Category: Uncategorized

  • Is It Better to Have Multiple Businesses Under One LLC?

    Is It Better to Have Multiple Businesses Under One LLC?

    Yes, it is possible to run multiple businesses under one LLC. This setup allows multiple business activities to be managed under a single legal company, which can simplify management, reduce costs, streamline operations, and reduce administrative work.

    However, business owners should consider whether the different businesses fit well together and make sense under the same LLC structure. It is also important to consult an LLC business attorney to determine whether this approach is appropriate for your specific situation.

    While operating multiple businesses under one LLC can be convenient, it also carries risks, including shared liability, which means legal or financial issues involving one business could potentially affect the other businesses operating under the same LLC.

    Can you have multiple businesses under one LLC?
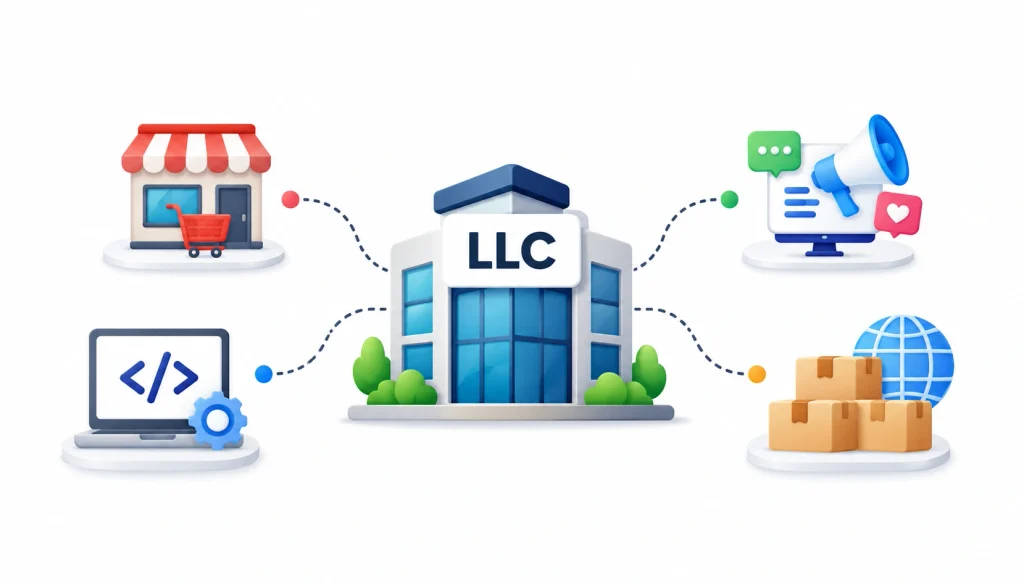
    One LLC managing multiple businesses, shown with retail, technology, marketing, and e-commerce icons connected to a central LLC building.

    Yes, in most U.S. states one LLC can run several business activities. An LLC is a legal entity. It is not limited to one product, one brand, or one type of work, unless your state, your license, or your own operating agreement says otherwise.

    Think of the LLC as a container. You can put one business in it or five. The state sees one company. Your customers might see five brands.

    Here is a simple example. Maria forms Ridgeway Ventures LLC. Under it she runs Ridgeway Consulting, Ridgeway Marketing, and Ridgeway Training. Legally, there is one company. Each brand is a trade name it operates under.

    If you want the background on how the LLC works as a structure, the Wikipedia article on limited liability companies is a decent starting point. The SBA’s guide to choosing a business structure covers the basics from a government source.

    Is it better to have multiple businesses under one LLC?

    It is generally more practical to operate multiple businesses under one LLC when the businesses are closely related, owned by the same people, and carry similar levels of risk. It can be less suitable when one business could expose the others to significant liability or when you may eventually want to sell, finance, or bring separate ownership into one business independently.

    The key question is not simply, “What is cheapest?” but rather, “What is the worst thing that could happen in each business, and am I comfortable with that risk affecting the others?” Business owners should also understand LLC tax filing for small business owners, including how the LLC’s tax treatment can affect reporting and tax obligations as the business structure becomes more complex.

    Consulting a qualified tax professional or business attorney can help determine whether using one LLC for multiple businesses fits your situation.

    One LLC may be the better fit when

    • You are the only owner of every business, or the same owners hold all of them.
    • The businesses carry similar and fairly low risk.
    • They are related, like consulting and training in the same field.
    • They share customers, tools, or staff.
    • You are testing a new idea and don’t want to pay for a new entity yet.
    • Keeping paperwork simple matters more to you than strict separation.

    Separate LLCs may be the better fit when

    • One business is much riskier than the others.
    • The businesses have different owners or investors.
    • One business owns valuable assets, such as real estate or equipment.
    • You might sell one business and keep the rest.
    • The businesses are in unrelated industries.
    • A state or industry rule pushes you toward separation.

    One LLC vs multiple LLCs: side-by-side comparison

    This table gives the general pattern. Your state and facts can change it.

    FactorOne LLCSeparate LLCs
    Formation costOne filing feeA filing fee for each LLC
    Ongoing feesOne annual report or franchise fee, in states that charge oneRepeated for each LLC
    Liability between businessesShared. One business’s debts and claims can reach the othersBetter separation between businesses
    BrandingMay need a DBA for each brand nameEach business can use its own legal name
    TaxesOne entity, but each business activity still needs clear recordsEach LLC has its own tax treatment
    AccountingCentralized, but you must track each business inside itSeparate books by default
    OwnershipEveryone owns the whole entityDifferent owners per business are easier
    Selling one businessHarder, since assets and contracts sit togetherCleaner, since the business is its own entity
    FinancingOne lender or investor looks at the whole entityLenders and investors can focus on one business
    Admin workloadLowerHigher

    Advantages of putting multiple businesses under one LLC

    1. Lower formation and administrative costs
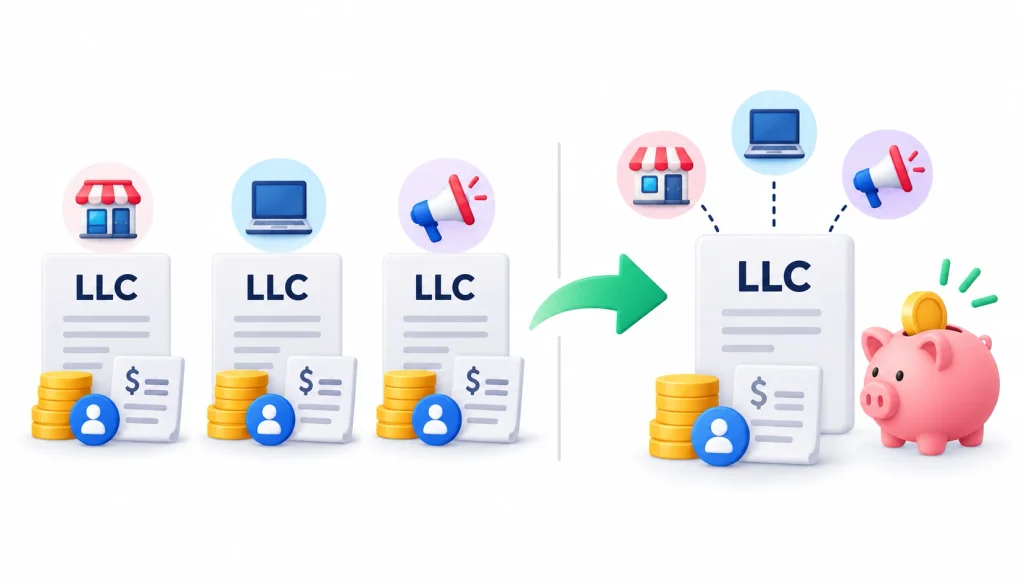
    Multiple LLCs with separate fees and administrative costs compared with one LLC, highlighting potential savings in formation and ongoing expenses.

    Every LLC comes with a state filing fee. Many states also charge annual fees or require annual reports, and you may need a registered agent for each entity. With one LLC, you pay those once. Fees vary a lot by state, so check your Secretary of State’s website for current numbers.

    2. Simpler management

    One operating agreement. One set of annual deadlines. One entity to keep in good standing. If you run everything yourself, that matters.

    3. Shared resources

    When your businesses use the same bank relationship, software, and team, one entity can be less awkward. You avoid billing one LLC for work done by another.

    4. Easier to test new ideas

    Launching a new service line under your existing LLC is quick. If the idea fails, you close a brand, not a company.

    Disadvantages and risks of multiple businesses under one LLC

    1. Shared liability

    This is the big one. An LLC separates your personal assets from the company’s debts in most situations. It does not build walls between businesses inside the same LLC. A claim against one business can generally reach assets used by the others.

    2. Messier accounting

    You can run clean books for several businesses in one LLC, but it takes discipline. Without separate tracking, you won’t know which business makes money.

    3. Harder to sell one business

    If a buyer wants only one of your businesses, you have to untangle contracts, licenses, bank accounts, and assets from the rest. That takes time and legal work.

    4. Different risk levels cause trouble

    A low-risk consulting practice sitting next to a business with employees, vehicles, or foot traffic is a mismatch. The safer business pays the price for the riskier one.

    5. Ownership and financing complications

    If a partner or investor wants into one business only, one shared LLC makes that awkward. They would own part of everything unless you restructure.

    How liability works when multiple businesses share one LLC

    Liability is where most people get this decision wrong, so it deserves a closer look.

    1. One LLC means one legal entity
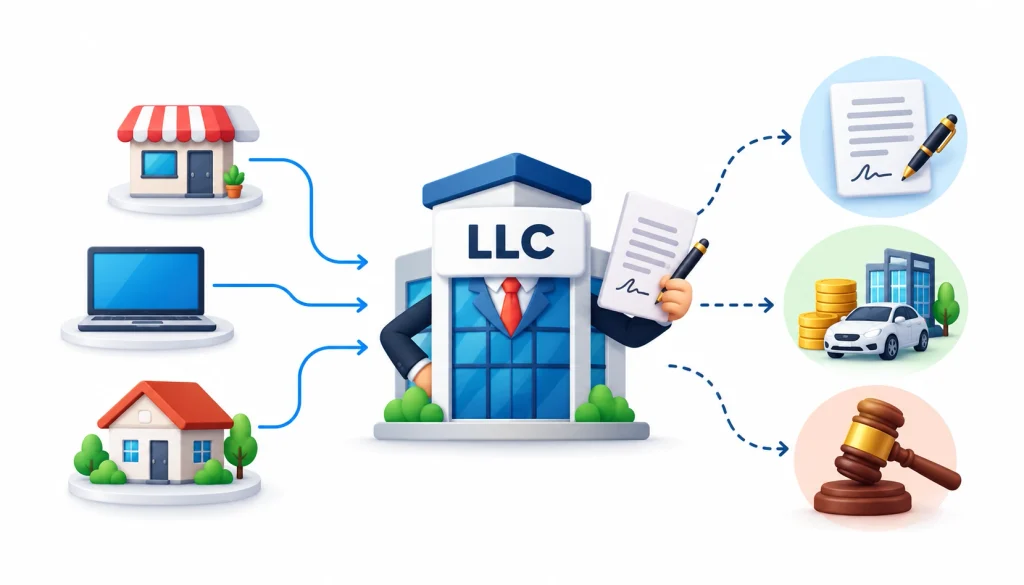
    One LLC serving multiple businesses while handling contracts, owning assets, and managing legal liability as a single legal entity.

    The law treats your LLC as one person-like entity. It signs contracts, owns assets, and can be sued. Your brand names do not change that. Whether you call a business “Ridgeway Consulting” or “Ridgeway Rentals,” the party on the contract is Ridgeway Ventures LLC.

    2. What happens if one business is sued?

    Say you run a small marketing agency and a short-term rental out of the same LLC. A guest is seriously injured at the rental and sues. The lawsuit names the LLC. The LLC’s assets, which may include the agency’s bank account and receivables, can be exposed to a judgment.

    Now change the setup. The agency is in one LLC and the rental is in another. The injured guest generally has to go after the rental LLC. The agency’s assets are usually out of reach, though a court can look at the facts. Insurance still matters in both setups.

    3. An LLC does not remove every risk

    An LLC does not protect you from your own wrongdoing or from personal guarantees you sign. If you guarantee a loan, the lender can come after you. Courts can also set aside LLC protection in some situations, an idea known as piercing the corporate veil. Mixing personal and business money is a common trigger.

    4. Why records matter

    Keep your LLC’s finances, contracts, and paperwork in order. Use a business bank account. Sign contracts in the LLC’s name. Follow your operating agreement and state filing rules. Good habits make it much easier to defend the structure if anyone challenges it.

    When should you use one LLC for multiple businesses?

    Here are the situations where one LLC tends to work well.

    Related businesses. A web design studio and a hosting service for the same clients are a natural pair.

    Similar risk. Two desk-based service businesses with no employees on site or heavy equipment share about the same exposure.

    Same owners. If every business has identical owners, shared ownership is not a problem.

    Shared customers and tools. When clients and resources overlap, one entity is easier to run.

    Early-stage experiments. Before a new idea earns money, paying for a separate entity may be premature.

    Small operations. For a solo owner with modest income, the savings in time and fees can be real.

    When should you consider separate LLCs?

    Here is when splitting usually makes sense.

    Different risk levels. Put the higher-risk business in its own LLC so a claim there stays contained.

    Different owners. If you run one business with a partner and another alone, separate entities keep ownership clean.

    Valuable assets. Real estate, expensive equipment, and intellectual property are often better held apart from a business that deals with the public. For businesses that also manage physical products, inventory management software can help maintain accurate records of stock and business assets.

    A planned sale. A buyer can purchase a standalone LLC more easily than a division of a shared one.

    Different investors. An investor in one venture usually does not want a share of unrelated ventures.

    Unrelated industries. If the businesses have nothing in common, there is little reason to tie them together.

    Regulatory rules. Some licensed professions and regulated industries have their own entity rules. Check your licensing board.

    How to run multiple businesses under one LLC

    If you go with one LLC, set it up carefully.

    1. Form the LLC. File articles of organization with your state and appoint a registered agent.
    2. Write an operating agreement. Even a single-member LLC benefits from one. List the business lines it will run.
    3. Register DBAs where needed. Most states require you to register a trade name if you operate under any name other than the LLC’s legal name.
    4. Open a business bank account. Consider tracking each business by sub-account or by class in your accounting software.
    5. Track income and expenses by business. You will want to know what each business earns and spends, especially when multiple businesses operate under the same LLC. Keeping separate financial records can make it easier to prepare accurate tax reports and understand the performance of each business. It can also help small business owners better understand CIS tax, including what it is, who it applies to, and how it affects payments and tax reporting.
    6. Check licenses and permits. Local, state, and industry licenses are often tied to the activity, not just the entity.
    7. Review insurance. Make sure your policies cover every activity the LLC runs. Tell your insurer what you do.
    8. Check your state’s rules. Fees, DBA filing places, and annual report rules are set at the state level, and sometimes the county or city.

    Do you need a DBA for multiple businesses under one LLC?

    Usually yes, if you use any name other than the LLC’s exact registered name.

    1. What a DBA is

    A DBA stands for “doing business as.” It is also called a trade name or fictitious name. It lets a company operate publicly under a different name. You can read a short overview on Wikipedia’s page on doing business as.

    2. When you need one

    If Ridgeway Ventures LLC wants to sell under the name Ridgeway Training, it generally needs to register that name. Where you register depends on the state. It might be the state, the county, or both.

    3. Can one LLC have multiple DBAs?

    Yes. Many states allow an LLC to register several trade names. Each one usually carries its own fee and renewal schedule.

    4. A DBA does not create a separate LLC

    This point trips up a lot of owners. A DBA is a name. It does not create a new legal entity and it does not wall off liability. If Ridgeway Training is sued, the defendant is still Ridgeway Ventures LLC.

    What is a Series LLC?

    A Series LLC is a special kind of LLC that lets you create internal “series,” each with its own assets and liabilities, under one umbrella entity. The goal is to get separation between businesses without forming a new LLC for each one.

    1. How it works

    In states that allow it, you file once for the master LLC and then set up series according to the state’s rules and your operating agreement. Each series is meant to keep its own records and assets.

    2. Limits you should know

    Only some states permit Series LLCs, such as Delaware, Texas, and Illinois. Rules differ widely. Some states have detailed requirements for how series must be set up and recorded. Courts outside those states may not treat series the way you expect, and banks, lenders, and tax agencies can handle them differently.

    If you operate in more than one state, get advice from an attorney who knows Series LLC law in each of them. Do not assume it works the same everywhere.

    3. What is a holding company structure?

    A holding company, sometimes called a parent LLC, owns other companies instead of (or in addition to) running a business itself. The companies it owns are subsidiaries.

    For example, Maria could form Ridgeway Holdings LLC. It would own 100% of Ridgeway Consulting LLC and Ridgeway Rentals LLC. Each subsidiary runs its own business and carries its own liability. The parent owns the shares or membership interests.

    This setup suits owners with several valuable or higher-risk businesses, or owners who plan to sell, bring in investors, or hold assets separately. It also adds cost and paperwork, since each subsidiary needs its own filings. See the Wikipedia overview of holding companies for general background.

    Tax considerations for multiple businesses under one LLC

    Taxes are where oversimplified advice does the most damage, so go slowly here.

    1. Legal entity vs tax classification

    An LLC is a legal structure. It is not a tax category. The IRS decides how an LLC is taxed based on its members and any elections it makes. The IRS page on LLCs explains the defaults.

    In general, a single-member LLC is taxed as a disregarded entity (reported on the owner’s personal return), and an LLC with two or more members is taxed as a partnership. Either kind can elect to be taxed as a corporation, including an S corporation, if it qualifies.

    2. Pass-through taxation

    Under the default rules, the LLC’s profit passes through to the owners and is taxed on their personal returns. The LLC itself does not usually pay federal income tax. That is not the same as owing no tax.

    3. Tracking each business separately

    Even when the IRS sees one entity, you should know the numbers for each business. A single-member LLC with several unrelated businesses may need to report each one separately on the owner’s return. Ask a tax professional how that applies to you.

    4. EIN considerations

    An EIN is an Employer Identification Number issued by the IRS. One LLC generally uses one EIN. Separate LLCs each need their own. A DBA does not get its own EIN. The IRS has a page on who needs an EIN if you want the official rules.

    5. State taxes

    States handle LLC taxes differently. Some charge a flat annual fee. Some charge a franchise tax based on income or net worth. Some require sales tax registration for each type of sale. Check your state revenue department.

    6. When to bring in a tax professional

    Talk to a CPA or enrolled agent when you have multiple businesses with different income levels, when you are thinking about an S corporation election, when you hire employees, or when you sell goods in more than one state.

    Should each business have a separate bank account?

    The LLC should have its own bank account, separate from your personal money. That part is not optional if you want to keep your liability protection solid.

    Whether each business needs its own account is a judgment call. Many owners open one account per business line because it makes bookkeeping simple. Others use one account and rely on accounting software categories. Both approaches can work.

    What matters is that you can answer, for any month, how much each business earned and spent. Never pay personal bills from the business account or deposit business income into a personal one.

    Here is a quick example. Ridgeway Ventures LLC has one bank account and one credit card. In the accounting software, Maria tags every transaction as Consulting, Marketing, or Training. At month end she can see that Training lost money while Consulting carried the company. She would not know that without the tags.

    Real-world examples: one LLC or multiple LLCs?

    Example 1: SEO agency and content writing. Same owner, same clients, similar low risk. One LLC is likely a sensible choice.

    Example 2: Software consulting and a rental property. The rental carries injury risk and holds a large asset. Most advisors would at least consider separate LLCs here.

    Example 3: Consulting and a high-risk physical business. Think of a consultant who also runs a landscaping crew with trucks and equipment. A single accident could hurt the whole LLC. Separation makes sense.

    Example 4: Two businesses with different owners. If you own one business with a partner and another alone, keep them in separate entities so each group owns only what it should.

    Example 5: Testing a new idea. You run a design practice and want to try an online course. Start under the current LLC with a DBA. If the course takes off or grows risky, move it into its own LLC.

    Decision tree: should you use one LLC or multiple LLCs?

    Work through these questions in order.

    1. Do all the businesses have the same owners?
      • No: consider separate entities.
      • Yes: go to question 2.
    2. Do they carry similar risk?
      • No: consider separate LLCs.
      • Yes: go to question 3.
    3. Does any one business own valuable assets, like real estate?
      • Yes: consider holding those assets in a separate entity.
      • No: go to question 4.
    4. Do you plan to sell or bring investors into one of them?
      • Yes: consider separation now.
      • No: go to question 5.
    5. Do they share customers and resources?
      • Yes: one LLC may make sense.
      • No: one LLC is still possible, but you have less reason to combine them.

    This is a general framework, not legal advice. A lawyer can tell you how your state’s rules affect the answer.

    One LLC vs multiple LLCs: cost and complexity

    Exact costs depend on your state, so I won’t give numbers. Here is what changes when you add LLCs.

    ItemOne LLCMultiple LLCs
    Formation filingOnceEach LLC
    Annual reports and feesOneOne per LLC
    Registered agentOneOne per LLC (often one provider can serve all)
    Bank accountsAt least oneAt least one per LLC
    BookkeepingOne set, tracked by businessSeparate sets
    Tax returnsDepends on classificationPossibly one per LLC
    Licenses and permitsPer activityPer LLC and activity
    InsuranceOne program covering all activitiesPolicies per LLC, or a shared policy with each named

    The extra cost of multiple LLCs is real, but it is often small next to what an uncovered lawsuit can cost. That trade-off is the heart of the decision.

    How to decide: a 7-factor checklist

    1. Liability risk. Which business could produce the biggest claim? If one is much riskier than the others, lean toward separation.
    2. Ownership. Same owners everywhere points to one LLC. Different owners point to several.
    3. Business assets. Valuable property or equipment often belongs in its own entity.
    4. Tax structure. Ask whether different tax treatment could help one business, such as an S corporation election.
    5. Administrative cost. Add up fees, accounting time, and filings for each option.
    6. Exit strategy. If you could sell a business in the next few years, set it up to be sold.
    7. State and industry rules. Check licensing, DBA rules, and Series LLC availability where you operate.

    Common mistakes when running multiple businesses under one LLC

    • Believing a DBA protects one brand from another.
    • Mixing personal and business money.
    • Not tracking each business’s numbers.
    • Skipping insurance or buying a policy that does not cover every activity.
    • Assuming tax and filing rules are the same in every state.
    • Forgetting local licenses and permits for each activity.
    • Waiting until a lawsuit or a sale to separate the businesses. Moving assets after a claim arises can be treated as an attempt to dodge creditors.

    Owners also compare notes in public forums. Communities like smallbusiness on Reddit are useful for hearing how others handled the same choice. Treat what you read there as personal experience, not legal advice.

    Frequently asked questions

    Is it better to have multiple businesses under one LLC?

    It is better when the businesses are related, have the same owners, and carry similar low risk. It is worse when risk, ownership, or assets differ a lot, or when you may sell one business separately.

    Can an LLC own multiple businesses?

    Yes. One LLC can run several business activities, and it can also own other LLCs as a parent company.

    How many businesses can one LLC have?

    Most states set no fixed limit. The practical limits come from your licenses, insurance, and how well you can keep records.

    Can one LLC have multiple DBAs?

    Yes, in most states. Each DBA is registered separately and may have its own fee and renewal.

    Does each business under an LLC need a separate EIN?

    Generally no. One LLC normally uses one EIN, and DBAs share it. Separate LLCs each need their own. Confirm with the IRS or a tax professional for your case.

    Are multiple businesses under one LLC taxed separately?

    Not as separate entities, in most cases. The IRS sees one LLC. But you still need to track each business’s income and expenses, and a tax professional can tell you whether you must report them separately.

    Does a lawsuit against one business affect the other businesses?

    It can. When businesses share one LLC, a judgment against the LLC can reach assets used by all of them. Insurance helps but may not cover everything.

    Should I have a separate LLC for each business?

    Not necessarily. Use separate LLCs when risk, ownership, assets, or exit plans differ. For small, related, low-risk businesses, one LLC can be enough.

    Final takeaway

    Is it better to have multiple businesses under one LLC? For related, low-risk businesses with the same owners, often yes. You save money and time, and the shared liability is a risk you may be willing to take.

    For businesses with different risk levels, owners, valuable assets, investors, or exit plans, separate LLCs usually make more sense. The extra paperwork buys you real protection and a cleaner path to selling.

    Before you decide, talk to a business attorney and a tax professional in your state. They can check the details this guide cannot see.
  • Fund Reporting Software: Features, Comparison & Buying Guide

    Fund Reporting Software: Features, Comparison & Buying Guide

    If you’ve ever spent a Friday night reconciling capital account spreadsheets before an LP call on Monday, you already know why fund reporting software exists. 

    It’s the category of tools that pulls fund data together, runs the calculations, and turns all of it into reports your investors, auditors, and regulators can actually use, without you rebuilding the same workbook every quarter.

    This guide walks through what fund reporting software actually does, how it’s different from fund accounting and fund administration tools, which platforms are worth a look, and how to pick one that fits your fund’s size, strategy, and stack. 

    We’ll also cover pricing, integrations, security, and where AI genuinely helps versus where it’s just marketing.

    What Is Fund Reporting Software?

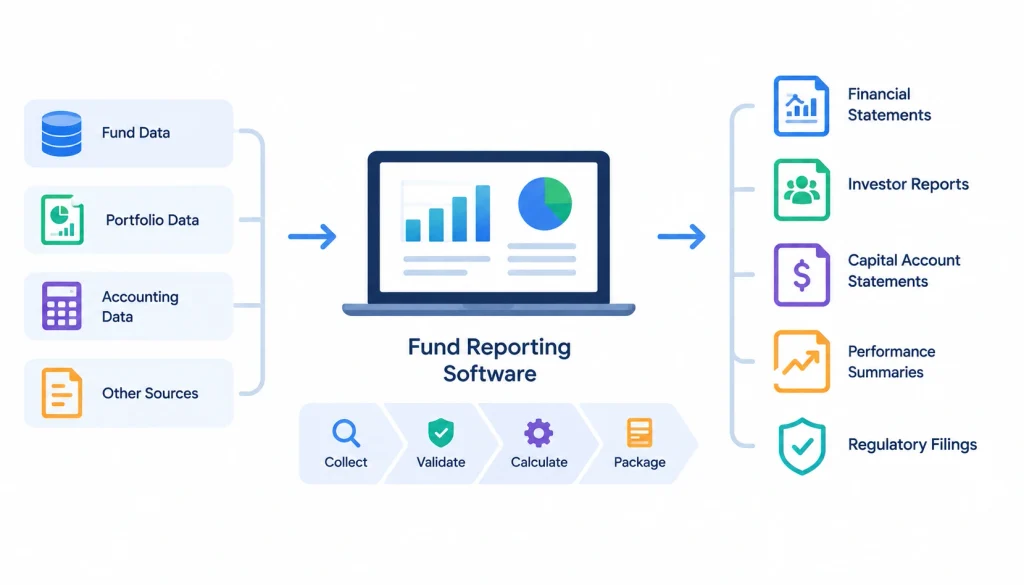
    Fund reporting software processing fund, portfolio, and accounting data into financial statements, investor reports, capital account statements, performance summaries, and regulatory filings.

    Fund reporting software is a platform that takes raw fund and portfolio data and turns it into finished reports (financial statements, investor letters, capital account statements, performance summaries, and regulatory filings) with far less manual work than spreadsheets require.

    Some platforms handle reporting on top of a general ledger they also maintain. Others sit above your existing accounting system and just handle the reporting layer. Either way, the job is the same: collect data, check it, calculate the numbers that matter, and package everything for the people who need to see it.

    1. What fund reporting software does

    At a practical level, these tools:

    • Pull data from accounting systems, portfolio trackers, and custodians
    • Consolidate numbers across multiple funds, entities, and currencies
    • Run standard calculations like NAV, IRR, and capital account rollforwards
    • Generate reports in the formats LPs, auditors, and regulators expect
    • Route drafts through review and approval before anything goes out
    • Deliver finished reports securely, often through an investor portal
    • Keep a record of who changed what and when, for audit purposes

    2. Who uses fund reporting software

    The buyers are usually general partners, fund controllers, and finance teams at investment firms, plus the fund administrators who handle back-office work on their behalf. Investor relations teams rely on it for LP communications, and compliance staff use it when regulatory filings are involved. A CFO at a mid-size PE firm and a one-person controller function at an emerging VC fund will use the same category of software very differently, but the underlying need, accurate reports with less manual effort, is the same.

    3. What types of funds use it

    Private equity, venture capital, private credit, real estate, hedge funds, and fund-of-funds vehicles all use some version of this software. So do family offices managing multiple entities and fund administrators serving several clients at once. The reporting requirements differ by strategy (a real estate fund cares about property-level rent rolls in a way a VC fund doesn’t), which is part of why fund-type fit matters so much in vendor selection, a point we’ll come back to.

    What Does Fund Reporting Software Actually Report?

    It helps to know what’s actually coming out the other end before you evaluate vendors on features. Reports generally fall into four buckets.

    Fund financial reports cover balance sheets, income statements, cash flow statements, general ledger detail, and net asset value (see Wikipedia’s overview of net asset value for the accounting mechanics). These are the books-and-records side of reporting.

    Investor and LP reports include capital account statements, capital call notices, distribution notices, and quarterly investor letters. This is the reporting LPs actually read, so formatting and clarity matter as much as accuracy.

    Portfolio reports track portfolio company or asset-level performance: valuations, KPIs, exposure by sector or geography, and investment-level returns like IRR and MOIC.

    Regulatory and compliance reports cover filings and disclosures required by regulators, along with the documentation auditors need at year-end. Depending on your jurisdiction and fund structure, this might mean Form PF, Form ADV, or other filings your compliance team tracks closely.

    Fund Reporting Software vs. Fund Accounting vs. Fund Administration

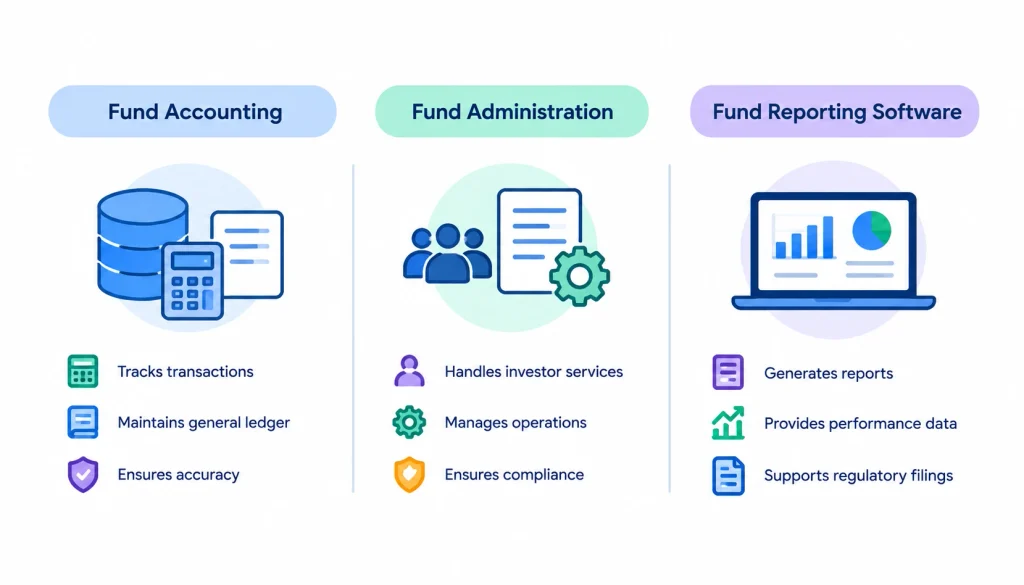
    Fund accounting vs fund administration vs fund reporting software comparison showing key functions and responsibilities.

    This is where a lot of buyers get confused, and honestly, vendors don’t always help. Many blur these categories in their own marketing because their products span more than one.

    CapabilityReporting SoftwareFund AccountingFund Administration
    Financial booksSometimesCore functionUsually
    Investor reportingCore functionOften includedOften included
    Portfolio monitoringVariesLimitedVaries
    LP portalOften includedSometimesOften included
    Regulatory reportingOften includedOften includedOften included
    Data consolidationCore functionCore functionCore function
    Administration workflowsLimitedLimitedCore function

    Fund accounting software keeps the books, while strong bookkeeping and accounting processes provide the underlying financial records that reporting systems rely on. Fund administration covers the broader operational work a back office does: accounting plus investor onboarding, capital calls processing, and more. Fund reporting software is the layer that turns whatever’s in the books into something a human can read and act on.

    When do you need one platform instead of multiple systems?

    If your fund is small and your data lives in one clean general ledger, a single combined platform usually makes sense: less integration work, one vendor relationship, one login for your team. Once you’re running several funds, multiple entities, or a mix of asset classes, the calculus changes. At that point, a dedicated reporting layer that pulls from whatever accounting system you already trust can be less disruptive than ripping out your books to adopt an all-in-one platform. Threads on privateequity and AccountingPE regularly cover this exact debate from people who’ve lived through both setups. Worth a read if you want unfiltered opinions before a vendor call.

    Key Features to Look for in Fund Reporting Software

    A few features separate genuinely useful platforms from glorified spreadsheet replacements.

    Automated report generation. The software should build reports from a template and live data, not require someone to copy numbers into a Word doc every quarter.

    Multi-fund and multi-entity reporting. If you run more than one fund or have SPVs and blockers in your structure, the platform needs to consolidate across all of them without manual workarounds.

    Investor and LP reporting. This includes capital account statements, capital call and distribution notices, and the ability to customize what each LP sees based on their commitment and side letter terms.

    Portfolio reporting. For PE and VC funds especially, you’ll want portfolio company KPI tracking and valuation support built in or well integrated.

    Financial consolidation. The system should combine data across entities and currencies correctly, including intercompany eliminations where relevant.

    Custom report builder. Templates rarely fit every LP’s requested format exactly, so the ability to adjust layout and content without an engineering ticket matters.

    Workflow and approval automation. Reports should route through review before they go out the door, with a clear record of who approved what.

    Audit trails and version control. Every change should be logged. This isn’t optional if you’re dealing with institutional LPs or auditors.

    Investor portal. A secure place for LPs to log in and retrieve their own documents, rather than everything going out over email.

    Regulatory reporting. Built-in support for the filings your fund type requires saves real time at deadline.

    Data validation and reconciliation. The software should flag numbers that don’t tie out, not just accept whatever gets fed in.

    APIs and integrations. Connections to your general ledger, portfolio monitoring tool, CRM, and data warehouse determine how much manual data entry survives implementation.

    Role-based access controls. Not everyone on your team, or at your fund administrator, should see everything.

    AI-powered reporting and analytics. Increasingly common, though the maturity varies a lot by vendor. More on this later.

    Best Fund Reporting Software Platforms to Consider

    A quick note on methodology before the list: this comparison is based on publicly available vendor documentation and product pages as of 2026. Where a claim comes directly from a vendor, we’ve noted it as such rather than presenting it as independently verified. Pricing and feature depth change often in this space, so confirm current details directly with each vendor before you commit.

    1. Quick comparison

    PlatformBest suited forAccountingInvestor reportingPortfolio reportingPortalIntegrationsPricing
    WorkivaEnterprise financial & regulatory reportingPartialYesVariesYesStrongCustom
    FISInvestment accounting across asset classesYesYesLimitedVariesStrongCustom
    EntriliaPE/VC firms wanting an integrated platformYesYesYesYesGrowingCustom
    AllvueMulti-strategy funds needing deep fund accountingYesYesYesYesStrongCustom

    2. Workiva

    Workiva positions itself around connected data and automated financial reporting for investment firms, with features for investor communications, regulatory filings, audit trails, and reporting across multiple funds. It’s built for organizations that need reporting to tie tightly into broader financial and regulatory workflows, not just LP-facing documents.

    3. FIS

    FIS markets its Investment Accounting Manager as a modular, SaaS-based platform that supports multiple investment types, asset classes, and accounting methodologies. It leans more heavily into the accounting side of the equation, which makes it a common choice for firms that need robust investment accounting first and reporting layered on top.

    4. Entrilia

    Entrilia takes a broader approach aimed at private equity and alternative asset managers, combining fund accounting with investor insights, an investor portal, portfolio monitoring, and data integrations. The company has also been building out agentic AI features for reporting workflows, which is worth asking about directly if that’s a priority for your team.

    5. Allvue

    Allvue combines fund accounting (including partnership accounting and a multi-currency general ledger) with investor reporting, cash management, and portfolio monitoring. According to the vendor, the platform runs on Microsoft Azure and Dynamics infrastructure with SOC 1 and SOC 2 alignment, and it explicitly supports PE, VC, private debt, CLOs, and fund-of-funds structures.

    6. Other platforms worth evaluating

    Depending on your fund type and size, it’s worth putting these on your shortlist too: eFront, Dynamo, Investran (now part of FIS’s Private Capital Suite), Juniper Square, Carta, FundCount, Chronograph, Visible, Cobalt, and Qapita. Some of these are full fund-accounting platforms; others are lighter-weight LP-reporting layers meant to sit on top of accounting data you already have elsewhere. Don’t assume two vendors in the same shortlist are solving the same problem; check which layer of the stack each one actually covers.

    Best Fund Reporting Software by Use Case

    Private equity funds typically need strong waterfall calculations, capital account tracking across multiple share classes, and portfolio company KPI reporting for their investment committee.

    Venture capital funds usually prioritize a simpler cap table and capital account structure but want fast, clean quarterly reporting and portfolio valuation tracking that doesn’t require a finance team the size of a PE shop.

    Private credit funds need reporting built around loan-level data (interest accruals, covenant tracking, and payment schedules), which not every platform handles well out of the box.

    Real estate funds need property-level reporting, rent rolls, and often more granular cash flow tracking than a typical PE platform is built for.

    Fund administrators managing multiple client funds need multi-client architecture, strict data segregation, and the ability to apply different reporting templates per client without duplicating work.

    Emerging fund managers are usually price-sensitive and need something they can implement quickly without a large operations team. This is where lighter LP-reporting tools sometimes beat full accounting platforms.

    Enterprise investment firms running many funds and entities need deep consolidation, strong API access, and enterprise-grade security more than they need simplicity.

    How Fund Reporting Software Fits Into Your Technology Stack

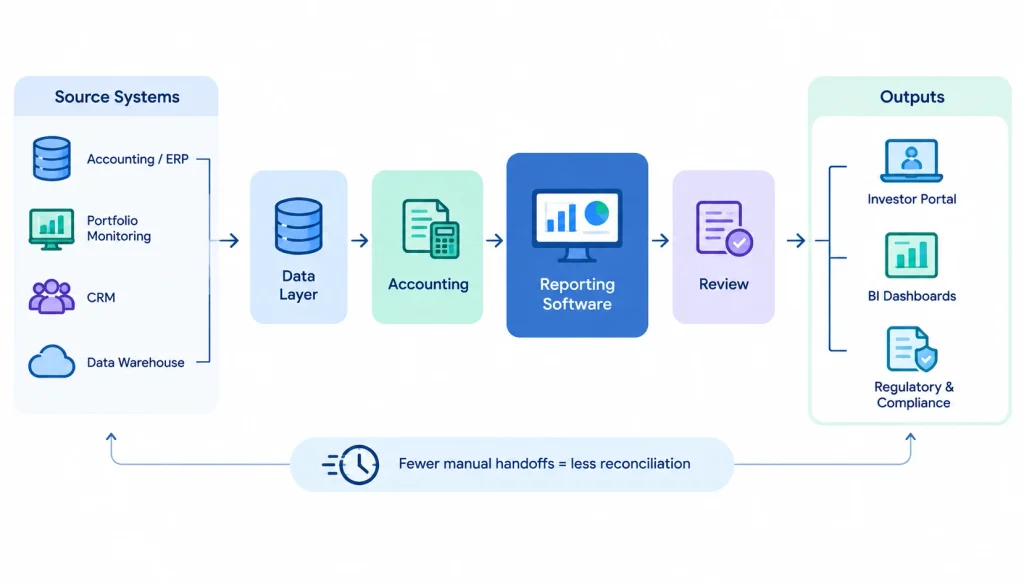
    Fund reporting software technology stack showing data flowing from source systems through accounting and reporting software to review, investor portals, BI dashboards, and regulatory compliance.

    Reporting software rarely works alone. It usually sits between your source systems and the reports that leave the building:

    Source systems → data layer → accounting → reporting engine → review → investor portal

    On the input side, It typically connects to your accounting or ERP system, including accounting software with analytics capabilities, a portfolio monitoring tool, your CRM for investor contact and commitment data, and sometimes a data warehouse if you’re consolidating from several sources. On the output side, it feeds your investor portal and, in some cases, your business intelligence tools for internal dashboards. Regulatory and compliance systems may also need a feed, depending on what you’re required to file.

    The fewer manual handoffs between these systems, the less time your team spends reconciling numbers that should already match.

    How Automated Fund Reporting Works

    Here’s the process most platforms follow, whether or not they market it this way:

    1. Collect fund and portfolio data from accounting systems, custodians, and portfolio trackers.
    2. Validate and reconcile data to catch mismatches before they end up in a report.
    3. Consolidate funds and entities, including intercompany eliminations where needed.
    4. Calculate performance and investor metrics, NAV, IRR, MOIC, capital account balances, and similar figures.
    5. Generate reports using templates mapped to the calculated data.
    6. Review and approve drafts internally before anything is finalized.
    7. Distribute reports securely, usually through an investor portal rather than email attachments.
    8. Preserve the audit trail so every number can be traced back to its source.

    Skipping steps 2 and 6 is how bad numbers end up in an LP’s inbox. Good software makes those steps hard to skip, not just possible to do.

    What Reports Should Your Fund Reporting Software Generate?

    ReportAudienceFrequencyPurpose
    NAV reportFinance, LPsMonthly or quarterlyFund valuation
    Capital account statementLPsQuarterlyInvestor position tracking
    Capital call noticeLPsAs neededFunding requests
    Distribution statementLPsAs neededDistribution details
    Portfolio reportGP, investment committeeMonthly or quarterlyInvestment monitoring
    Financial statementsFinance, auditorsQuarterly or annualFinancial reporting
    Performance reportGP, LPsQuarterlyFund performance
    Regulatory filingRegulatorsPeriodicCompliance

    How Much Does Fund Reporting Software Cost?

    Almost no vendor in this space publishes pricing on their website, which is frustrating but common for enterprise financial software. Expect a sales call before you see a real number.

    1. Common pricing models

    Pricing tends to follow one of a few patterns: custom enterprise quotes, per-user licensing, fees based on assets under management, fees based on the number of funds or entities managed, or modular pricing where you pay separately for accounting, reporting, and portal access.

    2. Additional costs to budget for

    The license fee is rarely the whole story. Budget for implementation, data migration from your existing spreadsheets or legacy system, integration setup with your accounting and portfolio tools, custom report template design, training, and ongoing support. On a mid-size implementation, these costs can add up to a meaningful fraction of year-one license spend.

    3. How to compare total cost of ownership

    Ask each vendor for a full first-year cost estimate, not just the license fee, and get a sense of what year two looks like once implementation is behind you. A cheaper license with expensive implementation can end up costing more than a pricier platform that’s faster to stand up.

    How to Choose Fund Reporting Software

    1. Define your reporting requirements. List the exact reports you need to produce today, plus any you expect to need as the fund grows.
    2. Map your current data sources. Know where your fund’s data actually lives before you evaluate anyone’s integration claims.
    3. Identify required reports. Match your list against what each vendor can actually generate out of the box versus what needs custom work.
    4. Define integrations. Confirm the platform connects cleanly to your accounting system, portfolio tools, and CRM.
    5. Evaluate security and compliance. Ask for SOC 1 or SOC 2 reports directly rather than taking a marketing page at face value.
    6. Test reporting workflows. Have your finance team walk through an actual quarterly close cycle in a demo environment, not just a canned presentation.
    7. Compare implementation requirements. Ask how long a comparable client took to go live, not just the vendor’s best-case timeline.
    8. Run a vendor demo using your own data. This is the single best way to catch problems before you sign a contract.

    Fund Reporting Software Demo Checklist

    Bring these questions to every vendor call:

    Data and integrations: Which systems does this connect to out of the box? What does a custom integration cost and how long does it take? Can it handle multi-currency data?

    Reporting: Can we build a custom report template ourselves, or does every change go through support? How are capital account statements generated per LP?

    Investor communications: Does the portal support side-letter-specific reporting? Can we control what each LP sees?

    Automation: What parts of the process still require manual data entry? How does the system flag data that doesn’t reconcile?

    Security: What certifications does the platform hold? Where is data hosted and stored?

    Scalability: How does pricing change as we add funds or entities? Has this platform been tested at our target scale?

    Administration: Can our fund administrator access the system directly if we use one?

    Support: What does onboarding look like, and who do we call when something breaks at 11pm before an LP call?

    Common Fund Reporting Challenges and How Software Solves Them

    Too many spreadsheets. When every fund, entity, and report lives in its own workbook, errors multiply fast. Reporting software consolidates that into one system of record.

    When financial data is scattered across systems, better financial management and reporting processes can help consolidate information and reduce manual work

    Duplicate data entry. Manually re-entering numbers between accounting and reporting tools wastes time and introduces mistakes. Integrations remove that step.

    Reconciliation problems. Numbers that don’t tie out between systems are one of the most common sources of delayed reporting. Built-in validation catches these earlier.

    Inconsistent investor reports. Without templates, report formatting drifts over time and between team members. A shared template library keeps things consistent.

    Manual report formatting. Copying numbers into a Word or PDF template by hand is slow and error-prone. Automated generation removes that bottleneck.

    Slow quarter-end close. Manual processes stretch out over weeks. Automated data collection and calculation can compress that meaningfully.

    Lack of auditability. Spreadsheets don’t track who changed what. Reporting software logs every edit.

    Data scattered across systems. Consolidation tools pull everything into one place instead of forcing your team to hunt across five logins.

    Growing fund and entity complexity. What works for one fund breaks down at five. Purpose-built software scales in a way spreadsheets don’t.

    Fund Reporting Software Implementation

    Implementation is where good software either pays off or turns into a headache. Expect these phases:

    Data migration:  moving historical fund data from spreadsheets or a legacy system into the new platform, and checking it matches. 

    System configuration: setting up your fund and entity structure correctly. 

    Integration setup:  connecting your accounting system, portfolio tools, and CRM. 

    Report template creation: building the templates your LPs and internal team actually need. 

    User permissions: setting role-based access for your team and any external stakeholders. 

    Testing and reconciliation:  running a full cycle against known numbers before going live. 

    Training and rollout: making sure your team can actually use the system day to day. 

    Ongoing optimization: refining templates and workflows as reporting needs change.

    Rushing the testing and reconciliation phase is the most common implementation mistake. It’s tempting to go live fast, but a platform that produces wrong numbers quickly is worse than a spreadsheet that produces right numbers slowly.

    Can Fund Reporting Software Replace Excel?

    1. Where Excel still works

    For a very small fund with one entity and a handful of LPs, a well-built spreadsheet can still get the job done. There’s no shame in that, and plenty of emerging managers run this way successfully for their first fund.

    2. Where Excel becomes risky

    Once you’re managing multiple funds, multiple entities, or a growing LP base, spreadsheets start breaking in predictable ways,  broken formulas, version control chaos, and no real audit trail. Institutional LPs also increasingly expect a level of reporting polish and security that a shared Excel file can’t provide.

    3. How software and Excel can coexist

    Most funds don’t do a clean cutover. It’s common to keep Excel for ad hoc analysis and modeling while moving the recurring, LP-facing reporting into dedicated software. That split keeps flexibility where you need it and control where it matters most.

    AI in Fund Reporting Software

    AI is showing up in most fund reporting platforms now, with varying degrees of actual usefulness.

    Automated report narratives: drafting the written commentary sections of an LP letter based on the underlying numbers, which a human then edits. 

    Data anomaly detection: flagging numbers that look off compared to historical patterns before a human catches them manually.

    Natural-language data queries: letting a finance team ask a question about fund data in plain English instead of writing a query. 

    Automated reconciliation assistance: speeding up the matching process between systems, though rarely replacing human review entirely. 

    Report generation: pulling data into a draft report faster than a manual process would.

    Risks and controls for AI-generated financial outputs

    None of this should replace financial controls. AI-generated numbers still need human review before they go to an LP or a regulator, the same way a junior analyst’s work would. If a vendor pitches AI as a way to skip review steps rather than speed them up, that’s worth pushing back on directly.

    Security and Compliance Requirements

    Fund data is sensitive, and LPs increasingly ask about security before they’ll even engage with a new fund. At minimum, look for SOC 1 and SOC 2 attestations, data encryption at rest and in transit, role-based permissions, detailed audit trails, version control on documents, clear data residency policies, support for the regulatory reporting your fund type requires, and a documented disaster recovery plan. Ask vendors for their actual SOC reports rather than accepting a badge on a marketing page, a real audit report will tell you exactly what was tested and when.

    Frequently Asked Questions

    1. What is fund reporting software? 

    It’s software that collects fund and portfolio data, runs the standard calculations, and generates the reports investors, auditors, and regulators need, replacing manual spreadsheet-based reporting.

    2. What is the difference between fund accounting and fund reporting software? 

    Fund accounting software maintains the financial books. Fund reporting software turns that financial data into finished, distributable reports. Many platforms today do both, but the two functions are conceptually distinct.

    3. What features should fund reporting software have? 

    At minimum: automated report generation, multi-fund consolidation, investor reporting, an audit trail, and integrations with your accounting and portfolio tools.

    4. How much does fund reporting software cost? 

    Most vendors use custom pricing based on fund size, number of entities, or user count, so expect a sales conversation rather than a published price.

    5. Can fund reporting software automate LP reporting? 

    Yes. Most platforms automate capital account statements, capital calls, distributions, and quarterly letters, though templates still need human review before distribution.

    Conclusion

    Choosing fund reporting software isn’t about finding the vendor with the longest feature list; it’s about finding a platform that fits your fund structure, reporting requirements, existing systems, and growth plans. 

    Look for strong accounting integrations, investor and LP reporting, multi-entity support, automation, security, audit trails, and reliable scalability, while considering the full cost of implementation and ongoing support. Before making a decision, run demos using your own data, test the workflows your team relies on, and ask detailed questions about pricing, integrations, implementation timelines, and support. 

    The right software should reduce manual work, improve reporting accuracy, and make every reporting cycle more efficient, not simply replace one complicated process with another.

  • 50 Work-From-Home Business Ideas You Can Start (And How to Pick the Right One)

    50 Work-From-Home Business Ideas You Can Start (And How to Pick the Right One)

    If you’ve searched “work from home business ideas,” you’ve probably already found a dozen lists. What most of them skip is the harder question: which one is actually right for you, what it costs to start, and how long before you land your first paying customer.

    This guide covers 50 work-from-home business ideas, organized by cost, skill level, and business model. More importantly, it gives you a framework for choosing one instead of leaving you with a bookmark you’ll never open again.

    Quick answers, if you’re short on time:

    • Best for beginners: virtual assistant work
    • Lowest startup cost: freelance writing
    • Best long-term scalability: digital products
    • Best for hands-on creatives: graphic design or content creation
    • Best if you want to sell physical products: e-commerce or print-on-demand
    • Best if you already have deep experience: consulting

    What Counts as a Work-From-Home Business?

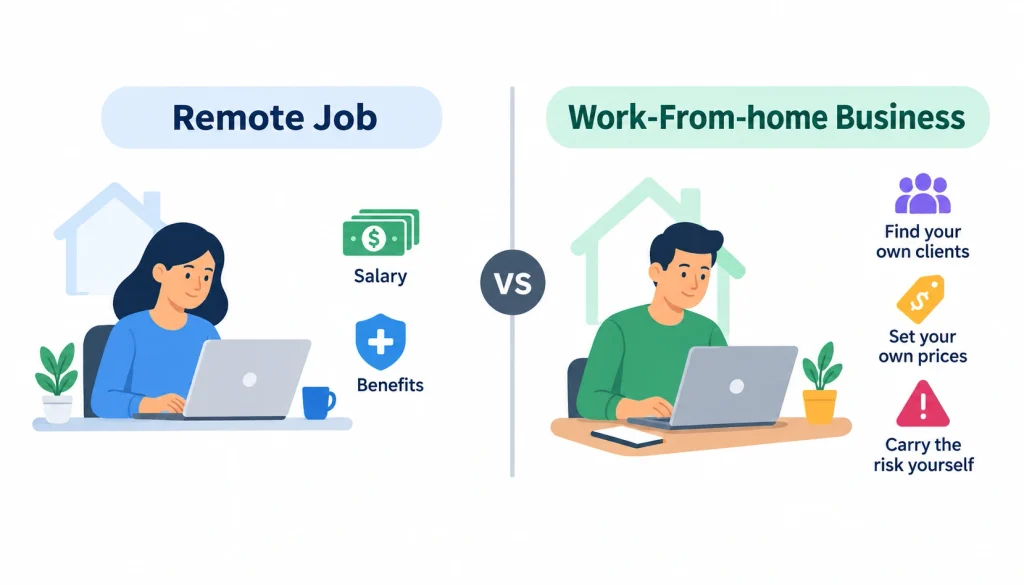
    Work-from-home business vs. remote job infographic showing salary and benefits for remote employees and clients, pricing, and business risk for home-based business owners.

    A work-from-home business is one you own and run yourself from your house, rather than a remote job where an employer pays you a salary. The distinction matters. A remote job gives you a paycheck and (usually) benefits. A home business means you find your own clients, set your own prices, and carry the risk yourself.

    A side hustle is really just a home business run part-time, alongside another job. Plenty of the ideas below started that way before becoming someone’s main income. And “online” doesn’t mean the same thing as “work from home”,  a home bakery or a pet-sitting service is run from your house but depends on local customers, not the internet.

    Best Work-From-Home Business Ideas at a Glance

    Before you scroll through 50 options, here’s a shortcut. This table compares the broad categories on the factors that actually determine whether you’ll stick with one.

    Business typeStartup costSkill levelTime to first customerScalability
    Freelance writingUnder $100Beginner to intermediateDays to weeksMedium
    Virtual assistantUnder $100BeginnerDays to weeksMedium
    Graphic/web design$100–$500IntermediateWeeksMedium
    Online tutoringUnder $100IntermediateDays to weeksMedium
    Bookkeeping$100–$500IntermediateWeeks to monthsMedium
    ConsultingVariesAdvancedWeeksMedium to high
    Digital products/courses$100–$500Intermediate1–3 monthsVery high
    Print-on-demandUnder $100BeginnerWeeksHigh
    Handmade products$100–$1,000Beginner to intermediateWeeksMedium
    Local services (cleaning, pet care)Under $500BeginnerDays to weeksLow to medium

    Costs and timelines are typical ranges, not guarantees — your actual numbers depend on your market, your pricing, and how much time you can put in each week.

    Low-Cost Service Businesses You Can Start From Home

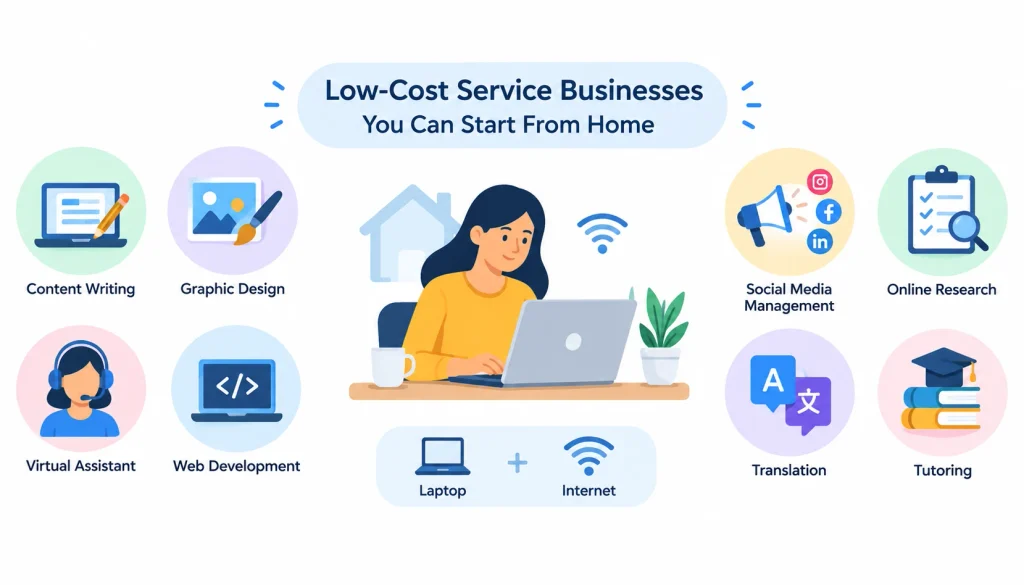
    Low-cost home-based service businesses infographic featuring content writing, graphic design, virtual assistance, web development, social media management, online research, translation, and tutoring, requiring only a laptop and internet.

    These lean on skills you already have, or can learn fairly quickly. Most require nothing beyond a laptop and internet connection.

    1. Freelance writing. You sell articles, blog posts, or copy to businesses that need content but don’t want to hire in-house. A portfolio of three to five sample pieces matters more than a degree. New writers typically find their first paying gig through freelance platforms like Upwork, then move to direct outreach once they have testimonials.

    2. Virtual assistant services. You handle email, scheduling, data entry, or customer support for busy business owners. This is one of the easiest entry points because clients care more about reliability than credentials. Many VAs start on retainer with a single client and add more as they build capacity.

    3. Social media management. You plan, create, and post content for small businesses that don’t have time to run their own accounts. Expect to show a client results, not just activity — engagement and follower growth are what get contracts renewed.

    4. Online tutoring. You teach a subject you know well, from math to a foreign language, over video call. Platforms like iTalki connect language tutors with students directly, and demand tends to spike around exam seasons.

    5. Bookkeeping. You manage a small business’s day-to-day finances using software like QuickBooks or Wave. This one rewards accuracy and discretion since you’re handling someone’s money. A basic bookkeeping certificate can help you land your first few clients faster.

    6. Graphic design. You create logos, social media graphics, or marketing materials for businesses and creators. A tight portfolio in one style beats a scattered one — clients hire designers whose past work already looks like what they want.

    7. Web design. You build and maintain websites, often on WordPress or Shopify, for small businesses that don’t have technical staff. Offering ongoing maintenance as a monthly retainer, not just one-off builds, is where the real recurring income sits.

    8. SEO consulting. You help businesses rank higher in search results through content, technical fixes, and link building. Understanding SEO for business can help you develop a stronger service offering and explain the value of SEO to potential clients.

    9. Translation services. You convert written or spoken content between languages for businesses, publishers, or individuals. Fluency alone isn’t enough — clients also want subject-matter familiarity, whether that’s legal, medical, or marketing content.

    10. Video editing. You cut and polish footage for YouTubers, businesses, or podcasters. Turnaround speed is often the deciding factor for repeat clients, since creators are usually working against a publishing schedule.

    11. Voice-over work. You record narration, ads, or character voices for clients who find you through casting platforms or direct outreach. A decent home setup (a quiet room and a good microphone) matters more than expensive studio gear when you’re starting out.

    12. Career coaching. You help clients with resumes, interview prep, or career transitions, usually over video calls. Credibility here often comes from your own career background, so lead with that experience when marketing yourself.

    13. Business consulting. You advise companies on strategy, operations, or a specific area where you have real expertise. This is the one idea on this list where “no experience” genuinely doesn’t work — clients are paying for judgment built on a track record.

    Online Business Ideas You Can Run Entirely From Home

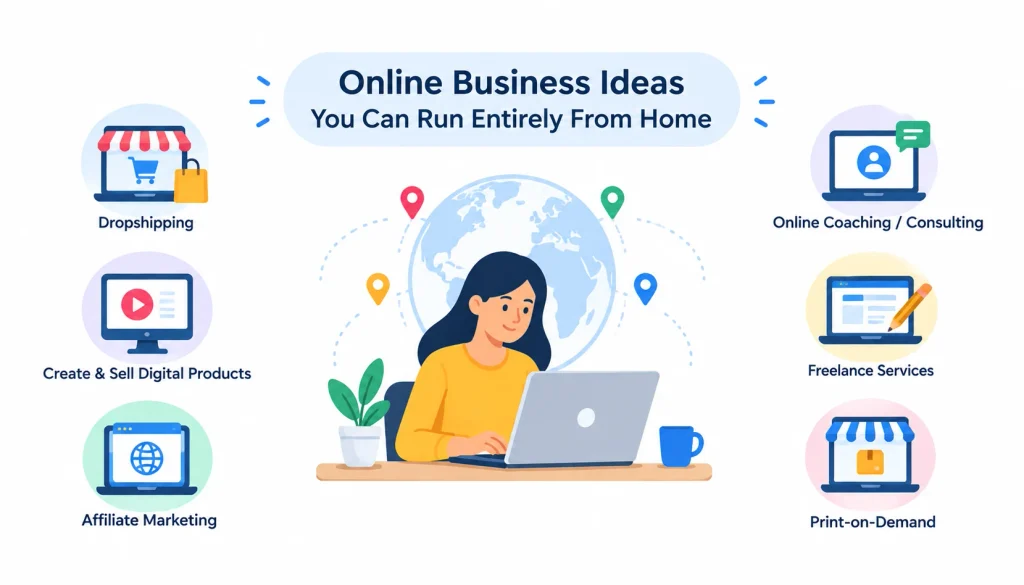
    Online business ideas infographic showing a woman working from home on a laptop, with examples including dropshipping, digital products, affiliate marketing, online coaching, freelance services, and print-on-demand.

    These businesses live mostly or entirely online, which means your customer base isn’t limited by geography.

    1. Affiliate marketing. You recommend products through content and earn a commission on resulting sales. It rarely pays off quickly, building the traffic and trust needed to convert readers usually takes months of consistent content in particular affiliate marketing niches.

    2. Blogging. You publish articles around a specific topic and monetize through ads, affiliate links, or your own products. Think of it less as a business on its own and more as a foundation other income streams get built on top of.

    3. YouTube channel. You create video content and earn through ads, sponsorships, or product sales. Consistency beats production quality in the early stages — channels that post on a schedule tend to outgrow ones that wait for the “perfect” video.

    4. Podcasting. You produce audio content and monetize through sponsorships, listener support, or by using the show to promote another business. Most podcasts take a year or more to build a monetizable audience, so treat it as a long game.

    5. Online courses. You package your expertise into a paid course, hosted on a platform like Teachable or Thinkific. This has one of the higher ceilings on this list, but it also demands real upfront work to validate that people will actually pay before you build it.

    6. Digital products. Templates, printables, spreadsheets, or simple tools you build once and sell repeatedly. Margins are strong because there’s no per-unit cost, but you still need an audience or marketing channel to find buyers.

    7. Membership or subscription community. You charge a recurring fee for ongoing access to content, coaching, or a community you run. This works best once you already have an audience — it’s hard to launch cold. Before launching, review the ⁠best membership platforms to find one that supports recurring payments, member access, and the type of content or community you plan to build.

    8. Newsletter business. You build a paid or ad-supported newsletter around a niche topic. This has grown quickly as a category over the past few years, largely because it’s cheaper to start than a full media outlet and easier to monetize directly through subscriptions.

    Product-Based Businesses You Can Run From Home

    These involve making or sourcing physical goods, so factor in supplies, storage, and shipping.

    1. Print-on-demand. You design graphics that get printed on shirts, mugs, or other products only after someone orders, so you never hold inventory. Margins per item are thin, which means volume and design quality both matter.

    2. Handmade products. You make and sell items like candles, jewelry, or home decor, often through Etsy or your own online store. Pricing is the most common early mistake — new sellers routinely underprice their time.

    3. Vintage or thrift reselling. You source secondhand items and resell them at a markup through platforms like eBay or Poshmark. This rewards people who genuinely enjoy hunting for finds, since sourcing takes real time.

    4. Subscription boxes. You curate a themed box of products that customers receive on a recurring basis. Customer retention is the whole game here — acquiring a subscriber is expensive, so keeping them matters more than the first sale.

    5. Dropshipping. You sell products online without holding inventory; a supplier ships directly to your customer. Margins tend to be thinner than people expect once you factor in ad costs, and supplier reliability makes or breaks the customer experience.

    6. Online boutique. You curate and sell a focused product line, usually clothing or accessories, through your own store rather than a marketplace. Once your store is live, an ecommerce SEO checklist can help you improve its search visibility and organic traffic.

    Creative Work-From-Home Business Ideas

    1. Photography. You shoot portraits, products, events, or real estate, depending on your niche. A focused niche usually books faster than a generalist portfolio, because clients searching for “newborn photographer” skip past a photographer who lists ten specialties.

    2. Illustration. You create custom artwork for books, brands, or products. Licensing your existing work for reuse, rather than only doing custom commissions, can add a second income stream on top of client work.

    3. Interior design consulting. You advise clients on room layouts, color schemes, and furnishings, often through virtual consultations. Before-and-after photos of past projects do most of the selling for you.

    4. Home organization services. You help clients declutter and organize their living spaces, sometimes in person, sometimes through virtual coaching. This one has grown alongside home-organization content on social media, which has made it easier to market with simple before-and-after posts.

    5. Craft business. You make and sell items like knitwear, pottery, or woodworking pieces. Selling at local markets alongside an online shop is a common way to build initial traction before relying purely on online traffic.

    6. Music lessons. You teach an instrument or vocal technique, in person or over video call. Referrals from current students are usually the strongest source of new ones.

    Local Businesses You Can Operate From Home

    Work from home doesn’t have to mean fully online. These depend on a local customer base but are still run and managed from your house.

    1. Personal chef or catering. You cook meals for clients or small events. Local health department rules on home kitchens vary widely, so check your local licensing authority before you take your first booking.

    2. Home baking business. You sell baked goods directly to local customers or through farmers markets. Many regions have “cottage food” laws that allow limited home food sales without a commercial kitchen — worth checking before you start.

    3. Cleaning business. You clean homes or offices, either solo or by building a small team over time. Liability insurance is worth the cost here, since you’re working inside other people’s property.

    4. Pet care. You offer dog walking, pet sitting, or boarding, often coordinated through apps like Rover. Reliability and trust drive repeat bookings more than anything else in this category.

    5. Childcare. You provide in-home childcare, subject to local licensing and safety requirements that vary significantly by state or country. Confirm the legal requirements in your area before you accept your first client, this is one of the more heavily regulated ideas on this list.

    6. Delivery services. You run local deliveries, whether independently or through an existing platform. Margins are thin per delivery, so this usually works better as a volume business or a bridge income while you build something else.

    7. Fitness coaching. You train clients one-on-one or in small groups, in person or over video call. A certification (from a body like NASM or ACE) builds trust with clients even where it isn’t legally required.

    Best Work-From-Home Businesses by Budget

    Under $100: freelance writing, virtual assistant work, tutoring, social media management, affiliate marketing.

    $100–$500: graphic design, bookkeeping, print-on-demand, a simple online course, a small handmade product line.

    $500–$1,000: web design (with paid tools and templates), a starter e-commerce store, professional photography equipment.

    $1,000+: larger inventory-based product businesses, catering with commercial-grade equipment, a fully built course platform with paid marketing.

    Best Work-From-Home Businesses With No Experience

    If you’re starting from zero, these tend to have the shortest learning curve:

    • Virtual assistant work, clients value organization and reliability over credentials.
    • Freelance writing, a few practice samples can substitute for a portfolio.
    • Reselling, sourcing and listing skills develop as you go.
    • Social media management , most of what you need can be learned from free content and trial and error.
    • Print-on-demand, no inventory risk while you learn what sells.
    • Online tutoring, subject knowledge you already have is the main requirement.

    Each of these still has a learning curve. Expect your first month or two to involve more learning than earning.

    Which Work-From-Home Business Is Most Profitable?

    This is the question everyone wants a straight number for, and no honest answer gives you one. Profitability depends on your pricing, your margins, how much demand exists for what you’re offering, and how efficiently you can serve customers, not on which category you picked.

    That said, some patterns hold up. Digital products and online courses tend to have the strongest margins because there’s no cost to produce another copy once the first one exists. Consulting and coaching can charge high hourly rates but are capped by your available hours unless you build a team. Product businesses can scale revenue quickly but usually carry thinner margins once you account for materials, shipping, and returns.

    ModelMargin potentialWhat limits it
    Digital products/coursesHighBuilding an audience to sell to
    Service/freelance workMediumYour available hours
    ConsultingHigh per hourYour capacity, unless you hire
    Product/e-commerceMedium to lowMaterials, fulfillment, ad costs
    Local servicesMediumGeographic reach

    Be skeptical of any article, including this one, that gives you a specific monthly income figure for a business idea. No legitimate home business guarantees a specific income, earnings depend on your skills, pricing, demand, and how consistently you show up.

    How to Choose the Right Work-From-Home Business

    Work through these questions in order rather than picking whatever sounds most exciting.

    Start with your skills. What do people already ask you for help with, or pay you to do in a job? That’s usually your fastest path to a first customer.

    Define your budget. Decide what you can afford to lose, not just spend, since early experiments don’t always work out.

    Decide how much time you actually have. Ten hours a week supports a different kind of business than forty. Be honest about this before you commit.

    Identify a real customer problem. Businesses that solve a specific problem for a specific person are easier to sell than vague “I offer everything” services.

    Check the legal requirements. Licensing, zoning, and insurance rules vary by location and by business type. A quick check with your local government website before launch saves headaches later.

    Consider scalability. Some businesses trade your time directly for money and have a ceiling. Others can grow without you personally doing more hours. Neither is wrong, just know which one you’re picking.

    How to Validate a Work-From-Home Business Idea Before Spending Money

    Most failed home businesses fail because the founder skipped this step and built first, then went looking for customers.

    1. Research who else is already doing something similar and how they’re pricing it.
    2. Talk to five to ten potential customers about the problem you think you’re solving — before you build anything.
    3. Search for existing demand: are people already asking for this in forums, Facebook groups, or on Reddit?
    4. Put together a minimum viable offer,  the smallest version of your service or product you could deliver this week.
    5. Try to land one paying customer with that minimum offer.
    6. Use what you learn from that first sale to refine the offer before you invest further.

    A quick, honest gut check on Reddit’s r/smallbusiness is a genuinely useful step here, searching whether others have tried something similar, and what went wrong for them, can save you months.

    How to Start a Work-From-Home Business, Step by Step

    1. Choose your niche. Narrower is usually better than broader when you’re starting out.
    2. Define your target customer. Know exactly who you’re selling to before you write a word of marketing copy.
    3. Validate the idea using the process above.
    4. Create your offer. Be specific about what’s included and what isn’t.
    5. Set your pricing. Base it on the value delivered, not just your hours.
    6. Handle registration, licenses, and taxes. Requirements vary by country and state, so check your local Small Business Administration or equivalent authority.
    7. Set up a simple website. It doesn’t need to be elaborate, it needs to explain what you do and how to contact you. Learn more about creating a business website and why it matters for your online presence.
    8. Set up payments and basic bookkeeping so money coming in is tracked from day one.
    9. Find your first customers through the channels that match where they already spend time.
    10. Build repeatable systems so the business doesn’t depend entirely on you reinventing the process every time.

    Tools You Need to Run a Home Business

    You don’t need every tool on this list before you start. Add them as the business actually requires them.

    • Website and domain: a basic site (WordPress or a simple site builder) so customers can find and vet you.
    • Payments: Stripe or PayPal to accept money without building your own payment system.
    • Accounting: QuickBooks or Wave to track income, expenses, and taxes from the start.
    • Communication: email and a scheduling tool like Calendly so clients can book time without back-and-forth.
    • Project management: something simple to track deliverables once you have more than one client at a time.
    • Marketing: a presence on whichever platform your customers already use, not every platform at once.
    • Cybersecurity and backups: basic password management and cloud backup, since losing client data is a real business risk, not just an inconvenience.

    How AI Is Changing Work-From-Home Businesses in 2026

    AI tools have shifted what’s efficient to do from home, and it’s worth understanding both sides before you pick a business.

    Business AI can be more efficient: content drafting, customer support responses, scheduling, basic research, and data entry. If your business involves a lot of repetitive writing or admin work, AI tools can meaningfully cut the time each task takes.

    Businesses more exposed to AI commoditization: generic content writing at scale, basic logo design, and simple translation are all areas where AI tools have gotten good enough that clients increasingly try the free option first. This doesn’t mean these businesses are dead — it means differentiation matters more than it used to.

    Human skills that remain valuable: original judgment, relationship-based trust (bookkeeping, consulting, coaching), physical services (cleaning, pet care, childcare), and anything requiring taste or a personal point of view. These are harder for AI to replace because the value isn’t purely in output speed.

    Practical ways to use AI in your business: drafting first versions of content you’ll edit, researching competitors, answering routine customer questions, summarizing meeting notes, and automating repetitive admin tasks. Treat it as a way to free up your time for the parts of the business only you can do, not as a replacement for your judgment.

    Common Work-From-Home Business Mistakes

    Choosing an idea because it looks profitable online, rather than because it fits your skills or actual market. Popularity in a YouTube video doesn’t mean there’s room for another seller in your specific niche.

    Spending money before validating demand. Buying inventory or building a course before confirming anyone wants to pay for it is the single most common way people lose their startup budget.

    Underpricing services, especially in the first few months. Low prices attract price-sensitive clients who are hardest to keep and rarely refer you to better ones.

    Trying to serve everyone. A narrow, specific offer converts better than a vague one, even though it feels like it limits you.

    Depending entirely on one platform for customers, whether that’s a single freelance marketplace or a single social app. Platforms change their algorithms and policies without warning.

    Ignoring taxes and legal requirements until it becomes a problem. Set aside money for taxes from your very first sale.

    Confusing revenue with profit. Money coming in isn’t the same as money you keep after materials, fees, software, and taxes.

    Expecting passive income immediately. Almost everything on this list takes active, consistent work for months before it starts to feel less demanding.

    Frequently Asked Questions

    What is the best work-from-home business to start? 

    There’s no single best option, it depends on your existing skills, budget, and available time. Virtual assistant work and freelance writing are strong starting points because they need little money and few specialized tools.

    What business can I start from home with no money? 

    Services that trade your existing skills for income, like virtual assistant work, tutoring, or freelance writing, can start with just a laptop and internet connection you likely already have.

    What is the easiest home business to start? 

    Virtual assistant work is often considered the easiest entry point because clients prioritize reliability and communication over formal credentials.

    What home businesses make the most money? 

    Digital products, online courses, and consulting tend to have the highest profit margins, largely because they don’t require materials or inventory. Actual income still depends on demand and how well you market yourself.

    Can I start a home business with no experience? 

    Yes. Virtual assistant work, reselling, tutoring, and print-on-demand all have a shorter learning curve than fields like consulting or bookkeeping, which usually require established expertise.

    Conclusion

    Fifty business ideas won’t get you anywhere on their own. What actually moves you forward is choosing one real problem, one specific audience, and one clear offer, then testing whether people are willing to pay for it before you invest serious time or money. Start small, get your first customer, listen closely to their feedback, and use what you learn to improve the offer.

    Once you know what works, focus on creating simple, repeatable systems for marketing, sales, customer service, and delivery. Only then does it make sense to think about hiring, expanding your services, or scaling the business.

    That’s the real answer to “work from home business ideas.” You don’t need an endless list of possibilities. You need one practical idea, a clear customer, a problem worth solving, and the willingness to test, learn, and improve. Start with what you can manage today, prove that it works, and build from there.

  • What Are Sundries? Everyday Essentials Explained

    What Are Sundries? Everyday Essentials Explained

    When you hear the term “sundries,” you might wonder, “What exactly does that mean?” Despite being a term not commonly used in everyday conversation, sundries play a significant role in both personal and business contexts.

    This blog will break down the meaning of sundries, explain their importance, and explore their applications in simple, factual, and easy-to-understand language.


    What Are Sundries?

    The word “sundries” refers to miscellaneous small items or articles that do not belong to a specific category. They’re often grouped together due to their varied nature, making them hard to classify. The term comes from the Old English word syndrig, which means “separate” or “distinct.”

    In modern use, sundries might include everyday items like toiletries, office supplies, or other small essentials. For instance, the toothpaste in your bathroom or the pens on your desk could fall under the category of sundries.


    Common Examples of Sundries

    Sundries vary widely depending on the context. Here’s a breakdown of common examples:

    1. Personal Use:
      • Toiletries such as toothbrushes, soap, and deodorant.
      • Small grooming tools like nail clippers or hairbrushes.
      • Miscellaneous items like sewing kits or travel-sized products.
    2. Business Use:
      • Office supplies like staplers, notepads, and paper clips.
      • Breakroom essentials, such as coffee filters or napkins.
      • Miscellaneous items purchased for daily business operations but not categorized elsewhere.
    3. Retail and Hospitality:
      • Sundries offered in hotel rooms, including shampoo, conditioner, and coffee packets.
      • Small merchandise items like souvenirs or snacks.

    Sundries in Accounting and Business

    In business, sundries have a special place in financial documentation. They are categorized as “sundry expenses,” a term used in accounting to record minor, irregular expenses that do not fit into standard expense categories.

    1. Definition of Sundry Expenses: Sundry expenses refer to small, infrequent costs that are not significant enough to warrant a dedicated account. Examples include postage, one-time purchases, or minor repairs.
    2. Why Are Sundry Expenses Important? Although they may seem insignificant, sundry expenses can add up over time. Properly tracking these costs ensures accurate financial reporting and helps businesses identify areas for cost-saving measures.
    3. Examples of Sundry Expenses in Businesses:
      • A company buying an extra set of printer ink for occasional use.
      • Travel-related expenses for one-off trips.
      • Small donations or community contributions made by the business.

    How Sundries Impact Everyday Life

    Sundries are an essential part of daily life, even if we don’t always recognize their importance. These small items often bridge the gap between comfort and inconvenience. Here’s how sundries influence our routines:

    1. Convenience: Having access to sundries can make life smoother. For example, carrying a spare pen or a small pack of tissues ensures you’re prepared for unexpected situations.
    2. Affordability: Sundries are usually low-cost items, making them accessible for most people. Their affordability means they can be replaced or restocked without significant financial strain.
    3. Preparedness: Sundries often include items that people purchase “just in case,” such as adhesive bandages, safety pins, or travel-sized hygiene products.

    How Businesses Use Sundries to Enhance Customer Experience

    Businesses, especially in the hospitality and retail sectors, leverage sundries to improve customer satisfaction:

    1. Hotels and Resorts: Many hotels provide complimentary sundries like shampoo, conditioner, and coffee pods. These small items can significantly enhance a guest’s experience, making them feel cared for.
    2. Retail Stores: Convenience stores often stock sundries such as snacks, batteries, and personal care items. Their availability allows customers to quickly pick up what they need without visiting a larger store.
    3. Offices: Companies often stock sundries in breakrooms or supply closets. Offering employees access to tea bags, notepads, or basic office tools boosts morale and productivity.

    What Is a Sundry Invoice?

    A sundry invoice is a type of invoice used to bill for miscellaneous or irregular items or services that don’t fit into standard categories. Businesses often issue these invoices to record minor or one-off transactions that are not part of their usual operations.

    Examples of Sundry Invoices

    • A repair shop billing for an unexpected part replacement.
    • A business charging for a small batch of products sold as an exception.
    • A retailer invoicing for items like packaging or delivery materials not typically sold.

    Why Are Sundry Invoices Important?

    Sundry invoices help businesses:

    1. Simplify billing for miscellaneous expenses.
    2. Keep accurate financial records for minor, irregular transactions.
    3. Ensure no revenue is lost, even for small or ad-hoc sales.

    Typically, sundry invoices include basic details like the item or service description, cost, date of transaction, and payment terms, making them straightforward to create and track.

    This simple approach ensures that businesses handle even the smallest details with precision and clarity.


    Frequently Asked Questions About Sundries

    1. What’s the Difference Between Sundries and Miscellaneous Items? While both terms refer to small, varied items, sundries are often physical, tangible objects, whereas miscellaneous items could include intangible things, such as odd services or unrelated tasks.
    2. Are Sundries Tax-Deductible? In many cases, businesses can claim sundry expenses as tax deductions, provided they are necessary for operations. Always consult a tax professional to ensure compliance with local laws.
    3. How Should Businesses Track Sundries? Keeping receipts and maintaining a detailed ledger for sundry expenses can help businesses stay organized. Some companies even create a dedicated budget line for such costs.

    Historical Context of Sundries

    The concept of sundries has been around for centuries. In earlier times, general stores carried “sundries” as an essential category of goods, including needles, thread, spices, and other small items needed by households. These shops catered to the needs of rural communities where access to specialty stores was limited.

    Over time, as retail evolved, the term became associated with convenience and versatility, reflecting the wide array of small items that people might need in their daily lives.


    Fun Facts About Sundries

    1. Sundries in Literature: Sundries often appear in historical novels and accounts, giving readers a glimpse into the daily lives of people from different eras.
    2. Evolution of Sundry Items: While sundries once included basics like candles and inkpots, today’s sundries range from power banks to travel-size hand sanitizers.
    3. Global Perspective: Different cultures have unique interpretations of sundries. In some countries, sundries may include spices or specific kitchen tools that are staples in local households.

    Conclusion

    Sundries might seem like a small and inconspicuous category, but their significance cannot be overstated. These everyday essentials make our lives more manageable, whether we’re at home, on the go, or running a business. By understanding sundries and their applications, we gain insight into how the little things can have a big impact.

    Next time you grab a pack of tissues or a spare battery, take a moment to appreciate the humble sundry. It might be a small part of your day, but it’s an essential one.