Category: Blog

  • What is business partnering, Know more.

    What is business partnering, Know more.

    Business partnering. It sounds fancy, doesn’t it? Like a corporate buzzword designed to make people sit up straighter in meetings. But the truth is, business partnering is far more than jargon; it’s a critical practice that’s reshaping the way organizations function in the modern world. It doesn’t have to feel overwhelming or complicated. Let’s break it down in the simplest terms so you can fully grasp what it’s really all about.

    What Exactly Is Business Partnering?

    At its core, business partnering is all about collaboration. Think of it as a bridge between different parts of an organization—most often between departments like finance, HR, or IT and the key decision-makers or operational leaders. Instead of working in silos, these departments partner actively with the broader team to ensure everyone’s goals and efforts align toward the same big-picture objectives.

    It’s not just about reporting numbers or delivering “support” from the sidelines (though, yes, those are part of it). Instead, it’s an involved and dynamic role where partners contribute strategic insight and work alongside leaders to steer the organization more confidently toward success. Imagine becoming more of a navigator than a backseat driver.

    colab

    Why Does Business Partnering Matter?

    Here’s why business partnering is changing the game for companies: it drives smarter, faster, and better decisions. Instead of resorting to outdated methods of working in isolation and passing off responsibilities, business partnering ensures that decisions are supported by both expert analysis and practical understanding.

    For example, let’s consider a finance business partner. Rather than only tracking expenses and ensuring budgets don’t spiral out of control, they actively collaborate with operational teams to analyze trends, forecast future outcomes, and suggest actionable strategies. They stop being gatekeepers of data and become trusted advisors. This shift toward collaboration also transforms how brands work with affiliates, influencers, and other partners through shared goals and transparency. A partnership marketing management platform centralizes these relationships, helping brands manage, measure, and scale them for real revenue impact.

    What Makes a Great Business Partner?

    Good question! Being a business partner isn’t just a title—it’s a mindset and a skillset. Here’s what separates effective business partners from the rest:

    • Strong Communication and Influence: Communication is key. Business partners must have the ability not only to convey their points clearly but also to influence and inspire others toward action.
    • Understanding the Business: You can’t be a partner if you don’t know the “partner” you’re working with. That means deeply understanding the goals, challenges, and realities of the teams you support.
    • Problem-Solving Skills: The role is all about solving real problems—not just identifying them or throwing numbers at people. Creativity and strategic thinking go a long way.
    • Flexibility: Let’s face it, no two organizations—or even days—are the same. A business partner needs the adaptability to handle all kinds of scenarios.

    The Core Components: What Really Makes Business Partnering Work

    Let’s talk about what makes business partnering truly click. It’s one thing to throw the term around your next meeting, but it’s quite another to put it into action and see it actually drive results. A strong foundation for effective business partnerships relies on a handful of essential building blocks. Here’s the good news: once you nail these down, you’re well on your way to unlocking collaboration that doesn’t just meet expectations—it exceeds them.

    1. Clarity in Roles and Expectations

    You know what they say—clear is kind. Everyone involved in business partnering needs to know who’s doing what and, more importantly, why. Without clear expectations and defined roles, you risk the dreaded double work (or worse, no one doing a critical task at all). Take the time to document priorities and responsibilities so each partner knows exactly where their expertise comes into play.

    Pro tip: Don’t stop at initial agreements. Scheduling regular check-ins to revisit roles and evolving objectives ensures that partnerships stay in sync and forward-looking.

    2. Trust and Transparency

    This one might sound cliché, but trust and transparency are the lifeblood of any solid business partnership. Why? Because successful collaboration means opening up about goals, challenges, and even vulnerabilities. If one side of the table is holding back, the potential for growth takes a serious hit.

    Transparency doesn’t happen overnight—it’s built over time with open communication and reliability. Keep your promises, share critical data, and encourage feedback. The more open the partnership, the better the outcomes.

    3. Mutual Strategic Alignment

    Think of business partnering as a dance. If both parties are moving to entirely different rhythms, everybody’s going to end up stepping on toes. Strategic alignment ensures energy is focused on shared goals—or at least complementary ones.

    How to nail it? Start by aligning on key business drivers and defining success metrics upfront. Everyone involved should understand how the partnership supports broader organizational objectives.

    4. Strong Communication Channels

    Have you ever tried coordinating a group text where half the people are silent, and the other half are typing novels? It’s chaos. The same goes for communication in business partnering. Establishing strong, consistent ways to communicate ensures everyone stays in the loop and conflicts are addressed early.

    Whether it’s weekly calls, shared dashboards, or a central project management system, find what works for the team and stick to it. Consistency is key to keeping collaboration running smoothly. With that in mind, enterprise unified communications can help bring all channels together, making it easier for everyone to stay aligned.

    5. Continuous Learning and Adaptation

    The world of business is anything but static. Market trends shift, priorities change, and new opportunities pop up. A successful business partnership knows how to embrace agility and adapt. Regularly assess what’s working, what’s not, and where tweaks are needed.

    Better yet, foster a mindset of continuous learning. Encourage partners to bring fresh ideas and creative solutions to the table. Staying adaptable ensures the partnership can weather challenges and seize opportunities,

    Beyond Numbers: How Business Partnering Connects Strategy and Execution

    Let’s face it – it’s easy to get caught up in the numbers. Reports, spreadsheets, data visualization dashboards… they can be dazzling! But business partnering is about something much bigger: bridging the gap between strategy and execution to create real, actionable value.

    Why Numbers Alone Aren’t Enough

    Numbers tell the “what” of the story – revenue growth, customer acquisition costs, quarterly profits – but they rarely explain the “how” or the “why.” This is where business partnering becomes a game-changer. When you focus solely on data, you risk creating a divide between strategic goals and the steps needed to achieve them. Business partnering, on the other hand, shifts the focus to collaboration, context, and aligning decisions with business direction.

    The truth is, numbers are just a foundation. But to build something meaningful, you need people, processes, and purpose. Business partners bring those missing elements to the table, ensuring that business strategies don’t stay trapped in presentation slides but come alive through thoughtful execution.

    The Golden Thread: Linking Strategy and Execution

    Think of business partnering as the golden thread connecting high-level goals with daily operations. It ensures that departments aren’t operating inside disconnected silos but are fully synchronized with the organization’s overarching vision.

    For example, imagine an organization sets a goal to improve customer experience. That’s the strategy. But how does this move from concept to reality? Here’s where business partnering enters the stage:

    • Defining actionable objectives: Business partners collaborate with teams – say, customer service and product design – to translate a broad goal like “better customer experience” into measurable, practical steps.
    • Tracking KPIs that matter: Not all metrics are created equal. Business partners identify which key performance indicators genuinely align with the strategy while leaving less relevant ones behind.
    • Removing roadblocks: Execution plans often hit hurdles. Business partners work to address organizational challenges, whether it’s clarifying priorities, reallocating resources, or streamlining communication.

    The Human Element: The Heart of Business Partnering

    Here’s something you might not hear enough: business partnering isn’t only about structure and strategy – it’s deeply human. At its core, it’s about communication and relationships. Business partners act as translators, communicators, and even negotiators, ensuring that everyone understands their role in achieving the strategy.

    Good business partners listen actively, ask probing questions, and facilitate challenging conversations between teams. By doing so, they ensure that strategies aren’t just “handed down” but are co-created and genuinely embraced by employees at every level.
    stamp

    The Evolving Role: How Business Partnering Fits into Modern Organizations

    Business partnering isn’t just a buzzword anymore, is it? It has truly evolved into a game-changer, carving a significant place for itself in how organizations operate today. So, what exactly makes it so essential in modern organizations? And how has its role grown from being “just another department” to becoming a key part of strategic success? Let’s dig into this transformation together.

    Why Business Partnering is No Longer ‘Nice to Have’

    Here’s the deal—organizations today face rapid changes: digital transformation, globalization, and unpredictable economic landscapes, to name just a few. Business partnering steps in to help bridge the gap between strategy and execution, ensuring that bold boardroom ideas don’t lose steam by the time they reach the frontlines.

    Modern organizations thrive on collaboration, shared knowledge, and making the most of their data. This is where business partners shine. They’re not just problem-solvers; they’re opportunity spotters. Their evolving role sees them diving deep into insights, communicating across multiple departments, and ensuring that everyone is pulling in the same direction. Talk about making a difference!

    From Back-Office to Frontline Contributors

    Traditionally, business partnering was often seen as a support function—a behind-the-scenes role ensuring things ran smoothly. But today, it’s much more than that. Business partners are increasingly stepping into strategic, people-facing roles that touch every part of the organization.

    They’re no longer sitting in the background crunching numbers or executing predefined tasks. Instead, they’re at the table with leadership, helping shape decisions that directly impact business outcomes. Whether it’s supply chain, product development, or company culture, business partners today are taking a hands-on role in driving forward innovative, cohesive solutions.

    The Intersection of Collaboration, Communication, and Analysis

    The evolution of business partnering boils down to three key elements: collaboration, communication, and analysis.

    1. Collaboration: Modern organizations value teamwork more than ever. Business partners work across departments, ensuring each part of the organization is aligned and contributing toward shared goals. They help break down silos—those pesky barriers that can stifle progress.
    2. Communication: Today’s business partners are storytellers. They’re not just throwing out stats; they’re contextualizing data, explaining why it matters, and making sure the whole organization speaks the same strategic language.
    3. Analysis: With an explosion of data in recent years, partners are expected to move from simply analyzing numbers to extracting meaningful insights. They’re helping leaders spot trends, uncover risks, and predict outcomes with greater accuracy.

    Adapting to the Future of Work

    As we move further into the digital age, the role of business partnering continues to evolve. Technologies like AI and machine learning are reshaping how businesses operate. Modern business partners are now expected to leverage these tools to find deeper insights and act as champions of innovation. Whether that’s automating routine tasks or driving conversations about sustainability, they’re at the forefront of impactful changes within organizations.

    And let’s not forget flexibility. The rise of hybrid workplaces means that business partners must adapt their communication styles, technologies, and approaches to work with teams that are increasingly distributed across time zones.

    Red Flags to Watch for When Implementing Business Partnering

    Business partnering can be a game-changer for organizations, creating stronger alignment between teams and driving strategic success. But, like any great idea, its success lies in the execution. As with any major initiative, implementing business partnering isn’t without its challenges. Spotting the red flags early can save your organization from derailment. Here are the key warning signs and what you can do about them.

    1. Lack of Clear Roles and Responsibilities

    One of the first red flags in any business partnering initiative is ambiguity around roles. Without clearly defined responsibilities, people end up pulling in different directions — and that’s a recipe for inefficiency.

    How to fix it: Start with a clear communication plan detailing exactly what each partner brings to the table. Define expectations, set measurable outcomes, and ensure everyone is on the same page from the beginning.

    2. Communication Breakdowns

    Let’s face it: solid business partnering relies on open, honest, and consistent communication. If team members aren’t communicating effectively, key details can slip through the cracks. Misunderstandings can breed mistrust, and suddenly, what began as a promising partnership feels like a tug-of-war.

    How to fix it: Invest time in building transparent communication channels. Host regular check-ins, encourage feedback, and create an environment where issues can be raised constructively. The right technology tools, such as collaboration platforms, can also help keep everyone connected.

    3. Focusing on Quick Wins Over Long-Term Strategy

    Achieving short-term success is wonderful, but when the focus shifts solely to quick wins, it can hinder long-term value. Business partnering is about creating synergies that support sustainable growth, not just ticking boxes in the present.

    How to fix it: Strike a healthy balance by celebrating quick wins but keeping long-term goals front and center. Regularly revisit your strategy to ensure all activities lead toward long-term objectives.

    4. Resistance to Change

    Humans are creatures of habit, and change can be uncomfortable. If employees perceive business partnering as a threat to their autonomy or feel it’s “just another restructuring,” implementation can face resistance at every level.

    How to fix it: Engage stakeholders early and often. Explain the benefits of the new model, collect team input, and emphasize how partnering empowers teams rather than replaces their contributions. Building a culture of trust is essential here.

    5. A Singular Focus on Data and Numbers

    Numbers are important in any business decision-making process, but relying solely on metrics without considering the human side is a red flag. Effective business partnering involves understanding people, processes, and systems—not just crunching numbers.

    How to fix it: Balance data-driven insights with qualitative input. Encourage discussions around team dynamics, culture, and customer impact alongside reports and analytics.

    6. Underestimating the Need for Training

    Business partnering requires skills that may be new to your team, from bridge-building to facilitating cross-departmental collaboration. If training is overlooked, even well-meaning efforts can fail.

    How to fix it: Offer continuous upskilling opportunities, such as workshops on collaboration or leadership training. Empower your team with the tools they need to thrive in this new role.

    7. Lack of Leadership Support

    No matter how invested your team is, without buy-in from senior leadership, business partnering can lack the momentum needed to succeed. A lack of leadership support often manifests as unclear priorities or a lack of resources.

    Making Business Partnering Practical: The Power of Tools and Techniques

    Let’s cut to the chase—business partnering sounds great on paper, but how do you actually make it work? That’s where tools and techniques come in. Think of them as the ingredients in your favorite recipe. Without the right tools, even the most brilliant strategy will struggle to come to life. The good news? There are plenty of practical ways to enable effective business partnering—and we’re about to dig into them in a way that’s helpful, straightforward, and kind of exciting (yes, I said exciting!).

    Start with the Right Tech Stack

    Technology is, without a doubt, one of the most empowering enablers of modern business partnering. Having the right tools not only saves you time but helps you work smarter. Let’s break this down:

    • Data Analytics Platforms: Tools like Power BI or Tableau are fantastic for providing real-time insights. Collaborating effectively means having a shared understanding of the data, and dashboards can help people get on the same page faster.
    • Collaboration Software: Platforms like Microsoft Teams, Slack, or Zoom are essential for building ongoing relationships and sharing ideas, especially if remote teams are involved.
    • CRM Tools: For functions like finance or HR partnering with other departments, CRM systems can help track interactions and tailor solutions to internal stakeholders.

    The idea isn’t to overwhelm yourself with every tool on the market. Keep it simple, evaluate your needs, and choose platforms that add real value to your process.

    Focus on Process Mapping

    Let’s talk about processes—because they matter. If you feel like business partnering occasionally lacks direction, process mapping might be your hidden gem. It’s essentially about visualizing the flow of ideas, actions, and decisions between teams.

    Here’s how to get started:

    1. Map out the journey of a typical business issue or strategy across departments.
    2. Identify bottlenecks or where communication tends to break down (hint: this is where partnering gets vital).
    3. Use this map to craft a clear, step-by-step approach to collaboration—who leads what, where data flows, and how feedback is implemented.

    Process mapping may not sound glitzy, but trust me, it works wonders for clarifying roles and keeping everyone aligned.

    Invest in Soft Skills Training

    Surprise! Tools aren’t limited to software or frameworks. One of the most underrated aspects of business partnering success is the human side. You might have a top-tier ERP system or brilliantly automated processes, but if teams don’t communicate effectively, those tools won’t stand a chance.

    Here’s where soft skills training comes in. Encourage skills like:

    • Active Listening: Partnering is as much about understanding others’ needs as it is about offering solutions.
    • Empathy: This helps teams build trust and foster long-term relationships—an absolute must for any partnership to thrive.
    • Negotiation: Sometimes, partnering means finding common ground while still pushing your department’s priorities forward.

    These skills aren’t just “nice-to-haves.” They’re game-changers, turning everyday interactions into true opportunities for collaboration.

    Measure, Assess, and Adjust

    Finally, remember that business partnering is not a “set it and forget it” process—it’s dynamic. To stay effective, you’ll want to measure how well your tools and techniques are working. Here’s how:

    • Look at key metrics that matter: Is decision-making faster? Are relationships improving? Are initiatives achieving results?
    • Gather feedback from stakeholders—even if it’s critical. Honest input helps you refine your approach.
    • Be willing to pivot. If something isn’t working, don’t be afraid to adapt your methods or even test out new tools.

    Monitoring progress and making adjustments will keep your business partnering on point, ensuring it continues delivering value over time.

    Real-World Applications of Business Partnering: Lessons from the Field

    Business partnering can sound like a high-level, theoretical concept, but its real magic happens out in the field. This is where strategies turn into action, problems evolve into solutions, and organizations truly thrive. Let’s explore how companies and leaders around the world are leveraging business partnering in practical, real-world scenarios—and uncover what we can all learn from their experiences.

    1. Driving Innovation Through Collaborative Partnerships

    One of the most impactful applications of business partnering is fostering innovation. Take the tech industry, for example. Organizations often pair financial experts with product managers to help weigh the costs, risks, and rewards of pursuing new ideas. The result? Financial insights guide the feasibility of cutting-edge products, while creativity still takes the lead.

    Lesson: The key to success here is striking the right balance between visionary thinking and pragmatic decision-making. By partnering across departments, these companies nurture big ideas while staying grounded in financial and operational realities.

    2. Elevating Decision-Making at All Levels

    In retail, streamlined decision-making is critical. For instance, consider a global retail chain striving for faster, data-driven choices. They integrated business partnering by embedding analysts directly into regional management teams. These analysts essentially became strategic advisors—offering localized, real-time insights into customer data, trends, and sales patterns.

    Lesson: Business partnering can empower decision-makers by putting expertise right where they need it. When your team has easy access to specialized knowledge, it reduces guesswork and boosts confidence at all levels.

    3. Turning Financial Insights into Strategic Action

    In the manufacturing industry, financial and operational teams frequently collaborate to identify waste in production lines. Through business partnering, supply chain managers might work directly with finance teams to estimate cost-saving opportunities. Together, they can prioritize the most rewarding operational changes.

    Lesson: Business partnering is not just about crunching numbers; it’s about shaping decisions. In this case, financial expertise breaks out of spreadsheets and becomes an integral part of the company’s overall strategy, paving the way for cost and time efficiencies.

    4. Strengthening Cross-Functional Collaboration

    In healthcare, collaboration is vital. Hospitals, for example, often rely on business partnering to improve patient outcomes while managing budgets. Here, clinical staff frequently work with finance and HR professionals to ensure staffing matches patient care needs. This synergy creates a functional and sustainable balance between resources and quality care.

    Lesson: Business partnering thrives when it fosters collaboration across traditionally siloed departments. When teams gather around common goals—whether it’s improving care or reducing expenses—they align their efforts toward success.

    5. Adapting to External Challenges

    An excellent example emerged during the COVID-19 pandemic, where many companies relied on business partnering to adapt swiftly and effectively. In one instance, a multinational company tasked their finance business partners with closely monitoring supply chain disruptions. This helped their leadership team make proactive adjustments to sourcing strategies and maintain profitability, even in uncertain times.
  • What is a business debt schedule

    What is a business debt schedule

    Have you ever found yourself feeling overwhelmed trying to keep track of business loans, due dates, interest rates, and lenders? If so, it’s not just you – managing debt effectively can be challenging, but here’s the good news: a business debt schedule could be your new best friend! So, what is it exactly? Let’s dive in.

    At its core, a business debt schedule is a comprehensive tool used to manage and summarize all of your business’s liabilities in one place. Think of it as a snapshot of all the debts your business owes, neatly organized for easy reference. It’s like your personal assistant for keeping you mindful of financial obligations without all the heavy lifting. No more flipping through countless loan agreements or piecing together spreadsheets – the debt schedule does it all for you.

    manage

    Why Does It Matter?

    Running a business often involves taking on debt, whether it’s for purchasing inventory, expanding your operations, or managing everyday cash flow. But debts need to be tracked and planned for – otherwise, you might find yourself caught off guard by sudden repayment deadlines or overlooked interest rates.

    Here are three ways a debt schedule can make a difference:

    1. Clarity at a Glance: By listing every single debt in one place, you’ll have a crystal-clear view of how much your business owes, when payments are due, and any additional conditions tied to your loans.
    2. Improved Decision-Making: Are you planning to take on more debt? By reviewing your debt schedule, you can better understand whether your business has room to borrow more or if it’s time to focus on paying down existing obligations.
    3. Preparation for Investors or Lenders: Banks and potential investors want to see your financial health boiled down into one document. A well-organized debt schedule signals that you have a good handle on your finances and can repay your commitments responsibly.

    What Goes Into It?

    Before you start visualizing a lengthy, confusing document, let’s set the record straight: a business debt schedule is surprisingly simple once you understand the basics. Typically, it should include:

    • Lender Information: Who are you borrowing from? Whether it’s the bank, private investors, or suppliers, logging the source of each debt is key.
    • Loan Amounts: What’s the total principal borrowed? This is the starting point for tracking how much you owe.
    • Interest Rates: Loans often come with different terms, so keep track of each rate to plan how they’ll impact your budget.
    • Repayment Terms: When are repayments due? Are they monthly, quarterly, or annually? Knowing the schedule ensures you never miss a deadline.
    • Outstanding Balances: Even if the loan amount was higher at the start, your focus should always be on what’s still owed.

    Why Every Business Needs a Debt Schedule

    At its core, business is all about balance. Balancing costs, revenues, and investments is what keeps a company afloat. When it comes to debt, things can quickly spiral if not properly managed. That’s where a debt schedule comes in. It’s more than just a spreadsheet tracking your loans—it’s an essential tool for your financial strategy. But why is it so important?

    1. A Clear Picture of Financial Health

    Think of your debt schedule as a bird’s-eye view of what you owe and when. It’s your ultimate cheat sheet for understanding how your liabilities stack up. By listing out every loan, line of credit, and outstanding debt, along with their due dates and interest rates, you can get a crystal-clear picture of your company’s financial health at a glance.

    Without this clear panorama, you might be flying blind. A debt schedule transforms what would otherwise be a chaotic jumble of numbers into a streamlined, organized plan.

    2. Better Cash Flow Management

    Cash flow is the lifeblood of any business. Mismanaging it can be dangerous, especially if you’re juggling multiple repayments or interest obligations. A debt schedule ensures that your revenue isn’t blindsided by unexpected outflows. By having all your debt information in one place, you can easily see:

    • Which payments are coming up soon
    • How much of your budget goes toward servicing loans
    • What’s left over for growth opportunities

    Ultimately, a debt schedule helps you prepare and maintain enough liquidity to meet your obligations without cutting into your profit margins.

    3. A Boost to Strategic Planning

    It’s not just about tracking what you owe; it’s also about fine-tuning your approach to growth. Are you thinking about expanding? Taking on new funding? Negotiating better loan terms? Having a well-maintained debt schedule equips you with the insights to make smarter, more strategic decisions. You’ll be in a much better position to pitch to investors or lenders when you can show them exactly how you’re managing your debt.

    In essence, your debt schedule works double-duty—it helps you avoid risky missteps while empowering you to identify smarter, more calculated opportunities.

    4. Ensuring Compliance and Avoiding Late Fees

    No one likes penalties or scrambling to make last-minute payments. A debt schedule ensures you meet all your obligations punctually, preventing unnecessary late fees or breaches of loan terms. Automating your debt schedule with reminders or alarms (or using tools—more on this later!) is a game-changer. It adds a layer of accountability, so you’re never caught off-guard.

    5. Simplifying Communication with Stakeholders

    Lastly, clear financial records can make life a lot easier for everyone—from new investors to your CFO. A debt schedule serves as a one-stop shop for your debt data. Whether someone wants to know your current loan balances or the interest rates you’re paying, the information is available in one concise, organized format.

    debt

    Breaking Down the Components: What to Include

    Let’s talk about the nitty-gritty of a business debt schedule — the detailed info that makes this tool so invaluable to managing your finances. A debt schedule isn’t just a random list of what you owe. Nope, it’s a carefully-structured document that organizes key data about all your financial obligations in one simple, clear format. So, what exactly should it include? Don’t worry, I’ll walk you through it step by step!

    The Essentials: What Every Debt Schedule Needs

    Your debt schedule is only as good as the information you put into it. Here’s what should always make the cut:

    • Creditor Name: Who do you owe money to? This could be a bank, a credit company, or any lender you’ve borrowed from. Listing each creditor is crucial for clarity.
    • Loan Description: Briefly describe each loan. Is it a term loan? A line of credit? Equipment financing? Categorizing loans makes it easier to understand the nature of each debt.
    • Original Loan Amount: Keep track of the full amount borrowed. This helps provide perspective on how much debt you’ve managed to pay off and how much remains.
    • Outstanding Balance: Let’s face it, this is what matters most: how much you still owe. Updating this regularly keeps your schedule accurate and actionable.
    • Interest Rate: Jot down the rate for each debt. Why? Because this figure tells you how expensive the loan is and helps prioritize repayments. The higher the interest rate, the more it’s costing you overall.
    • Repayment Terms: Outline how the loan is being paid back. Is it monthly or quarterly? Over five years or ten? Tracking these terms ensures you’ll never miss a due date.
    • Payment Due Date: Speaking of dates, make sure every payment due date is highlighted. Consider this your “don’t-miss-this-deadline” section. Lenders often rely on loan business software to monitor these schedules and ensure timely repayments across multiple borrowers.
    • Collateral (if applicable): Some loans are secured against business assets like equipment or vehicles. If that’s the case, list the collateral here for a full picture.

    Each of these elements plays a vital role in helping you grasp your financial position and maintain better control over your obligations.

    Taking It Up a Notch: Optional Add-Ons

    If you really want to stay ahead of the game, consider adding these extras:

    1. Loan Maturity Date: Knowing when a loan will be fully repaid helps you plan for the future.
    2. Monthly Payment Amount: Seeing exact dollar amounts of regular payments gives you a clear view of your monthly cash flow needs.
    3. Early Payment Terms: Some loans come with penalties or perks for early repayment. Recording these can help you evaluate options if cash flow improves.
    4. Notes Section: Keep space for observations. For example, you could track whether a creditor has been flexible with terms or if there are opportunities to refinance at a better rate.

    Step-by-Step Guide to Building a Debt Schedule

    Creating a business debt schedule might sound overwhelming at first, but trust me, it’s simpler than you think—and oh-so worth the effort! Let’s jump into a step-by-step approach that’ll help you stay organized and in control of your business’s financial commitments. Ready? Let’s go!

    1. Gather All the Data You Need

    The first step is organizing all the financial details related to your debts. This includes every loan, line of credit, or other liabilities hanging over your business. Be as thorough as possible here. Double-check invoices, credit agreements, and bank statements so you don’t miss anything.

    • Loan agreements and terms (interest rates, due dates, or any penalties).
    • Monthly payment amounts.
    • Balances and outstanding principal.
    • Names of lenders or creditors.

    Having all this in one place ensures you won’t have to dig through endless paperwork later. Think of it as building the foundation of your debt schedule. Solid foundation, smooth process.

    2. Choose the Right Format

    Next, think about how you’ll actually structure this schedule. Many people use spreadsheets because they’re flexible, user-friendly, and easy to update. Tools like Excel, Google Sheets, or even specialized apps and accounting software can do the trick.

    Your debt schedule should have clear columns for:

    • Creditor Name (who you owe the money to).
    • Original Loan Amount.
    • Outstanding Balance.
    • Interest Rate (to track how much ‘extra’ you’re paying).
    • Payment Amount (monthly/quarterly).
    • Maturity Date (when everything is due).
    • Collateral (if any).

    Keeping it clean and straightforward is key. After all, no one has time to decipher confusing spreadsheets, right?

    3. Plug in the Numbers

    Now for the fun part—populating your debt schedule! Refer back to all the data you gathered earlier and start entering the details in the appropriate columns. As you do this, double-check for accuracy because minor errors (like an incorrect interest rate) can throw off your financial planning down the line.

    Tip: If this kind of nitty-gritty gives you a headache, consider involving your accountant or bookkeeper, especially for complex debts.

    4. Organize and Prioritize

    Not all debts are created equal. Once you’ve entered all the data, organize it logically—perhaps by due dates, interest rates, or balances. Some businesses prioritize high-interest debts (to save money in the long run), while others focus on tackling smaller ones first for a psychological win. Choose what works best for your strategy!

    5. Schedule Regular Updates

    Your debt schedule isn’t a one-and-done document. It’s a living, breathing tool that needs regular updates to stay relevant. Set aside time, maybe at the end of every month, to review and revise it. Did you pay off a loan? Add a new line of credit? These updates will keep your schedule useful for decision-making.

    6. Use It to Empower Your Financial Planning

    The final step isn’t really a “step” but a mindset: use your debt schedule as more than just a list. It’s a strategic tool! Refer to it when deciding whether to take on new projects, apply for additional loans, or negotiate better terms with your creditors. Remember, knowledge is power, and having your debts spelled out clearly gives you just that.

    mistakes

    Common Mistakes to Avoid When Setting Up Your Debt Schedule

    Creating a business debt schedule is one of the smartest financial habits you can develop to keep your company on solid ground. However, just like any tool, it’s only as good as how well it’s designed and maintained. Unfortunately, there are common slip-ups that can turn your debt schedule from a powerful asset into a muddled mess. Let’s dive into some of the errors you need to watch out for so you can get it right the first time and every time after!

    Avoiding Errors by Staying Consistent

    Consistency might sound boring, but it’s the secret sauce for financial records – especially your debt schedule. One common mistake? Using different formats across the document or updating information irregularly. This inconsistency not only makes your debt schedule harder to read but also increases the chances of missing critical details or inaccurately tracking your debt.

    How to fix it: Choose one format and stick to it. Whether it’s the way you list creditor names, due dates, or balances, consistency is king. Set a regular schedule – monthly works best – to update the information so nothing falls through the cracks.

    Misclassifying or Overlooking Debts

    Another frequent pitfall is leaving out certain debts or improperly classifying them. Ever forget to include a small credit card balance or mislabel a short-term loan as a long-term one? It happens more often than you think. This can lead to a distorted view of your financial obligations and hurt your cash flow planning.

    How to fix it: Double-check that your debt schedule includes all liabilities – loans, credit cards, vendor payables, and even lines of credit that aren’t currently drawn upon. Review categories carefully, labeling debts based on their type (e.g., secured vs. unsecured) and term length.

    Failing to Factor in Interest Rates and Fees

    Sometimes, businesses focus solely on the principal amounts of debts and completely forget interest rates, fees, or penalties. Big mistake! These costs can add up quickly and significantly impact your repayment strategy. Ignoring them can leave you scrambling when payment amounts increase unexpectedly.

    How to fix it: Be sure to include a column in your debt schedule for interest rates, applicable fees, and any other costs associated with each debt. Knowing this information will allow you to prioritize which debts to pay off first – for example, tackling high-interest ones first to save money in the long run.

    Not Accounting for Changes in Payment Schedules

    Here’s one that’s easy to overlook: changes in payment schedules. Maybe you’ve just refinanced, deferred a payment, or renegotiated loan terms. If your debt schedule doesn’t reflect these updates, your financial projections could quickly become inaccurate.

    How to fix it: Keep a log of any changes to debt terms and update your schedule the moment they occur. Transparency and real-time accuracy are key to staying in control of your financial situation.

    Relying on Outdated Tools

    Are you trying to track your debt schedule on a bare-bones spreadsheet from ten years ago? That’s like navigating with a blurry map! Using outdated or overly simplistic tools can hinder your ability to analyze and use the information effectively.

    How to fix it: Invest in modern tools designed specifically for debt tracking. Many accounting platforms have built-in debt management features that can save time and eliminate human error. Look for software that can automatically pull together data and sync it with your records.

    The Bottom Line

    Setting up your debt schedule shouldn’t feel overwhelming. By avoiding these common mistakes and incorporating consistent, thorough, and up-to-date practices, you’ll create a tool that strengthens your financial strategy. Think of your debt schedule as your business’s financial GPS – accurate and precise tracking will help you avoid any financial dead-ends!

    • Tip: Don’t be afraid to review and revise frequently – it’s better to fine-tune as you go than to operate with outdated or faulty information.
    • Action step: Set a recurring calendar reminder to update and review your debt schedule every month. It’ll keep you in the habit of staying on top of your loans and liabilities.

    How a Well-Maintained Debt Schedule Can Support Financial Decisions

    When it comes to managing a business’s financial health, clarity is key. A thoughtfully maintained debt schedule is more than just a list of what your business owes—it’s a powerful tool that can guide your financial decisions with confidence and precision. Let’s dive into how staying on top of your debt schedule can make a massive difference in your financial strategy.

    Understanding the Big Picture

    Your debt schedule acts like a bird’s-eye view of your financial obligations. By keeping a detailed record of loans, interest rates, repayment terms, and due dates, you have a comprehensive snapshot of your liabilities. This level of understanding is invaluable for assessing your business’s current financial standing and planning for the future. Here’s why:

    • Cash Flow Management: Knowing when payments are due helps you allocate resources effectively, ensuring you don’t run into cash crunches when loan payments align with other major expenses.
    • Debt Prioritization: A clear breakdown of interest rates and terms allows you to determine which loans to pay down first, potentially saving significant money in interest over time.

    Informed Decision-Making

    Every financial choice your business makes should be built on reliable information. With a well-maintained debt schedule, you’re equipped to make smarter decisions in areas like:

    1. Future Investments: Want to expand your business or buy new equipment? A debt schedule helps you identify if taking on additional debt is feasible or if it would stretch your finances too thin.
    2. Loan Refinancing: By tracking interest rates and outstanding balances, you can recognize opportunities to refinance existing loans for better terms, ultimately boosting your bottom line.
    3. Strategic Planning: From rolling out long-term growth plans to timing your purchases, having a handle on your debt keeps your goals realistic and informed.

    More Credibility with Stakeholders

    Whether you’re sitting down with investors, lenders, or auditors, presenting an organized debt schedule immediately establishes trust. Why? It shows that you have a firm grasp of your company’s financial responsibilities and emphasizes your commitment to fiscal responsibility. This transparency can make lenders more inclined to offer favorable terms and increase confidence from investors.

    Preparing for the Unexpected

    Life is unpredictable, and so is business. A structured debt schedule prepares you to adapt to unforeseen challenges, such as economic downturns or sudden expenses, by keeping you aware of your leverage and repayment obligations. When crises hit, having a clear map of your debts allows you to react quickly and effectively, preserving your business’s stability.

    Tips for Keeping It in Top Shape

    Of course, the benefits of a debt schedule only materialize if it’s well-maintained. Here’s how you can ensure it remains a trusted financial ally:

    • Update Regularly: Add new debts and adjust balances as payments are made.
    • Leverage Technology: Consider using accounting software or spreadsheets to keep your debt schedule organized and easily accessible.
    • Review Periodically: Set aside time regularly (monthly or quarterly) to review your schedule and refine your repayment strategies.

    Spotlight on Tools: Making Debt Tracking Easier

    Managing your business debt doesn’t have to feel overwhelming! With the right tools at your disposal, keeping your debt schedule accurate and up to date can actually be a straightforward—and dare we say—pleasant task. Let’s take a closer look at some of the powerful tools available that can make debt tracking easier and more efficient for your business.

    Why Use Tools for Debt Tracking?

    Manually managing a debt schedule using basic spreadsheets might work for a while, but as your business grows, so does the complexity of your financial obligations. Missing due dates or forgetting to update balances can lead to unnecessary stress, higher costs, or even a hit to your business credit rating. By leveraging modern tools, not only can you avoid these pitfalls, but you can also save loads of time, enabling you to focus on growing your business.

    Features to Look for in Debt Tracking Tools

    Not all tools are created equal! When choosing a debt tracking solution that works for your business, keep an eye out for the following features:

    • Automation: Tools that sync with your financial accounts can automatically pull in data, reducing manual effort and ensuring up-to-date information.
    • Customizable Reports: Good tools let you generate tailored reports to give you insights into repayment schedules, interest trends, and principal balances.
    • Alerts and Reminders: Never miss a payment or renewal date again. Alerts keep you on track and avoid unnecessary fees.
    • User-Friendly Interface: A clean, easy-to-navigate dashboard ensures you’ll actually use the tool and keep your debt schedule well-maintained.
    • Integration: Tools that integrate seamlessly with your accounting software save you time and effort, giving you a bigger picture of your finances.

    Top Tools to Make Debt Tracking a Breeze

    Ready to explore your options? Here are some popular tools recommended by business finance experts:

    1. Excel or Google Sheets: If you’re just starting out, a spreadsheet software can be a simple and cost-effective solution. Use templates specifically designed for debt schedules, available for download online.
    2. QuickBooks: This widely-used accounting software includes debt management functions, allowing you to track loans, generate reports, and set payment reminders.
    3. Zoho Books: Zoho offers an affordable, feature-packed financial management tool that simplifies debt tracking among its many capabilities.
    4. Trello or Asana (with Customization): While typically project management tools, with a little tweaking, these platforms can be great for task reminders and visualizing debt timelines.
    5. Specialized Financial Tools: Platforms like Tallyfy and Debitize (or similar localized tools) are specifically designed for managing loans and payments seamlessly.

    Making the Right Choice for Your Business

    The key to choosing the best tool is understanding your unique business needs. If you’re a small business with simple loans, a spreadsheet could suffice in the short term. However, if you manage multiple debts with varying interest rates and payment schedules, investing in a more robust software solution will save you time—and likely money—in the long run.

  • What do you need to start a car detailing business

    What do you need to start a car detailing business

    So, you’re thinking about starting a car detailing business—awesome decision! Before diving in, there’s one critical first step: understanding the local market and regulations. Trust me, doing this homework upfront can save you tons of time, money, and headaches later. Let’s unpack it in a way that’s simple and actionable.

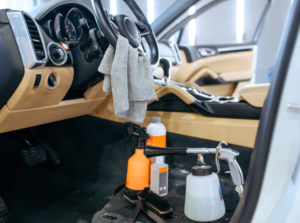
    car cleaning

    1. Start with Market Research

    You need to get your finger on the pulse of the local car detailing demand. Are there a ton of competitors in your area, or is there a gap you can fill? Check out what other car detailing businesses are offering. Look at their pricing, the services they provide, and how busy they seem. One sneaky but effective move? Call a competing service pretending to be a customer and ask about their wait times. Long wait times could mean they’re swamped and there’s plenty of demand for more players in the market.

    Additionally, different communities will have unique needs. For example:

    • Urban areas might favor quick, mobile services since street parking is tighter.
    • Suburban areas may lean towards stationary detailing shops with more room for expanded services.
    • Seasonal businesses thrive in areas with heavy winters where salty roads mean grimy vehicles in need of TLC.

    Ask yourself which services (interior cleaning? ceramic coating? paint restoration?) will appeal most to your local population. If you have access to population data, such as household income and car ownership rates in your area, even better—it’ll give you a solid edge.

    2. Learn About Local Regulations

    Here’s the thing—your business can’t get off the ground without checking the rules in your area. Car detailing might seem straightforward, but there are regulations you need to follow. Let’s break it down:

    1. Business Licensing: Most cities or municipalities will require you to register your business. Check with your local government’s website for details and fees.
    2. Environmental Regulations: Water runoff from car washing can be a big deal in some regions. You might need specific systems in place to ensure dirty water isn’t contaminating local waterways.
    3. Zoning Laws: Certain areas might not allow car detailing businesses. If you’re planning on setting up a stationary location, ensure your property is zoned for commercial use. For mobile setups, check if there are any restrictions on where you can operate.
    4. Permits: You might need special permits to use certain chemicals or set up equipment—even more so if you’re running a mobile service in public spaces.

    If this all sounds overwhelming, don’t worry. Many local governments have small business support centers that can walk you through the process. Hiring a professional to assist with paperwork and ensure compliance can also be worth every penny. You want to start your business on the right foot instead of dealing with fines or closures later.

    3. How to Gauge Demand AND Stay Compliant

    Talk to people—family, friends, neighbors. Ask them if they use detailing services, and if not, what would convince them to start. Collecting firsthand opinions gives you a much clearer picture. Also, go beyond just reading; talk to city planners or get a consultation with a small business advisor to solidify your knowledge of zoning laws and permits.

    Pro Tip: Keep an eye on online platforms like social media and review sites like Yelp to see what customers in your area REALLY complain about or rave about when it comes to car detailing services. Use this research as your secret weapon for structuring your business strategically.

    Choosing the Right Space: Mobile or Stationary Setup

    When starting a car detailing business, one of the biggest decisions you’ll face is whether you want to operate a mobile setup or invest in a stationary location. Each option has its own set of perks and challenges, so it’s essential to weigh them carefully. Don’t worry—we’re here to help you figure out which one suits you best!

    Mobile Car Detailing Setup

    A mobile car detailing setup is an exciting and flexible option, perfect for entrepreneurs who love the idea of taking their services on the road. Here are the key advantages and considerations:

    • Pros:
      • Lower Startup Costs: You don’t need to lease or purchase a physical shop. All you need is a reliable vehicle to transport your equipment.
      • High Convenience for Customers: Being able to detail cars wherever your customers are, at home or their workplace, is a huge selling point.
      • Minimal Overhead: No rent, no big utility bills—just fuel and regular maintenance for your vehicle.
      • Scalable Business Model: Over time, you can expand by adding more mobile units or hiring additional staff with their own equipment.
    • Things to Consider:
      • You’ll need to ensure your vehicle has enough space for all your detailing tools and products.
      • Working outdoors can be unpredictable—rainy days might disrupt your schedule.
      • Access to water and electricity at customer sites isn’t always guaranteed, so you’ll need alternatives like water tanks and portable power supplies.

    Stationary Car Detailing Setup

    Prefer the idea of having a dedicated space? A stationary setup might be the way to go. Here’s what to love—and what to prepare for.

    • Pros:
      • Professional Appearance: A physical shop can help establish a professional brand image and attract foot traffic.
      • Controlled Environment: Weather won’t interfere with your work since you’ll be operating indoors.
      • Opportunity for Larger Services: With more space, you can offer additional services, such as paint correction or ceramic coating application.
    • Things to Consider:
      • Leasing or buying a space means higher initial costs and ongoing monthly expenses.
      • You might need to invest in signage, advertising, and local marketing to make your shop location known.
      • Pick a spot with high visibility and good accessibility for your customers—it’s worth the research!

    Which Option is Right for You?

    Ultimately, whether you choose a mobile or stationary setup depends on your budget, lifestyle, and business goals. If you’re just starting out and want to minimize costs, mobile detailing is a fantastic choice. If you’re aiming to build a long-term, standout business with a steady location, a stationary setup could be your dream business home.

    Whichever route you go, remember that success comes from providing top-notch service and building trust with your customers. The decision on where to work is just the start of your exciting car detailing journey!

    requirements

    Essential Tools and Products to Invest In

    When starting a car detailing business, having the right tools and products in your arsenal can make or break your success. Think of these as your secret weapons for delivering professional results every time. Let’s break down the must-haves, ensuring you’re well-equipped to tackle every customer’s needs, from a quick wash to a full detail. Here’s where to start:

    1. Core Cleaning Tools You Can’t Do Without

    You’ll need proper tools to clean a car effectively inside and out. Here are some of the basics:

    • Pressure Washer: This will help with tough exterior cleaning and ensures you can remove grime thoroughly without wasting tons of water.
    • Vacuum Cleaner: Invest in a high-powered vacuum specifically suited for cars. A vacuum with various attachments can help you reach those tight spots underneath and between seats.
    • Buckets and Grit Guards: Dual buckets—one for soapy water and another for rinsing—keep dirt from transferring back onto the car. Pair them with grit guards to protect paintwork from scratches.
    • Microfiber Towels: Microfiber is your new best friend since it’s scratch-free and super absorbent. Keep a stockpile ready for drying, polishing, and buffing jobs.
    • Dual-Action Polisher: Polishing by hand is time-consuming; a dual-action polisher can save time and deliver a professional-grade finish.

    2. Essential Chemicals and Cleaners

    Using the right cleaning products ensures you won’t damage the vehicle while delivering eye-catching results. These are your staples:

    • Car Wash Soap: Forget generic household soaps! Dedicated car wash soap is designed to be gentle on paint while lifting off the dirt.
    • All-Purpose Cleaner (APC): An APC is versatile and can be used to clean many vehicle interior and exterior surfaces like plastics, fabrics, and carpets.
    • Glass Cleaner: Smudged windows and mirrors are a no-go. A streak-free formula will help achieve crystal-clear results.
    • Wheel and Tire Cleaners: These are specially designed to break down stubborn brake dust and road residue on tires and wheels.
    • Wax and Sealants: Post-cleaning, you’ll want to protect the car’s paint with a durable sealant or go the traditional route with a good carnauba wax for a glossy finish.
    • Car Odor Neutralizers: Leave car interiors not just looking clean but smelling fresh. Invest in odor eliminators or air fresheners that add an extra layer of luxury to your offering.

    car interior

    3. Interior Detailing Must-Haves

    Don’t overlook the interior! Many customers gauge your skills based on how immaculate their car feels on the inside. Here’s the gear to invest in:

    • Detailing Brushes: These range from soft brushes for dashboards to stiffer ones for carpets, great for loosening debris.
    • Steam Cleaner: A steam cleaner not only sanitizes surfaces but also cuts through grease, leaving fabrics like car seats spotless.
    • Upholstery Cleaner: For fabric interiors, you’ll need a cleaner that tackles stains without damaging materials. For leather interiors, get a pH-balanced leather treatment.
    • Extractor/Vacuum Combo: These machines deep-clean carpets and upholstery, sucking up dirt and moisture for a like-new finish.

    4. Storage and Portable Equipment

    Whether you’re running a mobile business or have a physical location, keeping your tools organized is key:

    • Tool Organizers: Use carts or detailing bags to keep everything within reach, saving you time and hassle while working.
    • Water Tanks: For mobile detailers, a portable water tank is a game-changer. Pair it with a generator or battery-powered tools for true mobility.

    5. Don’t Forget Personal Protection

    Detailing can be tough on your body and skin, so prioritize your safety too! Stock up on:

    • Gloves: Protect your hands from chemicals and rough surfaces.
    • Aprons: Keep yourself clean and stay professional with a detailing apron.
    • Protective Eyewear and Masks: Ensure you’re shielded when dealing with strong chemicals, especially during tasks like paint correction or interior sanitization.

    Building a Pricing Strategy That Attracts Customers

    Starting a car detailing business? Great choice! But let’s talk about something that can either drive customers to your door—or drive them away: your pricing strategy. Finding the sweet spot between affordability and profitability is key, and we’re here to help you strike the right balance. Let’s dive in.

    1. Research Your Market (Know the Norm)

    Before you set your prices, you’ve got to know what your competitors are charging. Spend some time investigating other car detailing businesses in your area. Are they charging by the hour? By the package? What’s their pricing range? This research will show you where you fit into the local market and help you avoid overpricing (or seriously underpricing!) your services.

    A quick tip: Check out both mobile and fixed-location businesses since their prices might vary. Mobile services could charge a little more because of the added convenience for customers.

    2. Understand Your Costs

    Your pricing has to account for your costs, or you’ll find yourself in trouble fast. Here’s what to consider:

    • Materials: Cleaning solutions, waxes, brushes, microfiber towels—they all add up!
    • Equipment: Machines like pressure washers and vacuums require maintenance and, eventually, replacement.
    • Labor: If you plan to hire employees later, don’t forget to factor in their wages.
    • Travel (if mobile): Gas and vehicle wear-and-tear should also be reflected in your pricing for mobile setups.

    The goal is to ensure your prices cover all these costs with a healthy profit on top. Track every penny so you can be confident in your price breakdown!

    3. Offer Flexible Packages

    Gone are the days of one-size-fits-all pricing! These days, offering tiered packages can make your services appealing to a broader audience. Consider something like this:

    1. Basic Wash: A simple exterior clean for budget-conscious customers.
    2. Standard Package: Includes interior vacuuming, window cleaning, and a thorough wash.
    3. Premium Detail: Full-service, deep cleaning, waxing, and protective coatings for customers who want the total experience.

    Having options means you can attract budget-conscious customers while still upselling to those willing to pay for premium services.

    4. Highlight Value, Not Just Price

    If you compete on price alone, you’ll always be racing to the bottom. Instead, focus on showing customers the value they’re getting. Emphasize the quality of your work, the professionalism of your service, and the convenience you offer. Does your product last longer? Do you have superior detailing expertise? Let your customers know!

    5. Be Transparent

    No one likes hidden charges. When advertising your prices, make sure they include everything, or at least outline the potential add-ons very clearly. Transparency builds trust, and trust builds long-term customers.

    6. Adapt as You Grow

    Once your business starts gaining momentum, you may need to adjust your pricing. Seasonal demand, growing operational costs, or adding new premium offerings might require a rethink. Don’t be afraid to tweak your strategy if needed, as long as you communicate the changes to your customers in advance.

    Crafting an Eye-Catching Brand and Logo

    Let’s face it: your brand is your personality in the business world. It’s what makes customers remember you (hopefully for all the right reasons!). When you’re starting a car detailing business, crafting an eye-catching brand and logo is not just a box to check—it’s the foundation of how people perceive you. Let’s dive into how to create a brand that not only turns heads but also builds trust and recognition.

    Why Does Branding Matter So Much?

    Your brand is more than just a logo—although we’ll get to why that’s important in a second. It’s your voice, your vibe, and the promise you’re making to potential customers. Strong branding makes you memorable, helps you stand out from competitors, and gives clients a reason to trust you before you’ve even touched their car.

    Think about it: would you rather leave your beloved car with someone who has a sleek, professional brand or someone who looks like they might just be winging it? Your brand communicates professionalism, attention to detail, and the fact that you mean business.

    Steps to Build a Stand-Out Brand

    1. Define Your Niche: Start by identifying your target market. Are you focusing on luxury car owners? Are you targeting busy parents? Your brand should resonate with that audience. For example, a luxury-focused shop might lean into elegance and sophistication, while a family-friendly brand could feel approachable and cheerful.
    2. Choose Your Business Name: Your business name should be unique, easy to remember, and relevant to car detailing. Avoid overly complex or generic names. Something like “Crystal Shine Detailing” or “The Polished Ride” is simple, impactful, and conveys exactly what you do.
    3. Pick Your Brand Colors and Fonts: Your color scheme should align with the emotions you want your brand to evoke. Want to feel sleek and professional? Go for blacks, silvers, and whites. Want something vibrant and friendly? Bold blues or yellows might be the way to go. The fonts matter too—leave Comic Sans in the past and opt for clean, professional typography.
    4. Create a Memorable Logo: This is where the visuals come together. Your logo should be simple, scalable (so it looks good on both business cards and van wraps), and tie in with your colors and themes. If design isn’t your strong suit, consider hiring a graphic designer or using online tools like Canva or Looka to help bring your idea to life.

    Setting Up Online Bookings and Payment Systems

    In today’s fast-paced and tech-savvy world, convenience often makes or breaks a customer’s choice of service. When it comes to your car detailing business, having a smooth, easy-to-use online booking and payment system isn’t just nice to have—it’s essential. Let’s walk through why and how you can make this process effortless for both you and your clients.

    Why Online Bookings Are a Game-Changer

    Think about it: most people are juggling busy schedules and would love the ability to book a service with just a few clicks. By setting up an online booking system, you’re giving your customers the convenience and flexibility they crave. Plus, it can save you time on back-and-forth phone calls or emails. When clients can select their preferred date, time, and service package themselves, you’re left to focus on delivering that perfect shine.

    But here’s the kicker: having an online booking system also adds credibility to your business. It tells customers, “Hey, I’m professional, modern, and ready for business.” First impressions matter, and a great booking interface can set the tone.

    How to Choose the Right Booking Tool

    Don’t worry—you don’t need to be a tech genius to get started. Tons of platforms are designed specifically for small businesses like yours. Some popular options include:

    • Square Appointments: Fantastic for service-based businesses and even integrates with payment processing.
    • Acuity Scheduling: Allows clients to book directly from your website and sends automatic reminders, reducing no-shows.
    • Fresha: Tailored for appointment-based businesses and completely free, though they take a small fee for payments.

    Most of these tools are beginner-friendly and include options like syncing with your calendar, customizing services, and allowing addons for upgrades (think: premium wax jobs or interior deep cleans). Whatever you choose, prioritize platforms that make life easier for both you and your customers.

    Getting Paid Without the Hassle

    Let’s talk payments. You don’t want to chase down unpaid invoices, and trust me—your customers love quick payment options too. Integrating a system that supports digital payments is a must. From good old credit cards to PayPal and even digital wallets like Apple Pay, having a variety of payment options increases your chances of landing a booking (and a happy customer).

    Some top-notch online booking tools also double as payment platforms. For example, Square not only allows bookings but also securely processes payments. If you’re already handling bookings separately, you might explore standalone payment gateways like:

    • Stripe: Great for customizing payment solutions (if you want full control).
    • PayPal: Recognized worldwide and trusted by many users.
    • Venmo: Perfect for casual, small-scale transactions in the U.S.

    Avoid common pitfalls like limiting your customers to cash payments or outdated methods. A smooth, professional checkout process shows you mean business.

    Pro Tips to Seal the Deal

    1. Make It Mobile-Friendly: More than half of online users book and pay on their smartphones. Ensure your system looks and works great on smaller screens.
    2. Allow Modifications: Let clients edit or reschedule their bookings without hassle. Life happens, and flexibility will win customer loyalty.
    3. Use Automated Confirmations: Send an email or SMS confirmation once a booking is made, detailing the time, date, and service selected. This makes things look polished and professional.
    4. Incorporate Upselling: While they’re booking, why not suggest premium services? A pop-up saying, “Add a deep interior clean for $20” could boost your earnings.

    Marketing Tactics That Bring In Customers Fast

    So, you’ve got your car detailing business all set up, and now you’re wondering: How do I get customers in the door—or on my schedule—quickly? This is where smart, effective marketing swoops in to save the day! Not to worry—we’re going to cover ideas that are easy to implement, won’t break the bank, and are proven to get results. Let’s rev those marketing engines!

    1. Get on Social Media and Engage

    Social media is hands-down one of the fastest ways to establish a presence for your car detailing business. Platforms like Facebook, Instagram, and even TikTok are your marketing best friends. Share before-and-after photos of your work, post short videos showing your detailing process (trust me, people love a good transformation!), and interact with followers by replying to comments and messages. Show your genuine personality and passion—it makes your business relatable and trustworthy.

    2. Offer Exclusive Deals for First-Time Customers

    Nothing grabs attention faster than special incentives. Launch an introductory offer like “Get 30% off your first service” or a free add-on like tire cleaning with your first full detail. Promote these deals through social media posts, email campaigns, and even flyers in local hotspots. When people see value right away, they’re more likely to give your service a try!

    3. Use Local SEO to Dominate Online Searches

    Ever notice how people Google things like “car detailing near me”? You want your business to show up first when they do. Setting up and optimizing a Google My Business profile is critical. Be sure to include your business hours, location (if applicable), photos of your work, and glowing customer reviews. Pair that with using local keywords like “Best car detailing in [Your City]” on your website and blog posts, and you’re on your way to topping the search results.

    4. Network with Local Businesses

    Building strong connections in your community can lead to a stream of referrals. Strike up partnerships with businesses like local auto shops, car dealerships, and even valet companies. Offer to detail their cars at a discounted rate or provide them with incentives for referrals. These relationships can turn into a steady source of customers and goodwill. To streamline and track these partnerships, consider using a referral program software to manage incentives and make the process smoother.

    5. Leverage Word-of-Mouth Marketing

    Your happy customers can be some of your best marketing tools! Encourage your clients to spread the word by offering referral discounts: “Refer a friend and get $20 off your next service!” You can make this even more effective by capturing testimonials, asking for reviews on platforms like Yelp or Google, and sharing their positive feedback on your social media pages.

    6. Run Eye-Catching Local Ads

    Sometimes, a small investment in advertising can yield big results. Start with local online ads through Facebook or Google to target people in your area. Focus on engaging text and visuals, like shiny car transformations or happy customer reviews. Offline methods like car magnets or signs at busy intersections can also help you boost visibility around town without being too expensive.

    7. Collaborate with Influencers or Local Creators

    Got a local DIY enthusiast or car enthusiast with a sizable following on Instagram or TikTok? Propose a collaboration! Maybe you detail their car for free in exchange for a post or review about your service. Their stamp of approval can send an influx of followers and bookings your way—win-win!

  • What does a business advisor do

    What does a business advisor do

    When you hear the term “business advisor,” what springs to mind? For many, the first thought is likely someone who deals solely with finances—helping you budget, forecast, and maximize profits. But while financial guidance is indeed a part of their role, a business advisor is much more than just a numbers expert. They’re like the Swiss Army knife of professional guidance, bringing a multidimensional skill set to the table. So, let’s dig deeper into what truly defines a business advisor and why they’re invaluable to business owners at every stage of their journey.

    advisor

    A Compass for Strategy

    Think of a business advisor as your strategic partner. They’re there to help you answer big questions like: “Where is my business headed in the next five years?” or “What is my competitive edge—and how do I sharpen it?” A good advisor will help you shape and refine your vision for your company while also being realistic about the challenges ahead. They balance ambition with practicality, ensuring you’re heading in the right direction without stumbling over roadblocks you didn’t anticipate.

    Not Just an Outsider, But an Insider in Disguise

    What makes a business advisor unique is their ability to blend both insider and outsider perspectives. They’re immersed enough in your company to understand its intricacies but distanced enough to maintain objectivity. This dual perspective allows them to provide insightful recommendations that someone too close to the business might miss. From identifying inefficiencies in your operations to suggesting innovative solutions, they help you see the forest *and* the trees.

    A Sounding Board for Decision-Making

    Every business owner has decisions that weigh heavily on their minds. Should you pivot into a new market? Is it time to grow your team? A business advisor isn’t there to tell you what to do, but rather to provide the guidance, data, and reassurance you need to make these choices confidently. They’ll ask tough questions, provide evidence-based insights, and help you weigh the pros and cons so you can make informed decisions that align with your goals.

    Skill Versatility

    Here’s the kicker: a business advisor often wears many hats. They might work with you to refine your sales strategy, address team morale, or troubleshoot operational snags. One day, they’re helping you untangle a sticky compliance issue; the next, they could be brainstorming creative ways to differentiate your brand. They adapt their expertise to meet the evolving needs of your business, ensuring you always have the support you need, when you need it.

    Always Keeping You Accountable

    Frankly, one of the underrated superpowers of a business advisor is their ability to hold you accountable. As a business owner, it’s easy to become bogged down in day-to-day operations and lose sight of your bigger goals. An advisor helps you stay on track, regularly checking in and nudging you forward. They’re your accountability partner, always steering you toward progress.

    • Big-picture strategists with a knack for details.
    • Objective yet deeply invested in your success.
    • A wellspring of knowledge, experience, and creativity.

    One Step Ahead: How Business Advisors Help with Market Trends

    Let’s face it: in today’s fast-evolving business landscape, staying relevant often means staying ahead of the curve. Markets change, customer preferences shift, and new competitors can emerge seemingly overnight. This is where business advisors step in—not just to help you react, but to proactively position your business for success. So, how do they work their magic? Let’s unpack it!

    Understanding Market Dynamics

    Business advisors are like your business-savvy crystal ball. They spend a significant amount of time analyzing market dynamics, studying trends, and forecasting potential changes. Their work often involves pouring over industry reports, customer data, and current events to pinpoint the patterns that may shape your business environment in the near future.

    Imagine, for instance, you’re in the retail space. A business advisor might notice a surge in eco-conscious consumer behavior long before it hits the mainstream. By identifying this trend early, they can guide you to implement sustainable practices or launch eco-friendly product lines before your competitors catch on. What’s the result? You’re not just playing catch-up—you’re the trendsetter.

    Customized Insight, Not Generic Advice

    One of the key advantages of working with a business advisor is their ability to apply market trends specifically to your business. Yes, trends affect entire industries, but the way they impact your unique company, customers, and goals will look different. A great advisor knows how to tailor their insights to craft a strategy that fits perfectly with your vision.

    Let’s break it down. If you run a tech startup, your advisor might help you tap into trends like artificial intelligence or blockchain, but they’ll guide you to focus on areas that align with your specific capabilities and growth potential, rather than throwing you into something that doesn’t make sense for your company. This blend of knowledge and precision ensures that you’re not just following trends blindly—you’re leveraging them smartly.

    Help Navigating Emerging Technologies

    Speaking of trends, one area many businesses struggle to stay up to date on is technology. From AI to automation, the digital world is moving faster than ever. Business advisors help cut through the noise by identifying meaningful innovations that can boost your efficiency, enhance your customer approach, or create new revenue streams.

    For instance, an advisor might suggest adopting a cutting-edge eCommerce platform based on market data showing increased demand for seamless online experiences. Their guidance ensures you’re not wasting resources on flashy tech that sounds promising but doesn’t suit your business model. Instead, you’ll be positioned to integrate innovations that matter.

    Proactive Planning for the Future

    If there’s one mantra business advisors live by, it’s “preparation over panic.” Instead of waiting for a major shift in the market to affect your business, they aim to have you ready long before it happens. Advisors do this by honing in on long-term trends and helping you develop strategies to future-proof your operations.

    • Have an emerging competitor? They’ll analyze their market entry and suggest sustainable ways to defend your position.
    • Spotting a decline in demand for one of your products? They’ll guide you in repositioning or diversifying your offerings.
    • Noticeable shifts in customer expectations? They’ll help you adjust your approach before it’s too late.

    The Value of Staying One Step Ahead

    Ultimately, the real value of a business advisor lies in their ability to keep you ahead of disruptions. By combining their deep understanding of market trends with actionable strategies, they’ll help you navigate challenges, seize opportunities, and maintain relevance in your industry. In a world where “adapt or die” rings truer than ever, having someone in your corner who constantly keeps an eye on what’s coming next is invaluable.

    So, the next time you hear the term market trends, remember: it’s not about jumping on every bandwagon. It’s about understanding where the value is and taking logical steps toward sustained growth—and with a skilled business advisor, that’s not just possible, it’s inevitable!

    strategy discussion

    Strategic Partner or Problem Solver? Decoding Their True Value

    At its core, a business advisor is often seen as either a strategic partner or a problem solver. But let’s dig a little deeper. It’s not just about slapping a label on their role—it’s about understanding how they adapt to different situations, bring unique perspectives, and ultimately help businesses thrive in ways that go beyond surface-level expectations.

    Being a Strategic Partner

    Think of a strategic partner as someone who’s in it for the long haul. They’re not just called in when things are going south; they’re there to shape the big picture. This approach means working hand-in-hand with business owners or leadership teams to identify goals, create roadmaps, and measure progress over time.

    When acting as a strategic partner, a business advisor focuses on things like:

    • Vision-setting: Helping companies define where they want to go and how to get there.
    • Growth strategies: Identifying opportunities for expansion, whether it’s new markets, customers, or services.
    • Streamlining operations: Advising on internal processes to ensure efficiency and scalability.

    This requires advisors to see far beyond the present and anticipate what challenges or opportunities may be lurking over the horizon. For instance, they might suggest ways to embrace digital transformation or prepare for economic shifts that affect an industry. That’s next-level thinking, don’t you agree?

    Stepping in as a Problem Solver

    On the flip side, business advisors can also be brought on as expert problem solvers, swooping in to fix thorny or immediate issues. The value here is in their ability to cut through the noise and find solutions where others might see only obstacles.

    As problem solvers, business advisors excel in scenarios like:

    • Financial struggles: Designing survival strategies when cash flow runs dry or costs spiral out of control.
    • Product or service issues: Refining underperforming offerings or adjusting pricing models.
    • Leadership clashes: Mediating management conflicts to refocus teams on shared goals.

    In these moments, a data-driven approach is key. Advisors often analyze reports, market insights, and organizational performance to deliver actionable recommendations. But what sets the great ones apart? Their creativity. After all, sometimes a breakthrough solution comes from thinking outside the box.

    From Startups to Established Enterprises: Tailoring Support for Every Stage

    Whether you’re kicking off your business journey as a startup or managing a well-oiled enterprise, one thing is certain: the challenges you face, and the advice you need will evolve. This is where a business advisor truly shines. With the right experience, they adapt their expertise to meet you where you are, helping you tackle immediate goals while preparing for what’s on the horizon. Let’s break it down stage by stage.

    Startups: Turning Ideas into Reality

    For startups, it’s all about building a solid foundation. Business advisors are like the GPS you didn’t know you needed—they guide you through the winding roads of launching a business, avoiding as many potholes as possible. Setting up your legal structure, crafting a functional business plan, and navigating the intimidating world of funding are just the tip of the iceberg.

    When you’re brimming with ideas, it’s easy to get caught up in the excitement, but here’s the deal—success comes from focus. Advisors help prioritize your offerings, assess market fit, and ensure your finances aren’t just a jumble of spreadsheets. With their guidance, you can grow thoughtfully without wasting precious resources.

    Small Businesses: Scaling With Intention

    Congratulations! You’ve moved past the “just launched” phase. But now, the game changes. As a small business owner, it can feel like you’re wearing a thousand hats. From managing a growing team to optimizing operations, things can quickly get overwhelming.

    A business advisor helps you fine-tune your strategies, ensuring scalability doesn’t come at the expense of quality. Need to automate? They’ll point you toward the right tools. Unsure about expanding your product line? They’ll help you weigh the risks and rewards. Advisors also teach you how to delegate effectively—trust us, you don’t have to do it all!

    Established Enterprises: Navigating Complexity

    • Expanding Horizons: At this stage, businesses often look to enter new markets, acquire competitors, or invest in innovation. A business advisor provides invaluable insights to ensure expansion plans are data-driven and realistic.
    • Leadership Challenges: With a larger company comes more complex organizational structures. Advisors act as sounding boards for leadership teams, offering unbiased perspectives on tough decisions like restructuring or pivoting.
    • Staying Ahead: Even established brands can’t rest on their laurels. Advisors monitor industry trends and help companies anticipate disruptions, whether it’s a new competitor or shifting consumer expectations.

    Adapting at Every Crossroad

    The beauty of a skilled business advisor is their ability to adapt their approach based on where your business currently stands. It’s not about delivering cookie-cutter advice—no two companies are the same, and neither are their journeys. Advisors listen, analyze, and craft strategies to ensure you’re always learning, adapting, and thriving.

    Ultimately, at any stage—whether you’re bootstrapping, seeking funding, scaling your team, or cementing your legacy—a business advisor helps you stay focused, prepared, and ready to tackle the ever-changing business landscape. They’re your partner in growth, every step of the way.

    Crisis Control: How Advisors Steady the Ship in Times of Chaos

    Let’s face it—businesses, no matter how well-prepared, are bound to face stormy waters at some point. Whether it’s a sudden economic downturn, a PR nightmare, or supply chain disruptions, chaos has a way of sneaking up on even the most well-organized companies. That’s where an excellent business advisor swoops in—not with magic (if only!), but with expertise, cool-headedness, and a game plan to help navigate through the mess.

    Why Businesses Need an Expert in Crisis Control

    When times get tough, emotions run high. Leadership teams may be scrambling, decisions might be rushed, and panic can cloud judgment. Business advisors play a crucial role by being the calm within the storm. They approach crises with objectivity and an outside perspective that leaders inside an organization may lack at such moments.

    Advisors specialize in zeroing in on what really matters. They’ll help identify the core of the issue—something that’s incredibly important when you’re being bombarded by multiple challenges at once—and create a targeted action plan. Think of it like triage for your business: stabilize the situation first, and then address the root causes.

    The Toolkit of a Crisis-Savvy Business Advisor

    So, what do advisors actually bring to the table during a crisis? It’s not just years of experience (although that certainly helps!). Here’s a peek into their toolkit:

    • Risk Assessment: Before jumping into solutions, advisors evaluate the full scope of the problem. What’s at stake—reputation, finances, operations? Priorities are critical in high-pressure scenarios.
    • Strategic Thinking: Advisors don’t just put out fires—they think several steps ahead. What measures will prevent this from happening again? What opportunities could emerge from the chaos?
    • Financial Safeguards: Many crises hit where it hurts most: the bottom line. Advisors will assess cash flow, renegotiate contracts, and explore funding options to help businesses stay afloat.
    • Clear Communication Plans: Whether dealing with employees, stakeholders, or the public, advisors ensure the right message gets delivered to the right people at the right time. Transparency and trust are key in any crisis.

    Mastering the Art of Resilience

    A great business advisor doesn’t just aim to “solve and leave”; they’re invested in strengthening the business for the future. This means embedding resilience into all aspects of the company’s operations. A crisis becomes a teachable moment, helping business leaders reassess their strategies, adapt to evolving markets, and implement safety nets to weather future storms.

    What’s more, advisors don’t shy away from difficult conversations. Whether it involves restructuring, pivoting business models, or renegotiating partnerships, they focus on what’s best for long-term survival—even if the short-term solutions are tough to swallow.

    Real-World Impact: Making Chaos Manageable

    Picture this: a mid-size company suddenly loses its biggest client, sending its revenue projections into freefall. Leadership is overwhelmed, layoffs seem inevitable, and morale is plummeting. Enter the business advisor. They may quickly step in to reallocate resources, identify alternative revenue streams, and reshuffle team priorities to minimize the impact. What looked like a catastrophe starts to become a manageable challenge, all because there’s someone who knows how to steer the wheel through uncertainty.

    At the end of the day, a business advisor is more than a consultant—they’re the trusted copilot your business needs when navigating through turbulence. So, if chaos ever strikes, take comfort in knowing there are experts who can help steady the ship while you focus on keeping your team motivated and your vision intact.

    Building Bridges: Partnering with Other Professionals for Holistic Solutions

    Let’s face it: no one has all the answers. Business advisors are undoubtedly skilled, resourceful individuals, but their magic truly shines when they work in partnership with other professionals. Why? Because the world of business is multifaceted, and solving complex challenges often takes a team of experts. Let’s dive into how business advisors “build bridges” and collaborate with other pros to craft well-rounded, impactful solutions.

    The Power of Collaboration

    A business advisor is like the conductor of a symphony—they bring together talented individuals with different skill sets to create harmony in an organization. This collaboration can span across various disciplines, including:

    • Accountants and Financial Planners: When it comes to navigating taxes, cash flow, and long-term financial strategies, business advisors often partner with these specialists to make the numbers work in your favor.
    • Legal Experts: From drawing up contracts to ensuring compliance with regulations, business advisors rely on legal professionals to tackle the fine print and protect the company legally.
    • Marketing Consultants: For building a solid brand and staying competitive, advisors work hand-in-hand with marketing experts who understand trends, customer behavior, and digital strategies.
    • HR Specialists: Workforce challenges? Enter HR professionals who help with optimizing team dynamics, recruitment, training, and even employee satisfaction.
    • Technology Gurus: In today’s tech-driven world, IT consultants or tech experts are often onboarded by business advisors to help streamline operations or implement cutting-edge solutions.

    Why Holistic Solutions Work

    The beauty of partnering with other professionals is that it allows for a holistic view of the business. Instead of addressing issues piecemeal, this approach ensures that every aspect of your organization—finance, strategy, HR, operations, and more—is aligned and functioning at its peak.

    Consider this: a business advisor helping a company cut costs might spot inefficiencies in supply chain logistics. They’ll work alongside operational consultants to not only slash expenses but also improve the quality and speed of service. This integrated approach often leads to outcomes that are greater than the sum of their parts.

    When to Lean into a Collaborative Network

    So, when should you expect a business advisor to bring in others? Here are some common scenarios:

    1. Major Transitions: Whether you’re expanding into a new market or pivoting your business model, collaboration with domain experts can ease the process and minimize risks.
    2. Crisis Situations: During turbulent times, like navigating legal battles or financial struggles, a business advisor will call on the appropriate experts to stabilize your business.
    3. Growth Spurts: Scaling up requires more than strategy—it demands financial planning, HR adjustments, and sometimes technological upgrades. That’s a team effort.

    The Human Side: Why Emotional Intelligence Matters in Business Advice

    When you think of a business advisor, what comes to mind? Pivot tables? Market analysis? Strategic game plans? All of that is part of the package, but let’s not forget the essential ingredient for truly impactful advice: emotional intelligence (EQ). In a world of numbers, projections, and balance sheets, the human side is often the secret sauce that transforms good advice into great advice. Let’s dive into why emotional intelligence matters in business advising and how it creates stronger, more meaningful results.

    Understanding Emotional Intelligence in a Business Context

    At its core, emotional intelligence is about understanding, managing, and positively influencing emotions—both your own and those of others. In the business advisor-client relationship, this EQ becomes a superpower. A shrewd, emotionally attuned advisor:

    • Knows how to navigate sensitive conversations gracefully.
    • Builds trust through empathy and active listening.
    • Identifies underlying issues that may not show up on a spreadsheet.
    • Motivates clients to take bold (but necessary) steps forward.

    An advisor with high EQ isn’t just someone who hands you advice; they’re someone who truly gets your unique goals, challenges, and even fears. They look beyond the business metrics to understand the human being driving those metrics.

    The Heart of Good Advice: Listening and Empathy

    Let’s be honest—pouring your energy, savings, and time into a business is deeply personal. Every entrepreneur, CEO, or small business owner has their own dream, priorities, and challenges. A business advisor who approaches their work with empathy acknowledges that this isn’t just about hitting financial benchmarks; it’s about helping people realize their visions.

    The simple act of listening is where it all starts. We’re not talking about waiting for a chance to respond—we’re talking about active listening. This means hearing what clients say, understanding what they mean, and even picking up on what they might not be saying outright. By building that connection, an advisor can forge a relationship built on trust and mutual respect, making their advice infinitely more effective.

    The Problem with Strictly “Business-Like” Approaches

    Let’s face it: not every advisor prioritizes emotional intelligence. Some might focus solely on the data and dismiss the human element as “extra.” But think about it—have you ever seen a stressed-out CEO make their best decision while feeling overwhelmed? Exactly. Ignoring the emotional side of things often leads to miscommunication, resistance, or decisions that lack buy-in.

    Great advisors recognize that running a business isn’t just logical; it’s emotional too. People often need encouragement to push through self-doubt, reassurance during uncertain times, and someone who genuinely believes in their abilities. Numbers alone can’t do that.

    Emotional Intelligence in Action

    Here’s where an emotionally intelligent advisor stands out. Imagine a client who’s struggling with decision fatigue and is hesitant to implement drastic changes. An advisor with strong EQ might:

    1. Encourage open conversations about the client’s concerns and values.
    2. Validate their feelings, reminding them that change is challenging but necessary.
    3. Deliver advice with encouragement, focusing on how these changes align with their overall goals.
    4. Break a daunting transformation into smaller, actionable steps to make it feel more achievable.

    These aren’t one-size-fits-all solutions. They’re tailored approaches that show the advisor values the client as a person, not just as a business opportunity.

    The Ripple Effect of Human-Centered Advice

    When advisors bring emotional intelligence to the table, it creates a ripple effect. Clients often feel more confident, understood, and empowered. This strengthens the partnership between client and advisor, helping decisions gain momentum and results flourish.

    And here’s the kicker: while EQ begins with understanding emotions, its results are practical. A well-supported client is more likely to take decisive action, build stronger teams, and turn challenges into opportunities.

  • What does a business controller do?

    What does a business controller do?

    When you think about a business controller, picture someone who’s both a strategist and a hands-on operator. They live at the intersection of big-picture financial planning and the nuts and bolts of a company’s day-to-day activities. Think of them as navigators charting the best path for a business to sail smoothly towards profitability and sustainability. Sounds exciting, right?

    Here’s the thing: financial strategy usually feels like the big leagues—forecasts, growth projections, and long-term planning. But none of it really matters if it doesn’t translate effectively on the ground. That’s exactly where a business controller shines. Their role revolves around taking high-level ideas and making sure they work where the “real world” happens: in everyday operational processes.

    So, how do they do it?

    Let’s break it down:

    • Top-down alignment: A business controller ensures that operational decisions and actions align with the company’s financial strategy. For instance, if the leadership team decides to cut costs or invest in new projects, it’s the controller’s job to make sure those changes flow seamlessly into operational plans without causing chaos.
    • Creating harmony: They connect teams across departments—finance, operations, and even sales—to avoid silos. Conversation flows better, and this ensures that priorities are executed without confusion or bottlenecks.
    • Simplifying complexities: No one loves diving into spreadsheets more than a business controller! They take that mountain of data and extract actionable insights, translating complex financial terms into something everyone can understand and act on.

    Bridging strategies and day-to-day workflows helps companies avoid that awkward disconnect where leadership is laser-focused on financial forecasts, while operational teams are stuck wondering what they’re supposed to do differently. Transparency and communication are, without doubt, the lifeblood of this role.

    graphics

    Why does this bridge-building matter?

    Without it, organizations risk inefficiency, or worse, losing their competitive edge. Imagine a company with lofty revenue goals but no proper systems in place to achieve them. That’s like setting sail across the ocean without a map or compass! Business controllers keep things steady and ensure that a company’s long-term objectives don’t get lost in everyday hustling.

    Pro Tips for Aspiring Controllers

    1. Sharpen financial forecasting skills: This helps you stay on top of what’s coming and guide daily operations smarter.
    2. Learn the language of operations: Understand how departments like IT, HR, or marketing tick so you can connect the dots.
    3. Be a great communicator: Explaining strategy or financial plans to employees who aren’t finance-savvy is a superpower in this role!

    Role in Budget Creation and Oversight

    When it comes to running a successful business, budgets are more than just numbers on a spreadsheet—they’re the roadmap that guides decision-making, spending, and resource allocation. As a business controller, playing a critical role in budget creation and oversight isn’t just part of the job; it’s the backbone of financial planning. Let’s break it down and explore what this entails!

    The Architect of Budgets

    Think of a budget as the foundation of any financial strategy, and the business controller as its architect. Crafting a budget goes far beyond tallying up income versus expenses. It requires a deep understanding of the company’s goals, market trends, and internal dynamics. A business controller doesn’t just “predict revenue”—they actively engage with stakeholders across various departments to forecast needs, potential risks, and growth opportunities.

    Here’s the deal: creating a budget that actually works and drives revenue means combining historical data, industry knowledge, and future conditions. Controllers must assess past performance, anticipate changes in the market, and collaborate with managers to align financial goals with operational realities. It’s not simply about crunching numbers; it’s about creating an actionable plan that serves the bigger picture.

    Overseeing Execution: A Watchful Eye

    Creating the budget is just half the battle. Ensuring it’s implemented properly—without deviations spiraling into financial chaos—is where oversight comes in. This is where a business controller truly shines. Their role includes monitoring how funds are spent, ensuring teams remain within their limits, and tracking whether financial goals are on course.

    • How do controllers manage oversight? Through diligent tracking of expenditure and understanding spending patterns as they emerge over the fiscal period.
    • They use this information to detect wasteful spending early and suggest adjustments to keep everything on track.
    • Proactive communication is key: controllers engage with management teams to ensure accurate reporting and compliance with set budgets.

    The idea isn’t to be rigid; budgets can be flexible. Sometimes situations change—new opportunities arise, or unexpected challenges crop up—and the budget needs to adapt. Business controllers need to say, “Okay, let’s adjust,” balancing agility with discipline.

    Tools of the Trade

    You may be wondering—how does a business controller keep tabs on all this? Thankfully, they’re not doing it solo with a pencil and paper! Advanced tools, from budgeting software to customized dashboards, provide real-time data. This allows controllers to analyze trends, create what-if scenarios, and instantly identify areas that need fine-tuning.

    Pairing these tools with strong analytical skills ensures that every dollar is accounted for and no red flags go unnoticed. Staying tech-savvy is a must because the ability to manage complex datasets efficiently can make or break financial control.

    Why This Role Matters

    The importance of budgeting and oversight can’t be overstated. Without a well-managed budget, a business can easily overspend or allocate resources where they don’t make sense. A skilled business controller ensures that teams work toward financial success rather than stumbling blindly through guesswork.

    Think of business controllers as guardians of the company’s financial future. With their meticulous planning and monitoring abilities, they enable organizations to stay resilient, stable, and (most importantly) growing.

    Detecting and Mitigating Financial Risks

    In the world of business, financial risks are often like storm clouds on the horizon—clear signs of trouble ahead if left unattended. A business controller plays the role of a vigilant weather forecaster and navigator, ensuring the company not only spots these clouds but also avoids being caught in the storm. Let’s dive into their role in identifying and addressing financial risks, shall we?

    What Are Financial Risks?

    Before we explore how a business controller tackles these challenges, let’s demystify what financial risks are. Simply put, financial risks refer to uncertainties that could negatively affect a company’s financial health. These risks might stem from market changes, credit issues, operational inefficiencies, or even external economic factors that a business can’t directly control.

    Now, no one can eliminate all risks, but the job of a business controller is to make sure risks are minimized and managed effectively. This ensures that the business stays on a steady course toward its goals, even if the financial waters get a little rough.

    Proactive Risk Detection: Seeing the Signs Early

    The secret sauce in a business controller’s toolkit is a proactive approach. Risk detection isn’t about waiting for something to go wrong—it’s about finding weak spots before they turn into major issues. Business controllers often use skills like:

    • Analyzing financial data continuously: By keeping a close eye on cash flow, balance sheets, and profit margins, they can identify red flags early.
    • Tracking economic trends: External influences such as inflation rates or industry shifts can impact the business, so staying informed is critical.
    • Conducting internal audits: These serve as a ‘health check’ for financial systems and processes to spot inefficiencies or vulnerabilities.

    A business controller doesn’t wait for a report to flag an issue. Instead, they take calculated steps to foresee potential problems. For instance, if sales in a key market are declining, they would immediately analyze what’s driving the downturn to avoid cash flow bottlenecks.

    Mitigation: Turning Risks Into Manageable Challenges

    Now that risks are detected, what’s next? Mitigation. This is where the business controller’s skillset really shines. They craft strategies to soften the blow or, better yet, prevent it altogether. Here’s how they often go about it:

    1. Building financial safeguards: Think of these as safety nets, such as maintaining healthy cash reserves or building contingency budgets for surprise expenses.
    2. Collaborating with risk management departments: By joining forces with specialized teams, they ensure a comprehensive response to both internal and external threats.
    3. Fine-tuning financial processes: Identifying process gaps and introducing tighter controls over expenditures or debt management helps reduce exposure to risks.
    4. Scenario planning: This involves creating “what if” models to test how various financial risks, such as a recession or increased vendor costs, might impact the business. Preparedness equals power.

    Staying Agile in a Changing World

    Mistakes might happen, and unforeseen factors like natural disasters or volatile markets are inevitable. This is why agility is paramount. Business controllers embrace change and recalibrate risk strategies as new information arises. For example, if sudden supply chain disruptions occur (hello, pandemic!), they quickly assess financial exposure and immediately suggest pivots to minimize losses.

    A Safety Net for the Business

    In essence, a business controller acts as the financial bodyguard of a company. They’re not just pouring over spreadsheets—they’re securing your organization’s future by taking the guesswork out of risk management. Their ability to detect and mitigate financial risks plays a crucial role in ensuring long-term stability and growth.

    So, the next time you see smooth sailing in your organization despite external challenges, take a moment to thank your business controller. They’re probably behind the scenes, navigating those storm clouds with finesse and keeping your financial future on course!

    control flow

    Streamlining Financial Reporting for Decision-Making

    Let’s talk about one of the most crucial aspects of being a business controller: streamlining financial reporting. At first glance, this might sound like just creating spreadsheets or crunching numbers, but in reality, it’s so much more than that. It’s about weaving together financial data into a story that helps key decision-makers see the big picture, understand risks, and seize opportunities. Let’s dive into what this responsibility entails and why it’s so impactful.

    Why Streamlined Financial Reporting Matters

    Imagine trying to make a big decision—whether it’s expanding to a new market or cutting costs—without clear, accurate financial data. It’s like trying to drive in a dense fog! A business controller’s role is to lift that fog. By simplifying complex financial data and consolidating it into actionable insights, they empower leaders to make informed decisions backed by real numbers.

    Today’s fast-paced business environment demands reports that are not only accurate but also easy to understand and delivered quickly. Being bogged down by clunky reporting processes can mean missed opportunities or delayed actions. That’s where the magic of streamlining comes into play.

    How Business Controllers Make It Happen

    • Centralizing Data Sources: One of the essential first steps is ensuring all financial data flows from consistent, reliable sources. By consolidating data from various departments—sales, operations, and logistics—a business controller eliminates redundancies and resolves inconsistencies. Everyone operates from the same playbook!
    • Creating Standardized Templates: A good report isn’t just accurate; it’s also user-friendly. Business controllers often develop standardized reporting templates that make it easy for leaders to focus on the most relevant metrics, such as profitability, cash flow, or operational expense ratios.
    • Automating Routine Processes: This is a game-changer. Much of the heavy lifting in financial reporting—like gathering and processing raw data—can be automated using software. By implementing automation, business controllers reduce errors and free up time to focus on analysis and recommendations.

    The Art of Telling the Financial Story

    Here’s the thing: data is only as good as the insights you draw from it. Business controllers go beyond presenting numbers—they translate them into compelling narratives. For instance:

    • A dip in monthly sales isn’t just a number—it’s an opportunity to analyze trends and brainstorm strategies with other teams.
    • A sudden spike in expenses isn’t just a cause for concern—it’s a chance to investigate and address inefficiencies before they snowball.

    The ability to blend financial expertise with storytelling is what truly sets business controllers apart. They bridge the gap between raw data and impactful decision-making.

    Practical Tips for Effective Reporting

    For those in the field (or aspiring to be), here’s some practical advice:

    1. Focus on What Matters: Avoid overloading reports with unnecessary details. Highlight key KPIs (key performance indicators) and stick to what the audience needs to know.
    2. Keep It Visual: Charts, graphs, and dashboards make data more digestible. They also help your reports stand out when presenting to non-finance stakeholders.
    3. Always Verify Your Data: Even automated processes need checks. Consistency and accuracy are non-negotiable for credibility.

    In a Nutshell

    Streamlining financial reporting isn’t just a task—it’s a critical service to the business. By transforming complex data into accessible, actionable insights, business controllers ensure that leaders have the tools they need to guide the organization confidently. So, the next time you read a sharp, insightful report, remember the detail-oriented controller behind it who’s helping drive the company to success!

    Analyzing Profitability and Performance Indicators

    When it comes to keeping a business financially healthy, one of the most critical tasks for a business controller is analyzing profitability and performance indicators. In simple terms, this role is all about asking, “Are we making money? And if not, why?” Let’s dive a little deeper into what this involves and how it impacts the success of a company.

    1. Profitability Analysis: Looking Beyond the Numbers

    Every business needs to know which products, services, or business units are pulling their weight and which aren’t. A business controller doesn’t just look at overall profits; they break things down. Which product line generates the highest margins? Are there hidden costs dragging down a seemingly successful operation? These insights are key to understanding how efficiently the company is working.

    For instance, imagine a retail company that offers dozens of products. The controller evaluates things like production costs, pricing strategies, and sales trends to figure out which items deliver the best return on investment. By doing this, businesses can allocate resources more strategically, focusing on what’s working instead of wasting time and money on areas that aren’t performing well.

    2. Performance Indicators: The Pulse of a Business

    Think of performance indicators as the heartbeat of a company. These aren’t just “nice to know” metrics; they’re critical for understanding how well the business is operating. A business controller is responsible for measuring and interpreting these indicators to assess whether the company is on course—or needs to make changes.

    Some key performance indicators (KPIs) a business controller might analyze include:

    • Revenue Growth: Are sales increasing, and if so, at the right pace?
    • Operating Margins: This shows how much profit the business is making from its core operations. Lower margins could call for cost-cutting or efficiency improvements.
    • Customer Acquisition Costs (CAC): Are marketing efforts paying off, or is the company spending too much to attract customers?
    • Return on Investment (ROI): For things like marketing campaigns, expansions, or new projects, ROI indicates whether they’re worth the effort.

    As a business grows, these indicators provide a baseline for setting goals and making comparisons over time. The business controller makes sure these metrics are interpreted correctly, helping managers pivot before small issues grow into costly mistakes.

    3. Making Recommendations Based on Data

    The magic of this process lies in the actionable steps that follow. It’s not enough to simply gather and analyze data—a great business controller uses insights to make informed recommendations. For example:

    1. Proposing price adjustments for underperforming products.
    2. Highlighting areas where operating expenses can be trimmed without harming quality.
    3. Suggesting better allocation of resources, such as focusing on high-margin services.

    The ultimate goal is to maximize profitability without compromising on long-term growth or customer satisfaction. It’s about finding the perfect balance between cutting unnecessary costs and investing in areas that promise returns.

    4. Why This Matters

    This role is vital because it keeps a company grounded in reality. Without proper profitability and performance analysis, it’s all too easy to make assumptions—and assumptions can be costly. A business might expand too aggressively, underestimate risks, or waste resources on ventures that don’t align with its strengths.

    An insightful business controller is like a detective with a calculator—cautiously investigating every corner of the business to pinpoint what’s working and what isn’t. Combining a sharp analytical eye with a deep understanding of the business, they play a vital role in steering the company toward long-term success.

    So, the next time you glance at a thriving business, remember: somewhere behind the scenes, there’s likely a business controller ensuring every dollar works as hard as possible. It’s not just spreadsheets—it’s strategy in action!

    Collaborating with Teams Beyond the Finance Sphere

    If you thought the role of a business controller was confined to spreadsheets and endless numbers, think again! One of the most fascinating aspects of the job is stepping out of the financial cocoon and engaging with a variety of teams across the organization. From marketing to HR, operations to sales, collaboration is at the heart of what makes a business controller truly effective.

    Why Collaboration Matters

    Gone are the days when finance worked in isolation. In modern companies, a business controller’s success often hinges on their ability to connect with departments far beyond the finance sphere. Here’s why:

    • Better Decision-Making: When controllers team up with other departments, they gain a comprehensive view of the company’s operations, which allows for more informed decision-making.
    • Breaking Down Silos: Cross-functional collaborations help build a shared understanding of goals and challenges, ensuring every department is working toward the same objectives.
    • Building Financial Literacy: By working closely with non-finance professionals, controllers can demystify financial data and teach teams how to use this information to improve outcomes.

    Practical Examples of Cross-Team Collaboration

    To really understand the impact of this collaborative role, let’s look at a few examples:

    1. Marketing: Imagine marketing is planning a new campaign. A business controller steps in to analyze the expected cost, determine break-even points, and help forecast the return on investment. Together, they ensure the campaign aligns with the company’s financial goals.
    2. Operations: Operations teams rely on controllers to assess the financial implications of supply chain choices, production costs, or process changes. This ensures seamless coordination between process improvements and their bottom-line impact.
    3. HR: Controllers often work with HR to create realistic budgets for hiring, training, and employee benefits, balancing talent investment with financial stability.

    How to Collaborate Effectively as a Business Controller

    So how can a business controller foster collaboration while managing critical financial responsibilities? Here are a few tips:

    • Communicate Simply: Use accessible language when discussing financial concepts with non-finance departments. Ditch jargon and make data relatable.
    • Be a Proactive Partner: Don’t wait for teams to come to you with questions. Reach out and offer your expertise in their planning and decision-making processes.
    • Understand Their World: Take the time to learn each department’s goals, challenges, and processes. This will help you tailor your insights and showcase your value.

    The Tech Edge: Advanced Tools Business Controllers Use

    Let’s dive into one of the most exciting aspects of being a business controller today: the incredible array of advanced tools that make their work not just manageable, but truly impactful. Gone are the days of mountains of paperwork and manual calculations. Technology has revolutionized how business controllers approach their roles, equipping them with systems and software that deliver precision, speed, and insight. Curious? Let’s explore what’s in their toolkit!

    The Must-Have Software Arsenal

    A business controller is only as good as their tools, so having the right software can be a total game-changer. In today’s tech-savvy world, these are some of the go-to platforms business controllers rely on:

    • ERP Systems (Enterprise Resource Planning): Think of these as the hub of business operations. Platforms like SAP, Oracle, and Microsoft Dynamics centralize financial data, procurement, HR, and supply chain information, giving controllers a bird’s-eye view of processes that affect the bottom line.
    • Business Intelligence (BI) Tools: Want to transform numbers into actionable insights? Tools like Power BI, Tableau, and QlikSense are a controller’s dream. They create stunning visualizations, automatically track KPIs, and make data decisions lightning fast.
    • Forecasting & Budgeting Software: Budgeting isn’t just about plugging numbers into a spreadsheet. Advanced tools like Adaptive Insights or Anaplan let controllers simulate different financial scenarios, calculate forecasts, and adapt budgets in real-time.
    • Accounting Software: While finance teams handle the nitty-gritty, controllers still lean on powerhouse platforms like QuickBooks or NetSuite to oversee compliance and track financial health.

    Automating the Tedious Tasks

    Repetitive tasks can eat up hours of precious time—time that could be better spent on analysis and strategy. Automation tools are a lifesaver here. For instance:

    • Robotic Process Automation (RPA): Yes, this is as cool as it sounds! Controllers can deploy bots using tools like UiPath or Automation Anywhere to handle routine financial processes like data extraction, invoice processing, or reconciliations with incredible efficiency.
    • AI-Driven Insights: Machine learning is becoming an important player in financial analysis. Tools with AI capabilities can flag anomalies in spending, identify potential cost-saving opportunities, and even predict trends based on historical data.

    The Cloud Conundrum

    Cloud-based tools deserve their time in the spotlight, too. Modern business controllers often handle data from various teams across multiple time zones, and on-premise tools simply don’t cut it anymore. With platforms such as Google Workspace, Dropbox, or dedicated cloud financial applications, collaboration has never been easier. Plus, that added layer of flexibility gives controllers the power to access critical reports anytime, anywhere.

    Mastering the Learning Curve

    No conversation about tech would be complete without acknowledging its challenges. Adopting these tools comes with a learning curve, but the payoff is well worth the effort. For any aspiring or experienced controllers out there, consider investing in online workshops, certifications, or webinars. Platforms like Coursera, LinkedIn Learning, or even the tool providers themselves often offer excellent resources. Staying ahead of tech trends isn’t just helpful—it’s essential.

    Why It’s a Game-Changer

    Here’s the key takeaway: technology isn’t just helping business controllers—it’s redefining their role. By leveraging these tools, controllers transition from being number-crunchers to strategic powerhouses. Automation and advanced analysis free up their time for higher-level problem-solving and big-picture thinking, making them indispensable to any organization.

  • What can you do with a business analytics degree

    What can you do with a business analytics degree

    Helping Companies See Patterns Through Numbers

    When you think about business analytics, it’s almost like being a detective—except your clues are numbers, charts, and endless streams of data. Pretty fascinating, right? One of the most important things you can do with a business analytics degree is help companies identify patterns hidden within those numbers. This ability might sound simple, but it’s absolutely game-changing for businesses in nearly every industry.

    Here’s a fun fact: numbers don’t lie. Data, when used correctly, tells stories about what’s working, what’s not, and where opportunities lie. Companies often have truckloads of data at their fingertips, but making sense of it? That’s where you, the skilled business analyst, come in.

    Why Spotting Patterns Matters

    Every business wants to know how they’re performing—whether it’s in terms of sales, costs, growth, or customer satisfaction. But raw data doesn’t automatically tell these stories. It needs to be analyzed, organized, and interpreted before it becomes useful. By deciphering patterns in this data, you can help businesses:

    • Understand performance trends: Is the company hitting its sales targets each quarter? Are there seasonal dips or unexpected spikes?
    • Identify inefficiencies: Is money being wasted somewhere? Are there bottlenecks in the operations?
    • Spot golden opportunities: Are there untapped markets or underperforming areas that could use attention?

    analytics pic

    The Cool Part: Turning Numbers Into Stories

    One of the superpowers you develop with a business analytics degree is the ability to turn seemingly boring rows of data into stories that decision-makers can easily understand. By employing data visualization tools like charts, graphs, and dashboards, you create a visual representation of the information. Suddenly, those dull spreadsheets transform into colorful bar graphs that say, “Look, here’s where things are going right (or not)!”

    For example, let’s imagine a retail company notices a sudden drop in their revenue during the fall. By analyzing sales data across different stores, you discover a key trend: their best-selling product wasn’t popular locally in one region, but there’s booming demand for it in another. That’s actionable intelligence, and you’re the mastermind who revealed it!

    Industries Need This Expertise Everywhere

    Every field you can imagine—from healthcare and finance to retail and tech—is hungry for people who can make sense of their data. Businesses generate mountains of information every day, but unless someone like you can sift through it effectively, they simply won’t get the full value of what they already have.

    Whether you’re working for a fashion brand analyzing online shopping behavior or a hospital tracking patient readmission trends, there’s always a way to make use of patterns. With your degree, you’ll help organizations discover surprises in the numbers and identify promising opportunities for growth.

    Improving Decisions with Better Insights

    Let’s face it: making decisions can be tough, especially in a business environment where so much is at stake. Whether it’s about which product to launch, how to tackle budget constraints, or even how to improve operations, every choice influences the company’s future. This is where the magic of business analytics comes in—specifically, improving decisions with sharper, more informed insights. If you’ve got a business analytics degree (or are planning to get one), this is where your skills make you a real MVP.

    Why Better Insights Are the Backbone of Great Decisions

    In business, guesswork just doesn’t cut it anymore. Thanks to the wealth of data available—from customer feedback to sales figures—there’s no reason for leaders to rely on gut feelings alone. Companies need experts who can turn piles of raw numbers into actionable insights that solve real-world problems. A business analytics degree equips you to do exactly that by teaching you how to:

    • Read and analyze complex data—so you can uncover trends and issues that might not be obvious at first glance.
    • Ask the right questions—because knowing what to look for is just as important as finding it.
    • Communicate findings effectively—ensuring that decision-makers not only understand your insights, but trust and act on them.

    With these tools, you’re not just crunching numbers—you’re providing clarity in what can often feel like chaos.

    How Businesses Benefit

    Imagine being able to identify the optimal time to launch a product based on market trends or selecting the most cost-effective supplier using data-driven comparisons. That’s the kind of value that business analytics professionals bring to the table. Here’s how better insights change the game:

    1. Focus resources where they matter most: Instead of spreading time and money too thin, businesses can invest in areas with the greatest potential for success.
    2. Reduce risks: By analyzing patterns and predicting potential pitfalls, companies can sidestep costly mistakes.
    3. Boost confidence: When decisions are backed by clear, data-based reasoning, leaders feel more assured in their choices—and that confidence trickles down to the entire team.

    What This Means for You as a Business Analyst

    Your role isn’t just about delivering raw data. It’s about becoming a guide—someone who empowers decision-makers with clarity, precision, and confidence. Think of yourself as the person behind the scenes making sure big moves aren’t just guesses but calculated steps forward.

    When you dive into this field, you’ll spend your days refining the decision-making process for a variety of industries. For instance:

    • In healthcare, you could help optimize hospital operations to improve patient care.
    • In retail, you might analyze purchasing patterns to help a company stock shelves with the right products at the right time.
    • In finance, you’d play a role in identifying market opportunities or detecting fraud.

    Predicting Future Trends with Data Tools

    Picture this: You’re at the forefront of a company’s decision-making team, and they’re relying on you to anticipate what’s coming next. Sounds pretty exciting, doesn’t it? Well, that’s exactly what predicting future trends with data tools is all about—and it’s one of the most fascinating ways a degree in Business Analytics can be put to work.

    How Do Data Tools Help You Peek Into the Future?

    At its core, business analytics uses data to help organizations make smart decisions. When it comes to predicting trends, it’s not about crystal balls or lucky guesses—it’s about using cutting-edge tools and techniques to analyze large amounts of past data, identify patterns, and forecast what might happen next.

    For example, machine learning algorithms—a hot topic in the world of analytics—analyze historical trends and provide predictions with remarkable accuracy. Tools such as Power BI, Tableau, and Python-based libraries like Pandas and Scikit-Learn make this process faster and more efficient, which is why many organizations now choose to hire Power BI developers to build clear, reliable forecasting dashboards. A skilled business analyst knows how to leverage these tools to uncover insights that others might miss.

    Why Predictive Analytics is a Game-Changer

    Why does predicting trends matter so much, you ask? Here’s the deal: businesses always want to stay ahead of the competition, and predicting future trends allows them to prepare, innovate, and thrive. These predictions can influence top-level decisions like:

    • Product Launches: Predict demand for a new product to avoid under-producing or overstocking.
    • Market Positioning: Spot trends in consumer behavior, enabling companies to tailor their services.
    • Supply Chain Adjustments: Forecast which suppliers might face delays or how costs might change.
    • Hiring Plans: Anticipate workforce needs to ensure staffing aligns with long-term demand.

    By equipping companies with these forecasts, you’re helping them embrace opportunities and sidestep potential setbacks before they even happen.

    Real-World Examples: Predictions in Action

    Let’s look at how businesses actually use these predictions. In retail, patterns from past sales data can point to seasonal trends. For instance, a clothing brand might notice increased demand for winter wear in late September, prompting earlier production or marketing pushes.

    Another fascinating example? Airlines. Ever noticed how flight ticket prices fluctuate? That’s predictive analytics in action. Analysts in the aviation industry use data tools to predict customer booking patterns and adjust pricing for maximum profitability.

    configrations

    Breaking Down Customer Behavior for Better Services

    Have you ever stopped to think about how companies seem to magically know what customers want? From personalized shopping experiences to perfectly timed offers, it all comes down to understanding customer behavior. This is one area where a business analytics degree really shines! By breaking down how customers think, feel, and act, companies can create services that are tailor-made for their audiences. Let’s dive into how you can use your skills in business analytics to make this magic happen.

    Why Does Understanding Customer Behavior Matter?

    Consumers are at the heart of every successful business. Whether you’re running a cozy café or a global e-commerce giant, knowing what your customers want (and why they want it) is the key to building loyalty and boosting sales. Think about it: if you don’t understand your audience, you’re essentially guessing. And in an era where competition is fierce, guessing doesn’t cut it.

    As a professional with a business analytics degree, you can help companies move past guesswork. Using data-driven insights, you’ll uncover the secret sauce for keeping customers happy—and coming back for more.

    Tools That Help Break Down Customer Behavior

    To decode customer behavior, you’ll rely on powerful tools and techniques. Here are a few game-changers:

    • Customer Segmentation: Using analytics tools, you can sort customers into distinct groups based on factors like age, location, or buying habits. This lets companies target specific audiences with tailored messages. What hooks a teenager might miss the mark for a retiree, right?
    • Buying Journey Mapping: By analyzing how customers move through a business—whether it’s browsing online or shopping in-store—you can identify pain points and areas to improve. For instance, maybe a clunky checkout process is causing cart abandonment. Your insights could save the sale!
    • Churn Prediction: Want to keep loyal customers from switching to competitors? Predictive models help you spot when someone’s about to leave so the company can take action, like offering discounts or personalized recommendations.

    Real-World Examples of Customer Behavior Insights in Action

    The beauty of understanding customer behavior is seeing the real difference it makes in companies. For example:

    1. Subscription Services: Platforms like Netflix and Spotify analyze viewing and listening habits to suggest content customers will love. It’s no accident that the next binge-worthy show is always lined up for you!
    2. Retail Stores: Retailers can track purchases and design loyalty programs that reward frequent shoppers. Discounts, birthday offers, and personalized emails aren’t just nice perks—they’re strategic actions based on analytics.
    3. Travel Agencies: Airlines and hotels use customer behavior data to enhance their services, offering personalized travel experiences or optimizing pricing strategies during peak seasons.

    How Can You Start Making a Difference?

    Your analytical skills are like a superpower—it’s all about learning how to wield them. Start by asking questions about customer interactions: What motivates their choices? What obstacles do they face? Then, dig into the data to uncover patterns and trends. Remember, every recommendation you make is shaping how a company connects with real people.

    So, when you work at the intersection of customer behavior and business analytics, you’re not just crunching numbers—you’re shaping experiences, building relationships, and creating customer loyalty. With your expertise, no customer question will go unanswered—and better services will always be within reach!

    Shaping Marketing Plans with Smart Predictions

    Marketing today is all about reaching the right people at the right time with the right message. Sounds simple, right? Well, that’s where a business analytics degree comes into play! If you love combining creativity with data, shaping marketing plans through smart predictions could be your calling. Let’s chat about how this works.

    The Power of Predictive Analytics

    Imagine this: You’re working with a company that wants to launch a new product. How do they know who will buy it or if there’s even a market for it? That’s where predictive analytics steps in, and trust me, it’s as exciting as it sounds. Using historical data, market trends, and advanced tools like machine learning models, you can forecast customer behavior, market demands, and sales potential. It’s like being a fortune teller, but with numbers!

    Armed with these insights, marketers can tailor campaigns and strategies to resonate with their target audience, saving time and money while achieving better results. Thanks to your skills in business analytics, you’ll be the superhero behind smarter, data-driven marketing decisions.

    Designing Hyper-Targeted Campaigns

    Gone are the days of one-size-fits-all marketing. With the help of analytics, you can help teams identify hyper-specific customer demographics, like age, location, preferences, buying habits, or even the time they’re most likely to open emails! Pretty cool, right?

    Using this information, businesses can create highly targeted campaigns that speak directly to the customer. Personalized ads, email content tailored to specific segments, or “recommended for you” product suggestions are all outcomes of smart predictive marketing. It ensures the company is not just shouting into the void but creating meaningful connections with its audience. That’s where you — with your savvy projections and analytical tools — become invaluable.

    Optimizing ROI Like a Pro

    Ah, return on investment — every marketer’s favorite buzzword. Great marketing isn’t just about looking cool or trendy; it’s about results. How much revenue did the campaign generate? Was the spend worth it?

    Here’s where you come in again! By analyzing past campaigns and forecasting future performance, you can guide marketing teams toward channels and strategies that promise the best ROI. Maybe your analysis shows social media ads drive more conversions than billboards or that customers tend to buy during holiday weekends. Armed with this knowledge, the next campaign’s budget can be allocated wisely, ensuring the business maximizes value.

    Keeping Campaigns Agile

    One big perk of data-driven marketing is the ability to be flexible. Predictive tools let you track campaigns in real-time and quickly adapt if things aren’t performing as expected. Let’s say email open rates are lower than forecasted — you can suggest adjusting subject lines mid-campaign or tweaking the timing of delivery. Your expertise allows marketers to stay ahead of the curve while saving a campaign from veering off course.

    Knowing Risks and Handling Them at Work

    Understanding and managing risks is a huge part of why businesses thrive—or, well, struggle. If you have a business analytics degree, you’re already equipped to help companies tackle risks like a pro. Let’s dive into how this skill can make you a superhero in the workplace.

    The Importance of Risk Management in Business

    When you think about risks, what comes to mind? Financial losses? Cybersecurity threats? Market uncertainties? You’re on the right track! Risks can pop up in many forms, and businesses face them daily. A single mistake or miscalculation can lead to huge consequences. This is where your business analytics degree shines.

    With training in analytics, you can identify potential risks early on. Using data-driven insights, you can anticipate where problems might arise and help your team create strategies to tackle them head-on. Instead of waiting for things to go wrong, you can help stop them from happening in the first place.

    How Business Analytics Helps in Risk Detection

    So, how exactly can you help assess and manage risks? Well, your business analytics degree gives you an edge in:

    • Data Monitoring: Businesses generate massive amounts of data every day. You’ll use tools to comb through all this information and flag unusual patterns or behaviors before they lead to problems.
    • Scenario Planning: Remember learning about predictive modeling? This can help paint different “what if” scenarios for a business. What happens if sales drop by 15%? What if raw material prices skyrocket? You’ll run these models to prepare for the unexpected.
    • Data-Driven Decision Making: Risks are easier to handle when decisions are guided by solid evidence. By bringing forward stats and trends, you ensure that companies don’t take uncalculated risks.

    Handling Risks the Smart Way

    Okay, so you’ve identified the risks. What’s next? Knowing about them is one thing, but steering the ship through turbulent waters takes a whole other set of skills. Luckily, your business analytics degree equips you with plenty of tools for this.

    1. Prioritizing Risks: It’s unlikely that you can eliminate every single risk all at once (#RealTalk!). Instead, your job is to determine which risks are the most pressing and focus efforts there.
    2. Collaborating Across Teams: Risk management isn’t a one-player game. You’ll work with finance, operations, HR, and other departments to create well-rounded strategies to minimize risks across the board.
    3. Building Contingency Plans: Ever heard the saying, “Hope for the best but prepare for the worst”? That’s exactly what contingency planning is all about. You’ll develop plans to keep the business running smoothly if problems arise.

    Why Businesses Love Risk-Savvy Professionals

    Imagine being the person who saves the day when a company faces a tough challenge. That’s exactly the role you can play by managing risks effectively. Businesses value employees who can think several steps ahead, using data as their guide. And being someone who helps avoid losses? That makes you indispensable!

    So, whether you’re identifying gaps in supply chains, analyzing market volatility, or ensuring compliance with regulations, your ability to assess and handle risks sets you out as a powerhouse in the professional landscape.

    Bringing Better Ideas with Team Data Connections

    In the modern workplace, collaboration is the name of the game. And when you pair teamwork with the powerful insights provided by business analytics, the results can be groundbreaking. Let’s dive into how a degree in business analytics equips you to not only work with data but also to synergize with your team and deliver innovative ideas that can transform entire organizations.

    Why Collaboration Matters in Business Analytics

    Gone are the days when data analysis was confined to one person sitting at a desk crunching numbers. Today, it’s all about creating a bridge between analytics and team efforts. As a business analyst, you act as a translator—connecting technical insights with your team’s goals and priorities. This role makes collaboration essential. When you’re able to connect actionable data with the collective expertise of your team, you unlock creative solutions and strategies that wouldn’t be possible otherwise. Standards like ISO 56001 also emphasize this collaborative approach, encouraging organizations to align innovation systems with cross-functional insights and shared responsibilities.

    How Do Teams Excel with Data?

    So, how does combining team collaboration and analytics spark innovation? The process is surprisingly straightforward yet incredibly impactful. Here’s how it unfolds:

    • Sharing a Common Language: A big part of teamwork in analytics is making data accessible to everyone. You don’t have to bog your colleagues down with spreadsheets full of code; instead, you’ll learn to present clear visualizations and concise insights. When everyone understands the “what” and “why” behind the numbers, ideas start flowing.
    • Brainstorming New Possibilities: When people across departments bring their unique perspectives to the table, great things happen. For instance, the marketing team might raise questions about customer needs that your data can answer, leading to campaigns that resonate more deeply with your audience.
    • Encouraging Cross-Functional Problem-Solving: By merging your findings with team feedback, you create an environment where the best solutions rise to the top. Whether it’s optimizing supply chains or adjusting product strategies, collaboration ensures no stone is left unturned.

    Making the Most of Team Data Connections

    Of course, fostering strong data connections within your team requires more than just enthusiastic meetings and presentations. Here’s how you can lead the way as a business analytics professional:

    1. Use Tools to Foster Collaboration: Platforms like Tableau or Power BI not only analyze data but also make it shareable and interactive. Everyone, from marketing to HR, can contribute to live dashboards that encourage ongoing discussions.
    2. Be the Data Advocate in the Room: It’s easy for non-analytics folks to feel overwhelmed by numbers. By showing how valuable and user-friendly data can be, you help your team see analytics as a tool for better ideas rather than just a specialized skill set.
    3. Promote Open Communication: Strong collaboration starts with a supportive culture. Make it easy for everyone to ask questions about the data—and answer them in plain language. This openness builds trust and encourages brainstorming sessions that lead to real progress.
  • Best Businesses to Start with 20K: Profitable Ideas.

    Best Businesses to Start with 20K: Profitable Ideas.

    Starting a business with 20,000 opens up a world of possibilities, from online ventures to brick-and-mortar opportunities. Whether you’re looking for a side hustle or a full-time business, choosing the right path is key to maximizing your investment. In this guide, we’ll explore profitable business ideas that fit within a 20K budget, covering industries like e-commerce, service-based businesses, and local startups. If you’re ready to turn your capital into a thriving venture, let’s dive into the best options to get started!

    Small-Scale Custom Printing Business: More Than Just T-Shirts

    So, you’re wondering how to stretch that 20K into a lucrative business? Well, let’s talk about custom printing! It’s a versatile and creative way to build not just a company, but also a fun venture that resonates with your personality. Sure, people might immediately think of T-shirt printing, but there’s so much more room to play here!

    Why Start a Custom Printing Business?

    Custom printing is one of the few businesses where a relatively small investment can yield incredible returns. Here’s why:

    • Low Entry Costs: With $20K, you can easily purchase a high-quality direct-to-garment (DTG) or screen-printing machine, a heat press, and other essential supplies like ink and blank items to get started.
    • High Demand: Custom items aren’t just trendy—they’re personal. From unique corporate merchandise to personalized gifts for weddings, birthdays, and events, people are always looking for items that make a statement.

    Beyond Just T-Shirts

    Think outside the “basic-printing” box. These days, almost anything can be printed on! Here are some unique niches to consider:

    1. Canvas Tote Bags: With a growing awareness of sustainable and reusable products, custom tote bags are an eco-friendly hit.
    2. Mugs & Drinkware: Personalized mugs add flair to kitchens and perfect gifts for customers.
    3. Phone Cases: Everyone uses smartphones, making stylish or quirky custom cases very appealing, especially for younger crowds.
    4. Home Decor: Think decorative throw pillows, wall art, or customizable blankets. These items stand out and have a high-profit margin.
    5. Specialty Apparel: Move beyond basic T-shirts and tap into markets like custom hoodies, baby onesies, or even sports team merch.

    What You’ll Need to Get Started

    Now, let’s get a little into planning. Setting up your small-scale custom printing business will require a mix of equipment, creativity, and strategy:

    • Printing Technology: Choose between screen printing (great for bulk orders) and DTG printing (ideal for small, detail-heavy jobs).
    • Designing Software: Invest in tools like Adobe Illustrator or Canva Pro to create appealing designs—or hire a freelance graphic designer if you’re not tech-savvy.
    • Inventory: Start small with basic items—plain T-shirts, mugs, and totes are beginner-friendly and versatile.
    • Marketing Strategy: Use social media platforms like Instagram, TikTok, and Pinterest to showcase your products. Invest in a user-friendly ecommerce site to streamline sales.

    Tips for Success

    Starting strong is one thing, but staying relevant is another. Here are some tips to help you succeed long-term:

    1. Find Your Niche: Are you targeting a specific group, like dog owners or fitness enthusiasts? Cater your products to their interests.
    2. Offer Customization Options: Allow customers to submit their own designs to make your service feel tailored to them.
    3. Local Partnerships: Local Partnerships: Team up with local businesses for bulk orders—think cafes needing branded tote bags or alternative schools wanting custom apparel.
    4. Focus on Quality: Always prioritize quality over quantity. Happy customers spread the word faster than any ad campaign.

    With a bit of equipment, ingenuity, and hard work, your small-scale custom printing business could turn your $20K investment into a thriving, scalable brand in no time. Who knows? One day, you could be the go-to name for custom prints in your area—or even beyond. Let your creativity shine!

    Home-Based Food Services: Mixing Passion with Profit

    Starting a food-related business from the comfort of your home can be a fantastic way to combine your love for cooking with some entrepreneurial spirit. With a budget of $20K, you have the opportunity to create a thriving small-scale food service operation that caters to your local community or even serves a broader audience online. Let’s dive into how you can turn your culinary skills into a profitable venture!

    Why a Home-Based Food Service Business?

    Food is a universal necessity, and people are always looking for convenient, delicious, and unique options — especially if they come with a personal touch. Home-based food services cater to individuals who seek a homemade, wholesome meal experience or specialty items they can’t easily find in grocery stores. With lower overhead costs compared to renting a restaurant space, you can keep your expenses under control while delivering high-quality products.

    Ideas to Consider

    You can focus on a specific niche to stand out in the food industry. Here are some ideas:

    • Baked Goods: Freshly baked bread, unique pastries, or custom cakes for events can be a big hit.
    • Catering for Small Gatherings: Offer your services for intimate events like birthdays, corporate lunches, or even office parties.
    • Meal Prep Services: Pre-packaged, healthy, and ready-to-eat meals are perfect for busy professionals or fitness enthusiasts.
    • Specialty Foods: Think about making jams, sauces, pickles, or even ethnic delicacies that are hard to find in stores.
    • Breakfast or Snack Boxes: Curated boxes with an assortment of treats or healthy morning options could tap into trendy consumer demands.

    Key Steps to Get Started

    Jumping into the food business requires some thoughtful planning. Follow this roadmap to start your home-based food services:

    1. Market Research: Study your local community and identify the demand. Are people craving healthier food, nostalgic home recipes, or something completely unique? Understanding your audience is everything.
    2. Licensing and Permits: Ensure that you comply with local health and food safety regulations. This might include getting a food handler’s permit or adhering to cottage food laws in your area.
    3. Perfect Your Menu: Start small with a focused menu. Offer only a handful of dishes or items that you’ve perfected, then expand once you’ve tested the waters. You can also use tools like The QR Code Generator (TQRCG) to add scannable codes to your packaging or flyers, making it easy for customers to access menus, place orders, or follow you on social media.
    4. Quality Packaging: Invest in eco-friendly and attractive packaging to give your products a professional touch. First impressions matter more than you think! To make your packaging truly stand out, be sure to create your custom boxes that reflect your brand’s personality and enhance the customer experience
    5. Set Up Marketing Channels: Use social media platforms like Instagram and Facebook to showcase your creations. A visually appealing page with customer testimonials can help build trust and attract orders.

    Tips for Long-Term Success

    The food services industry thrives on repeat customers and word-of-mouth referrals. Here are some practical tips to sustain and grow your business:

    • Consistency is Key: Always maintain the same high quality, taste, and service to keep your customers coming back.
    • Get Feedback: Encourage your customers to give honest reviews to identify areas where you can improve.
    • Experiment: Once your core products are established, test new flavors or limited-time offerings to keep things fresh and exciting.
    • Leverage Community Events: Partner with local businesses, attend farmers’ markets, or participate in food festivals to expand your customer base.

    Profitable Ventures in the Online Resale Market

    Are you ready to dive into the exciting world of online reselling? With $20,000 in your pocket, you have a fantastic opportunity to make your mark in the resale industry, which is booming more than ever. The beauty of this business is its accessibility—anyone with a bit of entrepreneurial spirit, a knack for finding hidden gems, and some online know-how can succeed in this space. Let’s explore how you can turn this idea into a profitable venture.

    Why the Resale Market is Thriving

    The online resale market is growing rapidly, thanks to increased consumer interest in sustainability, affordability, and unique finds. People love scoring great deals on gently used or rare items, and resale platforms like eBay, Poshmark, and Facebook Marketplace make it easier than ever to connect sellers with buyers. Plus, with trends like thrift flipping and secondhand shopping gaining momentum, starting an online resale business is not just profitable—it’s trendy.

    Steps to Start Your Resale Business

    1. Pick Your Niche: The first step is deciding what kind of products you’ll sell. Will it be vintage clothing, electronics, furniture, or maybe rare collectibles? A clear niche helps you stand out in a competitive market.
    2. Source Your Inventory: Find quality inventory to flip. Consider options like thrift stores, clearance sections in retail stores, estate sales, or even wholesale suppliers. Creating relationships with bulk distributors could give you the edge to secure great deals.
    3. Create Your Online Presence: Choose platforms that align with your niche. For instance, fashion items perform well on Poshmark, while electronics may do better on eBay. Build polished, eye-catching product listings to attract buyers and establish credibility.
    4. Consider Logistics: Shipping and inventory management are key aspects to figure out early. Invest in reliable shipping materials and explore platforms that simplify the shipping process by offering discounts or integrated label printing.

    What Makes This a Great Use of $20K

    With $20,000, you have capital to get a strong start. Here’s how you could allocate some of that budget:

    • Inventory: Spend a significant portion (around 50-60%) on high-quality items or bulk inventory.
    • Technology: Invest in reselling tools like inventory management software, shipping label printers, and photography equipment to present your listings professionally.
    • Marketing: Marketing: Allocate 10–15% of your budget to online advertising campaigns to drive traffic to your listings or store. Social media ads can be highly effective, just ensure your content is shared at the best times to post on social media to capture more attention from your target buyers.
    • Emergency Fund: Keep some money set aside as a safety net for unforeseen expenses or to seize great inventory deals when they pop up.

    Tips for Long-Term Success

    The resale business is not only scalable but also allows you to showcase your creativity and entrepreneurial skills. Want to succeed even more? Here are a few pro tips to keep in mind:

    • Stay updated on trends and buyer preferences to source items that are always in demand.
    • Continuously improve your photos and listings to increase conversions.
    • Engage with your buyers and ask for reviews to build a solid reputation.
    • Be willing to adapt. Market trends shift, and staying flexible will keep your business thriving.

    Exploring Tech Services: Affordable Startup Ideas

    Starting a tech-related business with a budget of $20,000 might sound daunting at first, especially when we hear about billion-dollar tech giants dominating the market. But here’s the thing: you don’t need a Silicon Valley-sized budget to tap into this thriving sector. In fact, there are several affordable tech service ideas you can explore, even with limited resources. Let’s break it down and see how you can turn your technical skills (or hire those who have them) into a lucrative business opportunity.

    Why Tech Services? The Low-Cost Advantage

    The beauty of tech services is that many of them don’t require heavy upfront investments in inventory, manufacturing, or commercial space. Tech-based businesses often rely more on skills and software rather than raw materials and gigantic facilities. This is especially true for offerings like Virtual CTO Services, where businesses can access high-level technical leadership without the cost of hiring a full-time executive or building out a physical infrastructure. Your biggest investments might be a good computer, some specialized software or apps, and compelling marketing. Plus, almost every type of business today needs tech support in some form—so you’ll have no shortage of potential customers.

    Affordable Startup Ideas in Tech Services

    Here are some approachable and budget-friendly tech service ideas to consider:

    • Website and App Development: If you have web development skills, you’re in luck. With platforms like WordPress, Wix, or Shopify, you can create stunning websites for small businesses and entrepreneurs. Hiring a small team of developers could also allow you to tackle app development, a growing area in today’s mobile-first world.
    • Social Media Management for Local Businesses: Many small businesses struggle to manage their Facebook, Instagram, or LinkedIn pages. With basic familiarity with social media tools, you can curate content, schedule posts, interact with followers, and build brand awareness for local entrepreneurs.
    • Tech Support Services: Even in 2023, not everyone is tech-savvy. By offering affordable tech support—from setting up devices to troubleshooting software issues—you can address a universal pain point. You can even specialize in helping seniors or small business owners who lack IT departments.
    • Cybersecurity Services: With cybersecurity threats on the rise, even small businesses need help ensuring their data is safe. You don’t need to start with the most complex solutions—simple firewalls, basic training sessions, or offering malware protection services can go a long way.
    • SEO and Digital Marketing Consulting: Every business wants to rank higher on search engines. By learning (or hiring talent proficient in) search engine optimization (SEO), you can help businesses improve their online visibility without needing large capital investments.

    How to Make It Work on a $20K Budget

    Now that you have a list of ideas, how do you actually execute them on a small budget? Here are some tips:

    1. Invest in training and certifications if needed: Platforms like Coursera, Udemy, or Google Skillshop offer budget-friendly courses to enhance your skills.
    2. Use freelancers or contractors: This way, you won’t need to hire a full-time team. Sites like Upwork or Fiverr can connect you with talent for specific tasks.
    3. Keep your overhead low. Run the business from your home or a co-working space rather than renting a physical office.
    4. Leverage free or affordable tools. For example, use Canva for design, Hootsuite for social media management, or Asana for project management.
    5. Focus on customer relationships to generate referrals. If you deliver outstanding service, happy clients will do some of your marketing for you.

    Turning Crafts or Art Into a Revenue Stream

    Are you one of those creative souls who loves to craft, paint, or design? Good news: your $20K budget could help you turn that passion into a thriving business! Whether you sculpt pottery, knit stylish scarves, or create stunning wall art, there are so many possibilities to transform your talents into a profitable venture that also brings you joy.

    Start with Your Specialty

    The first step toward launching your craft-based business is understanding your niche. What’s your area of expertise? Are your handmade candles so famous among friends that they’re practically begging to buy them? Is your watercolor art so striking that it turns heads? Choosing a specialty ensures that you stand out in a crowded market. If you haven’t quite settled on your focus, spend some time experimenting to see what inspires you the most—and what resonates with others.

    Create a Product Line

    Once you’ve decided what craft or art you’d like to sell, think about how to make your offerings cohesive and attractive. For example:

    • If you’re into candle-making, offer seasonal scents, like pumpkin spice for fall or lavender for spring.
    • If you’re a painter, create a themed collection, such as landscapes or minimalist botanicals.
    • If you sew or knit, consider offering accessories that complement one another, like a matching set of hats and scarves.

    Having a clear and curated product line makes it easier to market your items to customers and encourages repeat purchases.

    Invest in Quality Supplies

    With a $20K budget, you have some room to purchase high-quality materials while still keeping costs manageable. Buyers are more likely to recommend your work—and pay top dollar—when it’s clear that you put thought and effort into every item. Don’t cut corners when it comes to crafting tools or the raw materials you’ll need to bring your visions to life.

    Use Technology to Your Advantage

    You don’t need to rent a physical space or rely on in-person sales to succeed. Thanks to technology, setting up shop has never been easier or more affordable. Use some of your budget to:

    1. Launch an online store: Platforms like Printify, Printful, Etsy, Shopify, or Big Cartel are great for selling handcrafted items, artistic pieces, and custom hoodies. They’re easy to use and connect you with a global market of shoppers who love unique treasures.
    2. Invest in good photography: High-quality photos are essential for selling your work online. If you can’t hire a professional, invest in a decent smartphone camera, lighting setup, and some basic photo editing tools. You can also enhance your images using an HD photo converter to ensure your visuals are crisp and clear for potential buyers.
    3. Promote through social media: Sites like Instagram and Pinterest are visual platforms that are ideal for showcasing crafts and art. Regularly post about your process and finished products to engage your audience. If you’re creating content in bulk or need help making your posts sound more human and engaging, tools like Walter Writes AI can assist in crafting polished, relatable captions and descriptions.

    Collaborate and Sell Locally

    Although the online world can take your crafts far and wide, don’t underestimate the power of selling locally as well. Try pairing up with local boutiques, art fairs, or craft markets. It’s a great way to connect with your community while getting your work in front of more eyes. Plus, it can present opportunities for partnerships and custom orders.

    Local Services That Solve Everyday Problems

    Sometimes, the best businesses are the ones that address simple, everyday problems. If you have around $20,000 to invest, launching a local service that improves convenience for people in your community can be a rewarding and profitable venture. Let’s explore some creative ideas and practical steps to turn this concept into a thriving business.

    Why Local Services Are a Winning Idea

    Think about your own day-to-day life. How often do you wish someone else could take care of the errands or chores piling up? That’s exactly where local service businesses shine. From convenience to problem-solving, they directly cater to basic needs, creating a steady demand. What’s even better is these types of ventures require minimal upfront investment in inventory or physical space, making them ideal for a modest $20k budget.

    Ideas for Everyday Problem-Solving Services

    Start by identifying common challenges your community faces. Here are a few service-based business ideas to get your creative juices flowing:

    • Mobile Car Wash and Detailing: Not everyone has the time to clean their vehicle, but everyone wants it to look sharp. With a few essential tools and eco-friendly cleaning supplies, you can start bringing cleanliness to people’s driveways for a fee.
    • Personal Errands Service: Think grocery shopping, parcel delivery, picking up prescriptions—small yet time-consuming tasks people would happily outsource.
    • Pet Sitting and Dog Walking: Pet owners often struggle to find reliable care for their furry friends. Offering flexible and trustworthy services can make you a go-to solution in your neighborhood.
    • Handyman or Landscaping Services: Many homeowners need help fixing appliances or sprucing up their yards but don’t know whom to call. Even if you’re not a pro, you can hire skilled labor to take on basic repair or maintenance jobs. To streamline operations, many independent workers and small teams are now turning to handyman business software to manage bookings, track tasks, and improve service delivery.

    Steps to Start Your Local Service Business

    Ready to turn that $20k into a steady stream of income? Here’s a step-by-step guide to make it happen:

    1. Research Local Demand: Talk to people in your community or post informal surveys online to understand the services they’re most likely to use. Identifying gaps is crucial for finding your niche.
    2. Create a Lean Business Plan: Since you’re working with a manageable budget, focus on the essentials. Factor in the cost of equipment, licensing, marketing, and ongoing expenses like fuel or supplies.
    3. Prioritize Simple Marketing Strategies: Tools like Google My Business and social media platforms like Facebook are perfect for connecting with local customers. Additionally, flyers on community bulletin boards or partnerships with local businesses can boost visibility.
    4. Focus on Customer Service: A friendly, professional attitude goes a long way in creating repeat customers. Aim to exceed their expectations from day one.

    Leverage Technology to Stand Out

    One way to outshine your competition is by streamlining your operations with simple tech tools. For example, consider setting up online booking and payment options for your services. Tools like scheduling apps or mobile payment systems (like Square) make the whole experience seamless for you and your clients.

    Niche Ecommerce Stores with a Purposeful Focus

    Starting a niche ecommerce store with $20,000 is a fantastic way to break into the entrepreneurial world without tackling overly saturated markets. Niche ecommerce focuses on catering to a specific audience with specialized products—and with the right strategy, you can carve out a loyal customer base while ensuring your offerings stand out in a sea of generic goods.

    Let’s dive into what makes this business model special, how you can use your budget wisely, and some actionable steps to get started.

    Why Niche Ecommerce Stores Work

    Niche stores thrive because they serve a specific, often underserved, audience. Unlike generic online shops that sell a bit of everything, a niche store positions itself as an expert in one category. Imagine selling only yoga socks, eco-friendly pet toys, or premium stationery for bullet journaling enthusiasts—your target customer knows exactly why they’re coming to you.

    Customers today crave connection. A niche ecommerce store with a clear purpose can create a sense of relatability, community, and trust. This focus sets you apart, builds brand loyalty, and reduces competition compared to larger-scale general online retailers. For a niche store, engaging in WooCommerce website development is crucial for staying competitive in the digital space.

    Smart Uses of Your $20,000

    Here’s how you can strategically allocate your startup capital to build a thriving niche ecommerce store:

    • Website Development: Around $2,000–$5,000 can establish a professional yet straightforward website using platforms like Shopify or WooCommerce. These solutions are user-friendly, scalable, and perfect for managing niche online stores. For businesses needing more advanced customization and scalability, Magento 2 development services offer a powerful alternative.
    • Inventory or Dropshipping: Invest $5,000–$8,000 into initial stock or dropshipping partnerships. If shipping physical inventory isn’t feasible, dropshipping allows you to sell unique, curated products with minimal upfront costs.
    • Brand Development: Allocate $2,000–$3,000 for logo creation, professional photography, and cohesive branding. With a niche market, your brand identity must resonate with your audience’s passions or lifestyle.
    • Marketing and Advertising: Set aside $5,000–$8,000 for paid ads, influencer partnerships, and content creation. Use platforms like Google or Facebook Ads to laser-target your audience based on their specific interests.
    • Operational Costs: Always reserve some funds (e.g., $2,000) for unexpected costs, customer service tools, or platform fees.

    Choosing the Perfect Niche

    Research is everything when it comes to building a successful online store, especially when planning your Magento e-commerce strategies. Look for underserved demographics, trending products, or passionate communities with specific needs. Tools like Google Trends, Pinterest, and ecommerce analytics reports can help you pinpoint opportunities. Here are a few successful niche ideas:

    1. Sustainable Living: Eco-friendly reusable items, upcycled fashion, or plastic-free kitchen products.
    2. Pet Care: Unique handmade pet accessories or furniture for pets, like fancy cat trees or personalized dog collars.
    3. Hobbies and Interests: Products tailored for niche hobbies like knitting, home brewing, or urban gardening.
    4. Health and Wellness: Specialized fitness equipment, natural skincare, or wellness planners for mental health.
  • What questions to ask when buying a Business

    What questions to ask when buying a Business

    How Healthy Are the Financials Beyond the Numbers?

    Buying a business is a big decision, and financial performance is one of the first things you’ll check out. However, it’s critical to realize that there’s more to financial health than what’s reflected in spreadsheets and profit margins. Let’s dive into what you should be thinking about when inspecting the financials of a prospective business.


    Understanding the Bigger Picture

    Sure, revenue and cash flow are key indicators of success, but don’t stop there! Look at how consistent these figures are over time. Has the business been growing steadily, or are there big fluctuations? Stability in the numbers often indicates a well-run operation, while variability might suggest underlying challenges.

    Avoid Financial “Smoke and Mirrors”

    One essential tip: always ask for detailed financial records going back at least three years. This might include income statements, balance sheets, tax returns, and cash flow statements. Be on the lookout for potential “red flags” such as sudden spikes or unexplained profitability dips. If something doesn’t add up, ask why—and don’t hesitate to involve an accountant to analyze the books professionally before proceeding.

    Dig Into the Revenue Sources

    Here’s a piece of advice many forget: assess how diversified the revenue streams are. Does the business depend heavily on one or two customers for most of its income? If so, that could be risky. A well-distributed revenue base is a better bet—it reduces dependency on any single source and indicates diverse income potential.

    Don’t Overlook the Costs

    What can sometimes make or break an acquisition is understanding the cost structure of the business. Pay close attention to operational expenses. Are there contracts or agreements locking the business into high overhead costs? From supplier agreements to lease terms, these monetary commitments can have long-term implications for your bottom line.

    Cash Flow Is King

    Ever heard the phrase “cash is king”? This saying holds true, especially when analyzing a business’s financial health. A profitable business doesn’t always mean it has healthy cash flow. Be sure you’re aware of how money is moving in and out. Is there a seasonal dependency where cash flow dips during specific months? Can the business sustain itself during lean periods, or is it vulnerable to liquidity crises?

    • Pro Tip: If the previous owner has been overly dependent on debt to maintain cash flow, you’ll need a strategy to address these obligations post-purchase.
    Consider “Soft” Financial Influences

    Here’s where things get interesting. Financial health isn’t just about raw numbers—it’s about what’s driving them. For example, is the business reliant on an aging product or service that might soon be outdated? Does the local market play a huge role in revenue, and is it changing? Thinking beyond the numbers can save you from surprises down the road.

    Engage Experts

    Finally, don’t hesitate to work with financial consultants or accountants. They specialize in uncovering financial risks that may not be obvious at first glance. Even better, they can help identify opportunities for financial optimization, making your future business venture even stronger.

    In the end, ensuring financial health isn’t just about checking off boxes—it’s about gaining a full and clear understanding of the business as it stands and where it’s heading. Trust your instincts, rely on trusted professionals, and don’t be afraid to ask tough questions. A little diligence up front can save you big headaches (and dollars!) down the road.

    What’s the Real Story Behind Customer Loyalty and Retention?

    When buying a business, financials are critical, no doubt—but understanding why the customers keep coming back is just as important. It’s the lifeblood of any successful company. So, how do you uncover the truth about customer loyalty? Here’s what you need to explore, step by step.

    1. Dive into Customer Profiles

    Start by asking: Who are the customers? Get a clear picture of the customer base. Are they a mix of new customers and repeat buyers, or are most of them one-time visitors? Understanding their demographics, purchasing patterns, and preferences will help you determine if their loyalty is sustainable—or if it’s just a fluke.

    • Request data on the percentage of repeat customers versus new buyers.
    • Check customer acquisition costs. High costs with little repeat business could signal trouble.
    • Uncover whether the business serves broader market segments or a niche audience. Niche markets can be loyal, but risky if trends change.
    2. Measure the Customer Retention Rate

    Customer retention is a strong indicator of business health. Ask the seller for metrics that illustrate how many customers come back after their first purchase.

    Pro tip: Retention rates above 60% in many industries are considered healthy. Anything significantly lower could require a deeper understanding of why customers aren’t sticking around.

    Also, inquire about trends. Has retention improved, declined, or stayed flat? A declining rate might reflect service issues, new competition, or failing to adapt to customer needs.

    3. Investigate Reasons for Loyalty

    Next, dig into the heart of what keeps customers coming back—or what scares them away. Is it the product or service quality? The pricing model? Perhaps the business has a charismatic owner or unique brand story. This insight is crucial because:

    • Brand loyalty tied to the current owner’s personality may not transfer easily to you!
    • If loyalty is purely price-driven, you might face eroding margins in the future.
    • A standout product or experience is a more sustainable reason for dedication.

    Request customer surveys, reviews, or testimonials to learn their reasons for staying engaged (or churning).

    4. Examine Customer Feedback Channels

    How does the business handle feedback? A company with a solid system to monitor, respond to, and act on customer concerns is more likely to foster loyalty long-term.

    Ask if they track Net Promoter Scores (NPS) or similar metrics that measure customer satisfaction. Look for patterns in complaints and resolutions in recent feedback. Are they quick to resolve issues, or do valid concerns go ignored?

    5. Assess Churn and Loyalty Risks

    Finally, take a hard look at potential risks. Are competitors luring customers away with better solutions? Maybe the business depends on a small group of high-value customers—what happens if one or two of them leave?

    Questions to ask include:

    • What’s the churn rate (percentage of customers who stop doing business with the company)?
    • How diverse is the revenue? Are they overly reliant on a few big accounts?
    • Is the business vulnerable to market trends or shifts in consumer preferences?

    How Strong Is the Competitive Moat in the Market?

    When you’re considering buying a business, one of the key areas to dive into is how well the company is protected against competition. This is often described as the “competitive moat.” A moat, just like the one surrounding a medieval castle, acts as a barrier that keeps rivals from taking over territory—or in this case, stealing market share. Knowing the strength and width of a business’s moat can help you predict how sustainable its success will be in the face of competition.

    Why Does a Competitive Moat Matter?

    A strong competitive moat ensures the business has something unique or defensible that competitors can’t easily replicate. This could be due to a superior product, brand recognition, exclusive supplier relationships, intellectual property, or even economies of scale. Without a moat, a business is much more vulnerable to competitors swooping in and chipping away profits. And nobody wants to invest in a sinking ship, right?

    Questions to Ask and Areas to Examine
    • What distinguishes this business from its competitors? Take time to understand the company’s unique value proposition. Is it offering something competitors can’t match? Whether it’s through innovative products, better customer service, or quicker delivery, differentiation is critical.
    • How strong is the brand in the market? A recognized and respected brand can be a powerful moat. Explore the business’s reputation among customers—this may require reviewing customer testimonials, online reviews, and even a look at social media presence.
    • What’s the threat level of new entrants? Consider how easy it would be for new competitors to enter the market. For example, are there high barriers to entry such as significant capital investment or regulatory requirements? Lower barriers mean higher risks of competition.
    • Does the business have proprietary assets? Look for things like patents, trademarks, or technological advantages. Proprietary assets aren’t just nice-to-haves—they can be game-changers in keeping competition at bay.

    Real-Life Red Flags

    While investigating the competitive moat, you might find signs of weaknesses that could be potential red flags. For instance, if the market is oversaturated with a lot of similar businesses offering the same product or service, it’s a sign the business might not have a sustainable edge. Weak customer loyalty or dissatisfaction may also suggest cracks in the moat.

    Another issue can arise when the “moat” only exists because of temporary external factors, like a lack of awareness among competitors or a trend that might die out. Always consider whether the advantages are sustainable long-term or just a flash in the pan.

    What Should You Look for Moving Forward?

    It’s crucial to understand whether the competitive moat is adaptable. Markets evolve, and competition gets tougher—ask yourself if the business is in a position to innovate and stay ahead in the game. A flexible, forward-thinking approach to maintaining a strong and defensible position speaks volumes about long-term survivability.

    As you weigh your decision, remember: a business with a strong and enduring competitive moat can provide you with stability and profitability for years to come. Be sure to carefully analyze both current strengths and potential threats so you can make an informed choice about the future of the business.

    What Are the Hidden Operational Challenges Lurking?

    Buying a business often feels like stepping into someone else’s carefully built machine. Everything might look shiny and functional on the surface, but operating a business successfully is about understanding what’s beneath the hood. Hidden operational challenges can make or break your ability to run the company smoothly post-purchase. So how do you uncover these lurking issues? Let me walk you through it.

    Take a Close Look at Processes and Systems

    Every business has processes, but are they streamlined or patchwork fixes cobbled together over years? Ask the seller detailed questions about the systems in place for everything from inventory management to customer support. Are their tools and software outdated, or worse, does the business still rely on cumbersome manual processes where automation could save time and money?

    Uncovering inefficiencies here can help you assess how much effort and cost might be required to bring the business up to speed. For instance, transitioning to modern customer relationship management (CRM) software, tracking tools, or accounting platforms can be costly and disruptive if ignored early on.

    Staffing and Roles: Are There Gaps or Redundancies?

    The people behind the operation are just as important as the business itself. A hidden challenge that’s often overlooked in a sale involves staffing logistics. Investigate whether the current team is well-utilized or if there are overlapping duties leading to inefficiencies.
    Additionally, take time to understand whether there are gaps in the workforce that could leave you scrambling after the purchase. Are specialized skills concentrated in one or two key employees? What happens if they leave?

    Dive deeper by asking for an up-to-date organizational structure chart. You’d be surprised how often it becomes the missing piece in understanding the real operational dynamics. This step ensures you’re not walking into a resource headache.

    Supply Chain Stability: Will It Hold Up?

    Does the business you’re buying depend on a few major suppliers? If so, there’s a potential red flag. A common but hidden operational issue is overdependence on a single supplier or vendor. What happens if that supplier increases their prices, goes out of business, or can’t meet demand?

    Study contracts closely and ask for historical records regarding supplier relationships. Diversification is key. If the business is overly dependent on one link in the chain, you might face serious challenges maintaining operations down the line.

    Scalability and Future Constraints

    A slick website might catch your eye, but can the back-end support growth? A hidden issue many buyers ignore is that some businesses are optimized only for their current size. Once demand spikes, cracks start to show. Inquire about storage capacities, delivery systems, and production bottlenecks that may not surface until you try to expand.

    If long-term scalability isn’t baked into the operations, you’ll find yourself bogged down by costly and time-consuming upgrades sooner than expected.

    How to Stay Ahead?
    • Ask for case studies: Have them showcase what happened during an extraordinary season or rapid growth period. This unveils whether the business handled pressure gracefully or stumbled.
    • Perform diligence on infrastructure: Look at physical assets like machinery, tools, or IT hardware. Worn-out or neglected equipment can turn into a ticking time bomb.
    • Consult an operational expert: If you’re not well-versed in systems and efficiencies, hire someone to take a deep dive. Sometimes a professional can glimpse red flags you’d miss as a first-time buyer.

    Ultimately, peeling back the layers of a business’s operations means asking the right questions and looking beyond the surface. Operational challenges can be dealt with, but the real measure of a successful acquisition is knowing what you’re walking into—and having a plan to handle the hurdles ahead.

    Have You Dug Deep Into Employee Satisfaction and Institutional Knowledge?

    When you’re buying a business, it’s easy to focus on the obvious metrics—revenue, profit margins, and growth trends. But here’s a pro tip: don’t skip the human side of the equation. Employee satisfaction and institutional knowledge can be two of the most critical, yet overlooked, ingredients in a successful acquisition. Let’s break it down into why this matters and how you can address it.

    Why You Should Care About Employee Satisfaction

    Happy employees are the beating heart of any thriving business. If a team feels undervalued, unmotivated, or uncertain about the future, it could spell trouble for you as the incoming owner. Dissatisfied employees may lack productivity, deliver subpar customer service, or even jump ship entirely once you take over.

    When employees are motivated and loyal, they’ll bring synergy to the workplace, provide valuable insights for improving processes, and often stay committed throughout the transition period. In essence, if a business’s workforce is a well-oiled machine, you’ll have a smoother ride as the new captain of the ship.

    • Practical Tip: During the due diligence phase, get access to employee satisfaction surveys (if available) or consider conducting your own discreet assessments. If surveys aren’t an option, pay attention to resignation rates or schedules of employee reviews to gauge overall morale.
    • Red Flag to Watch For: High turnover or longstanding unresolved conflicts could be signs of deeper cultural issues within the organization.
    The Goldmine of Institutional Knowledge

    Institutional knowledge refers to the collective wisdom, skills, and processes that reside within your team. It may not show up on a balance sheet, but trust us—it can significantly impact how the business runs. Imagine losing a key employee on day one, only to realize they were the only one who knew how to operate critical systems, maintain long-standing client relationships, or navigate unique industry challenges.

    Understanding where institutional knowledge resides and how well it’s documented separates the strategic buyers from the reactive ones. If this knowledge is siloed in particular team members’ heads, you risk disruptions when those individuals leave. However, if it’s been effectively shared or documented, you’re looking at a much safer bet.

    • Practical Tip: Ask for clear documentation of operational workflows, client histories, and procedures. Is there a documented onboarding process for new employees? How are key tasks delegated? Weak documentation is your cue to take extra precautions.
    • Pro Move: Meet with key team members to get a sense of whether they are willing and able to share their knowledge post-acquisition. This may involve implementing mentorship or training programs during the transition period.
    How to Approach These Conversations

    We know—asking these questions might feel delicate. After all, no one wants to walk into a meeting and immediately give employees the perception that layoffs or drastic management shifts are on the way. So, how you approach these discussions matters.

    1. Work with the Seller: Ask the current owner to help facilitate conversations with key employees where you can build rapport and gather insights directly.
    2. Be Transparent: Share your vision for the transition. Honest dialogue about your goals will help keep employees on your side.
    3. Use Third-Party Assessments: Sometimes it’s easier to let HR consultants or professional advisors handle employee satisfaction surveys or interviews. This helps maintain objectivity while gathering crucial data.

    Are There Legal or Contractual Risks Waiting in the Background?

    When you’re in the exciting phase of exploring a business purchase, it’s easy to get swept up by visions of future success. But hold on—before you dive headfirst, you need to peel back the layers and take a hard look at what’s officially binding. Why? Because legal and contractual risks can quietly lurk beneath the surface, potentially creating a nightmare down the road.

    Why Legal Risks Matter

    Let’s face it: no one wants to inherit a surprise lawsuit as a “welcome to your new business” gift. Legal risks can crop up from unresolved disputes with vendors, lawsuits from past employees, or even issues tied to intellectual property. Imagine buying a brand that turns out to have trademark infringement issues—talk about a headache!

    Make sure you ask for all the legal paperwork. Specifically, insist on reviewing pending litigation, contractual obligations, and any regulatory documents. Having a qualified attorney comb through contracts and files is non-negotiable here. They’ll spot issues you may not even know could exist—and trust me, this is one area where professional advice counts.

    The Devil Is in the Contract Details

    Aside from legal perils, there are contractual pitfalls to consider. Every business has agreements with suppliers, vendors, partners, and sometimes even customers. For you, as the potential buyer, these contracts can be a double-edged sword. On the positive side, they may ensure a steady supply chain or locked-in revenues. On the downside, they may tie you into unfavorable terms that restrict future growth or come with steep penalties for breaking.

    Ask yourself: Are there any perpetual agreements? This could mean contracts that seem minor but could hold you hostage for years. You’ll also want to understand if customers make deal-breaking demands, such as refunds or service credits, nestled in long-forgotten agreements. These details will directly impact the financial feasibility of your purchase.

    Look Closer at Industry-Specific Risks
    • Regulatory Compliance: In industries like food, healthcare, or finance, regulatory compliance can define day-to-day operations. Previous lapses or violations inherited by purchase may cost you time and money.
    • Licensing Issues: Does the business require special licenses, permits, or certifications to operate? Make sure they’re valid and transferable.
    • Non-Disclosure Agreements (NDAs): When buying a business, agreements protecting trade secrets or intellectual property need to remain intact—they’re often critical assets.
    What Should You Do Next?
    1. Hire an experienced business attorney to perform legal due diligence. Do not attempt to do this alone.
    2. Discuss scenarios and risks with the seller. Be direct and transparent!
    3. Request a list of all contracts, including any expiring soon, to fully assess the obligations you’ll inherit.

    At the end of the day, digging into legal and contractual risks protects your investment. It’s not glamorous work, but being exhaustive here allows you to walk away—or proceed—with intention and safeguards in place. After all, purchasing a business should bring opportunities, not inadvertent liabilities!

    What’s the Seller’s Role and the Reasons Behind Letting Go?

    When buying a business, one of the most important—and often overlooked—questions you should ask is: why is the seller letting go? This isn’t just about satisfying your curiosity; it’s a critical step in understanding what you’re getting into. Think of it like peeling back the layers of an onion—each layer reveals valuable insights that might shape your decision.

    The Seller’s Role: Key to a Smooth Transition

    Start by digging into the seller’s role within the business. Were they the backbone of day-to-day operations, wearing multiple hats, or were they more hands-off? This matters because the level of their involvement could directly impact how the business continues to perform under your ownership.

    • High involvement: If the seller is deeply embedded, from managing key customer relationships to overseeing operations, their departure could create a disruptive void. You’ll need to ask yourself: Can I take over their role, or will I need to hire someone to fill those shoes?
    • Low involvement: On the flip side, if the business runs smoothly with minimal seller input, that’s a good sign of strong systems and teams in place. But don’t stop there—ensure that these processes are well-documented, so you’re not left guessing once you take over.
    What’s Driving the Decision to Sell?

    Once you have clarity on their role, dive into the reasons behind their decision to sell. Sellers often cite reasons like retirement, pursuing new ventures, or personal circumstances. While those may sound legitimate, it’s essential to look beyond surface-level justifications to ensure there’s no underlying issue being masked.

    Helpful Questions to Ask:
    • Are there market pressures or industry shifts causing a decline in profitability?
    • Is there something about the business model that’s no longer sustainable?
    • Are there unresolved internal conflicts, such as disputes with partners or staff?

    By probing tactfully, you can uncover whether the seller’s motives should give you pause or simply provide context that reinforces their genuine reasons for stepping away.

    The Transition Plan: Setting Yourself Up for Success

    Understanding the seller’s current role also allows you to create a clearer picture of the transition process. Will the seller be available to help guide you after the handover? If so, for how long? Are they open to providing training for you and the staff, introducing you to key customers, or sharing best practices?

    A transition period can be your secret weapon to mitigate risks. Sellers who are willing to stay on temporarily or act as consultants once the deal is done demonstrate confidence in the business’s long-term prospects and often make the shift smoother.

    Red Flags to Watch For

    Be cautious if the seller seems overly eager to close the deal quickly without a compelling explanation. Another red flag might be reluctance to share details about their role or the business’s challenges. Genuine sellers understand the importance of transparency and will likely work to help you feel comfortable with the purchase.

  • What are my rights if my employer sells the business

    What are my rights if my employer sells the business

    So, your employer is selling the business, and you’re wondering what this means for you. First of all, take a deep breath – this kind of situation can feel uncertain, but knowledge is power, and you’re in the right place to figure it all out! Let’s break it down step by step.

     When a business is sold, employees are often a central part of what’s being handed over to the buyer. It’s not just the physical assets like buildings or inventory that are sold, but also the people who make the business run – that means you! Depending on the type of sale and the laws in your region, your employment could remain intact under the new ownership, or you might encounter some changes. Let’s explore what could happen and what to look out for.

    Scenario A: The New Employer Takes Over Your Employment.

    In many cases, especially if you’re in a location where labor protections like the Transfer of Undertakings (Protection of Employment), or TUPE, laws apply (as in the UK and some other jurisdictions), employees are transferred to the new employer automatically. This means your job continues largely as it was before, with minimal interruptions. Sounds reassuring, right?

    However, laws may vary depending on where you are. In the U.S., for example, this process can be trickier because employment is often considered “at-will.” Always consider consulting a local expert or your HR team to get the specifics for your region.

    Scenario B: Restructuring or Redundancy

    On the flip side, some business sales involve restructuring. Your new employer might decide to shuffle things around, which could mean changes in job roles, locations, or even possible redundancies. Sounds a bit daunting, but don’t panic just yet! In many regions, employers must give proper notice and, in cases of redundancy, provide adequate compensation or alternative role options. Keep an eye out for legal notifications like redundancy consultations if this situation arises.

    Scenario C: Negotiating New Employment Terms

    Some business sales might not automatically transfer your job. In these cases, the new employer might want to renegotiate employment terms or even start from scratch with new contracts. This doesn’t mean you’re powerless, though! Feel free to ask questions, negotiate your terms, and ensure you fully understand what’s being offered before signing anything. Never feel rushed; you’re entitled to review documents or seek advice if needed.

    Understanding Your Rights Moving Forward

    • Make sure you’re included in any relevant communications about the sale from your employer – transparency is key.
    • Review employment laws for your region to understand how they protect you in this situation.
    • If applicable, look for formal documents explaining how your employment will transfer or whether changes will occur (this might be called a TUPE notice or similar).

    At the end of the day, the fate of your employment depends on the details of the sale and the legal framework in your area. Don’t hesitate to reach out to a labor lawyer or trusted advisor for tailored advice if anything seems unclear. Having someone in your corner who knows the ropes can make all the difference in navigating this transition smoothly.

    Are My Employment Terms Automatically Transferred?

    When your employer decides to sell the business, it’s natural to wonder what might happen to your employment terms and conditions. After all, your job forms an important part of your daily life and financial security. Don’t worry—let’s dive into this topic and shed some light on how these situations are typically handled!

    What Does “Automatically Transferred” Mean?

    In many cases, when a business changes hands, your employment terms do automatically transfer to the new employer. This generally means that your salary, working hours, holiday entitlements, and other conditions remain the same as they were under your previous employer. It’s like carrying over a contract blueprint—your rights and obligations are preserved even with new management.

    This process is often governed by laws or regulations, such as the Transfer of Undertakings Protection of Employment) Regulations (commonly known as TUPE) in the UK or equivalent legislation in other countries. The idea behind these rules is simple: to keep employees protected during major business changes.

    Are There Exceptions to the Rule?

    While the principle of automatic transfer usually applies, there are exceptions depending on the nature of the business sale and local labor laws. For example:

    • If the business is going through insolvency or liquidation, the rules around automatic transfer might differ significantly.
    • If the purchaser is only acquiring specific assets of the business and not taking on its employees, then automatic transfer may not apply.

    In such cases, your employment rights might not move with the sale, and you could face redundancy (though this opens the door to compensation, which would fall under other considerations).

    How Does TUPE Work?

    Legislation like TUPE (if applicable in your region) mandates that your employment terms—essentially, your existing contract—transfer over to the new employer unchanged. Importantly, this includes everything from your core responsibilities to benefits like sick leave or maternity policies, ensuring that you are treated fairly amidst the business shuffle. Sounds reassuring, right?

    However, it’s crucial to note that this only applies if your role is considered part of the business being sold. If your role is peripheral or tied to a different division, the same guarantees might not apply.

    Key Takeaways for You

    So, what should you do if you find yourself in this situation? First, get informed. Request clear communication from your employer about the effect of the sale on your position—this is your right. Second, knowing your legal protections is crucial. Familiarize yourself with the laws governing business transfers in your country, and don’t hesitate to seek professional guidance if the finer details leave you feeling unsure.

    Remember, the process may feel unsettling, but the law is often on your side. Your employment terms are designed to come with you if the business changes hands, ensuring a smoother transition and maintaining your job security. If anything feels off or unclear, it’s always a good idea to seek advice—after all, your rights matter, and it’s important to safeguard them during moments of workplace change.

    Can My New Employer Change My Job Role or Contract?

    One of the big questions when your employer sells the business is whether your new employer has the right to change your job role or contract. It’s natural to feel uncertain about this, but don’t worry! Understanding your rights is the first step to protecting them.

    Know Your Protection Under Employment Law

    In many jurisdictions, laws protect employees during business sales, ensuring you’re not left vulnerable. For example, in places like the UK and EU, regulations such as TUPE (Transfer of Undertakings Protection of Employment) apply. Essentially, these laws mean that your existing employment terms and conditions transfer over to the new employer unchanged. This includes your salary, working hours, holiday entitlement, and even your length of service.

    In other countries, similar laws exist that limit what a new employer can immediately change when taking over a business. Do some research specific to your location, or seek advice from an employment lawyer if you’re unsure.

    When Can a New Employer Make Changes?

    That said, there are circumstances where a new employer may attempt to adjust your role or contract. Here’s what you need to know about when those changes can happen:

    • Business Needs: If the new employer can show that changes are necessary for business efficiency, they may propose contract alterations. For example, they might suggest a new reporting structure or ask for flexibility in your job duties.
    • Mutual Agreement: Employers cannot force changes on you. If they want to change terms like your job title, salary, or hours, they must consult you and get your consent. Always review any proposed changes carefully before agreeing.
    • Redundancy or Restructuring: In some cases, changes may occur as part of a wider restructuring plan, especially if the new employer sees redundancy as unavoidable.

    How to Handle Proposed Changes

    If your new employer proposes changes to your role or contract, it’s important to stay calm and informed. Here’s how to approach the situation:

    1. Ask Questions: Don’t hesitate to get clarity on why changes are being suggested. Transparency is key, and understanding their perspective can help you respond thoughtfully.
    2. Review Your Contract: Go through the terms in detail. Consult your original contract and any documentation confirming the transfer of your employment. Are the changes fair or reasonable?
    3. Consider Seeking Advice: If you feel unsure about your position, reach out to a labor union (if applicable) or a legal professional who specializes in employment law. They can help you navigate your rights.
    4. Negotiate: If changes are unavoidable, consider negotiating adjustments that work for both you and your employer, such as additional benefits, training opportunities, or compensation.

    What If Changes Are Made Without Your Approval?

    If your new employer alters your terms without consulting or obtaining your agreement, you may have legal protections. You could file a grievance, pursue mediation, or even lodge a claim for breach of contract, depending on your situation and local employment laws. Remember, employers are obligated to treat you fairly, and you have every right to stand up for yourself!

    Do I Have a Say in the Sale Process?

    When you hear that your employer is selling the business, it’s natural to wonder if you have any control over what happens next. The short answer? It depends on the situation, but as an employee, there are some aspects of the process where your rights should be respected. Let’s break this down together!

    1. Legal Rights to Consultation

    In most cases, employers are required by law to inform and consult with employees before a sale, especially when the sale involves a transfer of the business to another company (often referred to as a “transfer of undertaking”). This obligation varies depending on where you live and local labor laws, but typically, employers need to:

    • Notify employees about the proposed sale or transfer in advance.
    • Explain how the sale might affect their jobs, roles, or terms of employment.
    • Discuss any potential redundancies, restructuring plans, or other significant changes.

    Generally, this consultation should happen with employee representatives, such as trade unions or elected workplace representatives. If your company has a union or a recognized employee body, they may act as your voice during the process.

    2. Do You Have Decision-Making Power?

    Unfortunately, employees don’t usually have formal decision-making authority in whether a business is sold or who it’s sold to. The sale itself is typically a decision made by the business owner or shareholders. However, just because you can’t stop the sale doesn’t mean you’re powerless!

    For example, under certain frameworks like Transfer of Undertakings (Protection of Employment) Regulations (TUPE) in the UK, employees have legal protections during the sale process. While you might not be able to veto the sale, these protections often provide peace of mind by ensuring your existing rights are somewhat safeguarded after the transfer.

    3. What About Direct Input?

    In some companies, especially smaller businesses, management may engage directly with employees during the sale process to answer questions or ease concerns. If your employer is open to dialogue, don’t hesitate to ask important questions, such as:

    • Who is buying the business?
    • Will my role or team structure be affected?
    • What changes, if any, should I expect?

    Even if they aren’t legally required to involve employees in decision-making, transparency from employers is considered good practice. After all, employees are a vital part of any business, and many employers want to support a smooth transition.

    4. What You Can Do

    While you can’t usually stop a sale, you can take proactive steps to protect yourself and make the most of the situation. Here’s how:

    1. Stay informed: Keep a close eye on company announcements and any information shared in consultations.
    2. Ask questions: Don’t shy away from clarifying how the sale might impact your future employment.
    3. Engage representatives: If you’re part of a union or have employee representatives, ensure they understand your concerns and priorities.
    4. Know your rights: Research labor laws in your country regarding business transfers and employee protections.

    In some cases, you may also choose to seek legal advice if the information provided by your employer seems vague, or if you feel your rights aren’t being honored during the process. It’s always better to be prepared than caught off guard.

    How Does a Sale Affect Workplace Benefits and Pensions?

    When your employer decides to sell the business, it’s natural to have questions, especially about your workplace benefits and pensions. After all, these are key parts of your livelihood, and you’ve worked hard to earn them! So, what happens when a sale is on the table? Let’s break it down step by step, so you know what to expect and what you’re entitled to during this transition.

    1. Will My Benefits Stay the Same?

    One of the most important things to check is whether your benefits—like health insurance, paid time off, bonuses, or other perks—remain untouched after the sale. Typically, if a business is sold as a “going concern” (meaning the new employer takes over operations without a major break), your benefits likely should carry over. However, the new employer might review and potentially adjust benefit packages to align with their policies.

    Here’s what you can do to protect yourself:

    • Review your contract: Take the time to revisit your employment agreement. Benefits that are explicitly outlined may be harder to alter without consultation.
    • Ask clear questions: During the transition, don’t hesitate to ask your new employer for details about how your benefits might change—or even if they won’t change at all. Transparency is key!

    2. What About My Pension?

    When it comes to pensions, things can feel even more personal—and understandably so. Pension plans are often bound by specific legal protections, and the way they’re handled in a business sale depends on whether the plan is a defined benefit, defined contribution, or workplace scheme.

    In many cases:

    • Defined benefit plans: Employers are usually obligated to safeguard your pension and ensure that any promises made about payouts are upheld (sometimes through transferring to a new plan or honoring existing contributions).
    • Defined contribution plans: These might get transferred to the new company’s contribution scheme, but your accrued funds shouldn’t vanish—they remain yours!
    • State or statutory pensions: These are typically unaffected by a business sale because they’re managed outside of the private employer’s system.

    If you find yourself unsure, reach out to your pension administrator or HR department. You may also want to consult a financial advisor to make sure your rights are respected.

    3. Legal Protections You Should Know

    In many countries, laws exist to safeguard employee rights during business transfers. For instance, in jurisdictions using Transfer of Undertakings (Protection of Employment) regulations (commonly referred to as TUPE), your workplace benefits and pension rights often cannot be arbitrarily reduced. That said, the specifics of these laws vary depending on where you are, so it’s wise to familiarize yourself with your local employment protections.

    If, for any reason, you feel your rights are compromised—such as losing benefits that were promised—don’t hesitate to seek professional advice from a labor attorney or your local employment rights agency.

    4. Communicating with Your New Employer

    Showing initiative during the transition can also go a long way. Here are some tips for effective communication:

    1. Stay informed: Attend meetings or briefings and ask detailed questions about the status of your benefits package.
    2. Get things in writing: If there’s anything unclear, make sure to request written confirmation of changes or protections.
    3. Be proactive: If the new employer offers new benefits schemes, evaluate them carefully—sometimes changes might even work in your favor!

    Remember, changes to your workplace benefits and pensions can feel overwhelming, but knowledge is power. When in doubt, seek clarity, educate yourself on your rights, and don’t hesitate to get professional guidance. After all, these benefits aren’t just perks—they’re part of the foundation of your future security!

    What Actions Can I Take If My Rights Are Violated?

    Discovering that your employment rights have been violated following a business sale can feel overwhelming, but don’t worry—you have options! Whether it’s unfair treatment, unpaid benefits, or sudden changes to your agreed terms, there are steps you can take to stand up for yourself and ensure your concerns are addressed. Let’s break it down into actionable steps that you can follow if something doesn’t seem right.

    1. Know Your Rights

    The first step is understanding your rights in the situation. After a business sale, employee protections often remain intact, even if ownership changes. Laws like the Transfer of Undertakings (Protection of Employment) Regulations (commonly referred to as TUPE in the UK) or similar statutes in other countries might ensure that your employment terms, pay, and continuation of service remain unchanged. Educate yourself on these laws by researching reliable resources or consulting with your local labor office.

    2. Communicate with Your Employer

    Sometimes, employers are unaware that they might be infringing on your rights. Quiet conversations can go a long way in resolving misunderstandings! Approach your employer or HR department professionally to discuss your concerns and seek clarity. Use polite but firm language, and make sure to write down the main points beforehand so you don’t forget anything during the meeting.

    3. Keep Records of Everything

    Documentation is your best friend when dealing with any type of rights violation. Create a paper trail! Save emails, meeting notes, pay stubs, and contracts relevant to the issue. For example:

    • If you’ve been asked to sign a new contract, compare it to your current one and note any differences.
    • If specific workplace benefits haven’t been carried over after the sale, keep records of how they were previously applied.

    Having evidence on hand will strengthen your position if formal action is needed later on.

    4. Seek Advice from a Union or Legal Expert

    It’s okay to ask for help from a professional when the going gets tough. If you’re part of a labor union, contact your representative and explain your situation—they can negotiate on your behalf or provide much-needed support in handling disputes. If you’re not in a union, you might want to consult with an employment lawyer. Many legal professionals offer free initial consultations, so don’t hesitate to reach out.

    5. File a Formal Complaint

    If initial conversations with your employer don’t resolve the issue, filing a formal grievance is often the next step. This involves submitting your complaint in writing—be specific about what rights were violated, how they were impacted, and what resolution you’re looking for. Your employer is typically required to follow up within a set timeline.

    6. Escalate to Labor Authorities or Courts

    If all else fails, you might need to turn to government agencies, ombudsmen, or legal institutions. File a claim for wrongful dismissal, unpaid wages, or unfair labor practices if necessary. Many jurisdictions have employment tribunals or small claims processes specifically designed for such cases.

    Stay Calm and Empowered

    Remember, standing up for your rights is your right! While the process might feel daunting, you don’t have to navigate it alone. Whether it’s through a trusted advisor, a legal professional, or support from coworkers, there’s always someone who can help ensure you’re treated fairly. Ultimately, the goal isn’t just to fix the immediate issue—it’s about fostering a workplace where you feel respected, secure, and valued.

    Understanding Severance Pay and Legal Compensation Options

    Hello there! If you’re navigating the complex waters of a business sale, one crucial topic to understand is severance pay and your potential legal compensation options. No one wants to face the uncertainty of losing a role or seeing their rights neglected, so let’s break this down in a way that’s both approachable and informative.

    First things first: severance pay is essentially a sum of money paid to you by your employer if your employment is terminated under certain circumstances — like a business sale where your position is eliminated. But how can you ensure you’re getting what you’re entitled to? Let’s unpack the details.

    What Is Severance Pay, and When Does It Apply?

    Severance pay often acts as a financial safety net to help you transition after losing your role. However, not everyone is automatically entitled to it. Whether or not you receive severance usually depends on a few factors, including:

    • The terms outlined in your original employment contract — does it mention severance clauses?
    • Local labor laws or regulations in your country — these can set minimum standards for severance.
    • The reason for your termination — for instance, were you laid off due to restructuring after the business sale?

    If your position is eliminated as the new owner takes charge and no alternative is offered, severance pay may be on the table, provided it’s legally mandated or written into your contract.

    How Is Severance Pay Calculated?

    The exact amount varies. Here are some common elements that employers might consider:

    1. Your length of service with the company (e.g., years of experience).
    2. Your role and seniority level.
    3. Your base pay or average earnings over a set period.

    This means someone who’s been with a company for years may typically receive more compared to a newer hire. Curious about what you’re entitled to? Don’t hesitate to consult your employment contract or a legal advisor. Clarity is your best friend here.

    What Are My Legal Compensation Options?

    If severance pay isn’t offered or you feel shortchanged after the sale, you might have other paths to pursue legal compensation. Here’s what you can consider:

    • Back pay claims: Were you paid fairly before or during the business transition? If not, a claim for unpaid wages might be an option.
    • Wrongful termination claims: If your termination violated labor laws or the terms of your contract, you could seek legal reparations.
    • Negotiating a settlement: Sometimes, disputes can be resolved without going to court. Reach out to an employment lawyer or union representative for advice tailored to your case.

    Remember, it’s critical to keep detailed records: performance reviews, contracts, pay stubs, and communication leading up to the business sale. These can be valuable assets if you decide to challenge any unfair practices regarding severance or legal compensation.

  • Best Practices to Keep Track of Invoices and Payments.

    Best Practices to Keep Track of Invoices and Payments.

    Keeping track of invoices and payments is one of the most important aspects of running a business. A solid invoicing system ensures steady cash flow, minimizes late payments, and helps maintain good relationships with clients. Without proper tracking, businesses can run into financial trouble, leading to unnecessary stress and operational disruptions.

    In this article, we’ll go over practical ways to manage invoices and payments effectively. Whether you’re a small business owner or managing finances for a larger company, these strategies will help you stay organized and ensure your accounts remain in good shape.

    Understanding Invoice Tracking

    What is Invoice Tracking, and Why is It Important?

    Invoice tracking refers to the process of monitoring outgoing invoices and incoming payments. It helps businesses keep a record of what they are owed, who has paid, and what is still pending. Without proper tracking, a business might lose track of unpaid invoices, resulting in cash flow issues.

    Having an efficient system in place ensures that:

    • Payments are received on time.
    • Unpaid invoices are followed up promptly.
    • Financial records remain accurate.
    • Businesses avoid disputes with clients over missing payments.

    What Happens When Invoice Tracking is Poorly Managed?

    If a business does not track invoices properly, it may face several challenges:

    • Late or missed payments: Without reminders or follow-ups, clients may forget to pay.
    • Cash flow problems: Inconsistent tracking can lead to unexpected financial shortfalls.
    • Strained relationships: Clients might lose trust in businesses that frequently mismanage invoices.
    • Tax and compliance issues: Missing financial records can cause trouble when filing taxes.

    15 Practical Tips for Effective Invoice and Payment Tracking

    1. Implement a Standardized Invoicing System

    Use a consistent format for invoices, including invoice numbers, issue dates, due dates, and detailed descriptions of services or products. A well-structured invoice makes it easier for both parties to process payments smoothly. Standardization helps avoid confusion, ensures accuracy, and provides a clear reference for both the business and the client. Having a defined template minimizes errors and speeds up the invoicing process, allowing businesses to focus on other important tasks.

    2. Utilize Digital Tools

    Manually tracking invoices can be time-consuming and prone to errors. Using invoicing software simplifies the process, reducing the chances of mistakes and ensuring better organization. Digital tools help automate invoice creation, track due dates, and send reminders, making the entire process more efficient. With automated systems, businesses can reduce paperwork, improve accuracy, and ensure timely payments from clients.

    3. Set Clear Payment Terms

    Clearly state your payment terms in each invoice. Mention due dates, accepted payment methods, and any late payment penalties to ensure clients understand their responsibilities. Well-defined terms prevent misunderstandings and encourage timely payments. Be transparent about fees for late payments to deter delays. Setting expectations early helps maintain professional relationships and reduces disputes over payments.

    4. Schedule Regular Reviews

    Conduct frequent checks on outstanding invoices. Set aside time each week or month to review unpaid invoices and send reminders when needed. Regular reviews help identify overdue payments early and take action before they become significant issues. Having a structured review schedule prevents invoices from slipping through the cracks and ensures cash flow remains steady.

    5. Maintain Detailed Records

    Keep thorough records of all invoices, including issue dates, due dates, and payment confirmations. This helps in case of disputes and ensures accurate financial reporting. A well-maintained record system allows businesses to track past transactions easily, identify trends in late payments, and provide documentation when needed for legal or tax purposes. Proper record-keeping also simplifies annual financial audits.

    6. Reconcile Accounts Frequently

    Regularly match invoices with received payments. This helps identify any missing payments or incorrect amounts and allows for quick correction. Reconciling accounts ensures that all transactions are accounted for and prevents accounting errors that could lead to financial discrepancies. This practice also helps in catching fraud or mistakes in financial reporting early.

    7. Communicate Proactively with Clients

    Send polite reminders before due dates. If a payment is overdue, follow up promptly but professionally to resolve any issues. Good communication reduces the chances of clients forgetting payments and demonstrates professionalism. Addressing concerns proactively builds trust with clients and encourages smoother financial transactions in the long run.

    8. Offer Multiple Payment Options

    Providing clients with various payment methods—bank transfers, credit cards, digital wallets—makes it easier for them to pay on time. Giving customers the flexibility to choose their preferred method increases the chances of timely payments. Businesses that accommodate different payment preferences tend to experience fewer delays in receiving funds.

    9. Monitor Cash Flow Diligently

    Keep a close eye on cash flow by tracking outstanding payments. Knowing what is due and when allows for better financial planning. Businesses that actively monitor cash flow can make informed decisions on spending, investments, and operational adjustments. Cash flow awareness prevents unexpected shortfalls and ensures financial stability.

    10. Train Staff Thoroughly

    Ensure employees handling invoices understand the process, software, and policies to minimize errors and delays. Training staff on proper invoicing procedures improves efficiency and reduces mistakes. A knowledgeable team can respond to invoicing issues quickly, preventing delays and ensuring clients receive accurate billing information.

    11. Utilize Cloud-Based Solutions

    Cloud-based invoicing tools allow you to access records from anywhere, making it convenient to manage invoices remotely. Businesses that adopt cloud-based solutions benefit from enhanced security, automatic backups, and accessibility from multiple locations. This is especially useful for companies with remote teams or multiple office locations.

    12. Set Up Automated Reminders

    Use software to send automated payment reminders to clients. This reduces manual follow-ups and increases the likelihood of on-time payments. Automated reminders take the burden off employees while ensuring clients receive consistent payment notifications. Timely reminders significantly reduce late payments and improve overall cash flow management.

    13. Establish a Collections Process

    If a payment is significantly overdue, have a step-by-step collections process in place. This could include sending multiple reminders, applying late fees, or escalating the issue if necessary. A structured collections process helps businesses recover unpaid invoices without damaging client relationships. Having clear procedures in place ensures fairness and consistency.

    14. Regularly Update Client Information

    Ensure client contact details are accurate to prevent miscommunication and lost invoices. Keeping an up-to-date database minimizes invoice delivery issues and ensures prompt communication. Regular updates also prevent administrative delays that can slow down the payment process and cause unnecessary confusion.

    15. Seek Professional Advice When Necessary

    If you struggle with invoice management, consult a financial expert or accountant to streamline the process. Professional guidance can help businesses optimize invoicing procedures, ensure tax compliance, and implement strategies to prevent late payments. Expert advice is particularly valuable for businesses looking to scale operations efficiently.

    Features to Look for in Invoice Tracking Software

    1. Automation Capabilities

    Good invoicing software should automate tasks like sending invoices, reminders, and receipts to save time and reduce errors.

    2. Integration with Accounting Systems

    The software should work well with your accounting tools to simplify financial management.

    3. Reporting and Analytics

    Tracking payment trends and outstanding invoices can help businesses make informed financial decisions.

    4. User-Friendly Interface

    A simple and easy-to-use platform ensures quick adoption and minimizes training needs.

    Addressing Common Questions

    How Can Small Businesses Manage Invoicing Effectively?

    Small businesses can benefit from using simple and affordable invoicing software. Setting clear payment terms and following up consistently can also help maintain smooth cash flow.

    What Are the Benefits of Electronic Invoicing?

    Electronic invoicing speeds up the payment process, reduces manual errors, and ensures better record-keeping.

    How Often Should Businesses Review Their Invoicing Processes?

    It’s a good practice to review invoicing and payment tracking methods monthly or quarterly to ensure efficiency.

    What Steps Can Be Taken If a Client Consistently Pays Late?

    Consider renegotiating payment terms, implementing late fees, or reassessing whether the client is worth the continued business relationship.

    Conclusion

    Accurate invoice and payment tracking is essential for keeping business finances stable. By following these best practices, businesses can avoid unnecessary delays, improve cash flow, and maintain positive relationships with clients. Using the right tools and strategies will make the entire invoicing process more efficient, helping businesses stay financially secure.