Author: Ahmad Firdous

  • What is a capital expense

    What is a capital expense

    Let’s face it—financial jargon can sometimes feel like an entirely different language. However, understanding capital expenses (frequently called CapEx) is crucial for anyone looking to navigate the world of business finance. Whether you run your own company, manage budgets, or are simply curious about how businesses use their resources, a solid understanding of CapEx can set you up for success. Let’s break it down together in plain, approachable terms.

    What Exactly Are Capital Expenses?

    Simply put, capital expenses are investments made to acquire, upgrade, or maintain physical or intangible assets that will drive long-term value for a business. Think of it as spending money on something that will help the company grow or operate over an extended period.

    For example, purchasing a new office building, acquiring manufacturing equipment, or even developing a software system for internal use all fall under the umbrella of CapEx. These aren’t day-to-day costs, but rather strategic investments for the future. As you might imagine, these expenses require careful consideration since they typically involve large sums of money.

    Why Do Capital Expenses Matter?

    Great question! Capital expenses differ from regular, everyday operational costs because they lay the foundation for sustained business success. By funding projects or assets that promise long-term benefits, companies can improve their efficiency, expand their capabilities, or stay competitive in a rapidly evolving marketplace.

    For instance, when a tech company invests in cutting-edge servers that enhance their cloud computing processes, they’re not just spending money—they’re ensuring their infrastructure can handle future growth and customer demands. It’s all about thinking ahead.

    Key Characteristics of Capital Expenses

    If you’re unsure whether a particular purchase qualifies as a capital expense, here are some traits that typically define CapEx:

    • Long-Term Benefit: If the expenditure adds value over time (e.g., five or ten years), it’s likely a capital expense.
    • Associated with a Fixed Asset: Most capital expenses are tied to acquiring or enhancing fixed assets like property, equipment, or technology.
    • Significant Upfront Cost: Unlike minor purchases or consumables, capital expenses often involve a substantial initial payment or significant financial planning.
    • Not Recurring: Sure, you might repair equipment now and then, but buying a new machine or building is less frequent and carefully planned.

    A Common Misstep: Mixing CapEx with OpEx

    One common area of confusion arises when capital expenses are confused with operational expenses (OpEx). While both represent money outflow, they serve different purposes. Capital expenses are all about long-term investments, while OpEx pertains to daily expenses, like paying employee salaries or covering utility bills.

    Think of it this way: buying a new delivery truck for your business is CapEx because you’ll use it for years, whereas filling it up with gas weekly is OpEx. Got it? Great!

    expenses

    Capital vs. Operational Expenses: Spotting the Key Difference

    Ever feel confused about the terms “capital expenses” and “operational expenses” floating around in conversations about business finances? Don’t worry—you’re not alone. For many, these two concepts sound similar, but understanding their difference is crucial for maintaining a healthy business. Let’s break it down together!

    How to Identify a Capital Expense (CapEx)

    A capital expense is all about investing in things your business needs to grow and sustain itself over the long term. These are usually one-time purchases and often include:

    • Buying a new building for your office or shop
    • Purchasing machinery to produce your product
    • Upgrading your company’s IT infrastructure

    Now here’s the kicker: Capital expenses create tangible or intangible assets. So if it’s something that your business owns, holds value, and can be resold or depreciated over years, it’s likely a CapEx.

    Spotting an Operational Expense (OpEx)

    Operational expenses are the recurring costs that keep your business running. Without these, maintaining day-to-day activities would be impossible. Examples include:

    • Monthly salaries for your employees
    • Utility bills like electricity and water
    • Costs of marketing, such as advertising campaigns

    The main difference here is that OpEx is typically incurred for the short term. They don’t create an asset but, instead, keep your operations running smoothly. Think of these as the fuel your business needs every month to stay functional and competitive.

    Why Does This Difference Matter?

    Knowing whether an expense is CapEx or OpEx isn’t just about using the correct terminology—it has a direct impact on how you budget, account, and even handle taxes for your business. Here’s why this distinction matters:

    1. Budget Planning: Capital expenses often require more upfront investment but promise long-term benefits. Operational expenses, on the other hand, are more consistent but ongoing. Differentiating between the two can help you allocate resources wisely.
    2. Accounting Practices: CapEx often gets recorded as an asset and depreciated over time, while OpEx is recorded as an immediate expense, directly hitting your profit and loss statement.
    3. Business Strategy: Recognizing when to spend on long-term growth (CapEx) versus maintaining efficient day-to-day operations (OpEx) can set your business up for long-term success.

    Examples That Define Capital Expenses in Real-Life Scenarios

    Capital expenses (CapEx) may sound like a complicated term, but it’s simply about the long-term investments a business makes to build or improve its ability to generate profits. To make it clearer, let’s dive into some real-life examples of capital expenses. By understanding these examples, you can better identify and handle CapEx in your own business or personal investments.

    1. Investing in Office Equipment

    One common example of a capital expense is purchasing office equipment. Let’s say you’re running a marketing agency, and your team needs top-of-the-line computers to handle graphic design rendering tools or video editing. Buying those computers would be considered a capital expense because they are assets with a useful life that extends beyond a single year. It’s important to note that regular maintenance or repairs for these computers would typically fall under operational expenses, not CapEx.

    2. Building or Expanding Commercial Space

    Another excellent real-world example is construction projects. Imagine a retail business deciding to build a new store or expand its existing location. The costs of construction, purchasing land, and installing permanent fixtures like lighting or flooring are categorized as capital expenses. These investments are treated as long-term assets that help the business grow over time.

    3. Acquiring High-Value Machinery or Equipment

    For manufacturing businesses, purchasing machinery is a perfect representation of a capital expense. For instance, if a factory invests in a new production line that will increase its output for years to come, this expenditure qualifies as CapEx. The upfront cost may be substantial, but its impact is long-lasting, making it a critical category for long-term planning.

    4. Upgrading Technology and Software

    Here’s a modern example many businesses can relate to: upgrading to a cloud-based software platform. If a company decides to implement an enterprise-level customer relationship management (CRM) system to streamline operations, this investment is often treated as a capital expense. The software itself, along with any necessary servers or IT infrastructure upgrades, represents long-term assets that directly influence the company’s efficiency and performance.

    5. Vehicles for Business Use

    Companies that depend on transportation often allocate a portion of their CapEx budget to vehicles. Delivery trucks for a logistics business or company cars for a sales team count as capital expenses. Because these vehicles will be used for years and materially add to the business’s earning potential, they fit squarely into the category of CapEx.

    6. Renovations and Major Repairs

    Here’s another real-life situation: you own a hotel, and you decide to undertake a complete renovation of the lobby to enhance the customer experience. Significant renovations like this don’t just maintain your business; they add to its future value, which is the hallmark of a capital expense. On the other hand, fixing a broken door or repainting the lobby would likely be operational expenses instead of CapEx.

    The Role of Capital Expenses in Business Growth and Strategy

    When it comes to laying the foundation for business success, capital expenses (or CapEx, as the pros call it) play a starring role. Businesses, whether they are startups or established giants, rely on strategic capital investments to fuel growth and stay ahead of the competition. But how exactly do capital expenses contribute to growth and strategy? Let’s break it down in a friendly, easy-to-follow way!

    1. Building a Competitive Edge

    In the ever-evolving world of business, staying one step ahead is key. That’s where capital expenses come in. Investments in assets like state-of-the-art equipment, advanced technology, and modern facilities not only improve efficiency but also give businesses the tools they need to outpace competitors.

    Think of it this way: If a restaurant invests in a high-tech oven that cooks meals faster and better, it’s likely to attract more customers. Similarly, a tech company that invests in cutting-edge servers can deliver faster solutions for its clients. These aren’t just expenses—they’re strategic moves to gain a long-term advantage.

    2. Laying the Groundwork for Scalability

    Growth doesn’t happen overnight—it’s a long-term game, and capital expenses help businesses prepare for scaling. Imagine a company preparing to increase its production output in five years. Do they wait until demand peaks? Of course not! They strategize early, purchasing industrial machinery, upgrading storage facilities, or even expanding office space in anticipation of that future boom.

    This foresight gives businesses the capacity to grow without the panic or hiccups of playing catch-up later.

    3. Diversifying to Tap New Markets

    What if your business decides it’s time to diversify its offerings? Say a retail company plans to move into e-commerce or expand into international markets. These strategic goals often require significant capital investments, such as developing a robust online platform or acquiring warehouses overseas.

    By strategically allocating capital expenses, businesses can seize new opportunities, explore untapped markets, and fuel innovation—all of which play a critical role in growth.

    4. Attracting Investors and Securing Finances

    Here’s something you might not realize: smart capital expenditures can enhance your company’s appeal to investors and lenders. A well-thought-out CapEx plan signals that your business is forward-thinking and stable, which is music to the ears of potential backers.

    For example, showcasing investments in energy-efficient equipment not only promises long-term savings but also identifies your business as environmentally responsible—all of which paints a brighter and more promising picture for stakeholders.

    5. Strengthening the Business Backbone

    Last, but certainly not least, capital expenses strengthen the very backbone of a business: its infrastructure. From IT systems that enable seamless communication to office buildings that foster teamwork and creativity, these investments create an environment where growth isn’t just possible—it’s inevitable.

    Tax Implications: How Capital Expenses Can Impact Your Finances

    When you hear the term “capital expenses,” your first thought might be how these large investments can help your business grow. But there’s an equally important aspect that often flies under the radar — taxes. Yes, those big-ticket items your business invests in, like equipment, real estate, or software, can significantly influence your tax situation. Let’s dive into the details in a way that makes taxes less, well, taxing!

    Understanding Capital Expenses and Tax Benefits

    Here’s the deal: capital expenses (or CapEx) aren’t treated the same way as everyday operational costs in the eyes of the taxman. Capital expenses are considered long-term investments, meaning they provide benefits to your business for several years. Because of this, you typically don’t get to deduct the entire expense in the year you make the purchase. Instead, their cost is spread out over the useful life of the asset — a concept known as depreciation or amortization.

    For example, let’s say you purchase new manufacturing machinery for $100,000. Instead of claiming that entire amount as a deduction in year one, you’ll write off a portion of it over several years based on the IRS-defined lifespan of similar equipment. Why does this matter? Those deductions, spread out over time, can significantly reduce your taxable income every year until the asset is fully depreciated.

    Some Tax Perks You Don’t Want to Miss

    • Bonus Depreciation: In some instances, government legislation allows you to accelerate the depreciation of an asset. For instance, instead of spreading deductions across multiple years, bonus depreciation lets you claim a larger portion (or even the full cost) in the initial year of purchase. It’s like getting a head start on saving!
    • Section 179 Deduction: If you’re a small business, Section 179 could be your new best friend. This provision allows you to deduct the full purchase price of qualifying equipment or software in the year it’s placed in service, up to a certain limit. It’s an amazing way to offset the cost of necessary upgrades without waiting years for tax benefits.

    Common Missteps to Avoid

    1. Mistaking Repairs for Capital Expenses: Not every improvement or maintenance task you perform qualifies as a capital expense. Patching a hole in the roof? Likely a repair. Replacing the entire roof? Now that might be a capital expense.
    2. Not Tracking Properly: Failing to maintain meticulous records of your capital expenses can backfire. Keep detailed records of purchase dates, amounts, and documentation to support your depreciation or deductions come tax season.
    3. Neglecting to Consult a Tax Advisor: Tax laws around capital expenses, depreciation, and deductions can be complex and subject to change. An experienced accountant or financial advisor can help you strategize and ensure compliance while maximizing tax advantages.

    Accounting for Capital Expenses: The Right Way to Do It

    Hey there! Let’s talk about something that might sound a bit complex but is absolutely crucial for the financial health of your business: accounting for capital expenses. Now, before your eyes glaze over, stick with me—I promise to keep things clear, actionable, and even a bit fun. 🎉

    What Are Capital Expenses, Anyway?

    First things first, let’s recap what capital expenses (or CapEx, as the cool accountants call it) are. In simple terms, capital expenses are the big-ticket items your business invests in to generate future profits. Think of these as long-term assets—things you’ll rely on over several years. Common examples? Upgrading office equipment, purchasing company vehicles, or investing in property. Unlike operational expenses (OpEx), CapEx represents investments, not day-to-day spending.

    Why Proper Accounting for Capital Expenses Matters

    Here’s the deal: you can’t just treat capital expenses like any other expense and dump them into your books all at once. Why? Because they’re not about short-term spending; they’re investments that benefit your business over time. Correctly accounting for them ensures:

    • Accurate financial reporting: Investors and stakeholders need clarity. Mismanaging CapEx can skew your numbers and cause confusion.
    • Smarter decision-making: Proper records give you a clearer picture of how and where your money is tied up, helping you make strategic investments in the future.
    • Tax compliance: Some CapEx-related expenses can be depreciated (more on that later), offering potential tax benefits if handled correctly.

    The Right Way to Handle Capital Expenses in Your Books

    Okay, let’s break this down step by step. Here’s how to make sure you’re accounting for capital expenses the right way:

    1. Determine whether it counts as CapEx: Not every purchase qualifies. Generally, the expense must benefit your business for more than a year. So while buying new staplers for the office wouldn’t count, upgrading to state-of-the-art machinery probably would.
    2. Record the cost as an asset: Instead of recording the entire expense in a single year, CapEx is treated as an asset in your balance sheet.
    3. Account for depreciation: Most capital assets lose value over time (except for things like land). Depreciation allows you to spread the cost of the asset across its useful life. This both reflects its decreasing value and reduces your taxable income each year.
    4. Stay organized: Keep detailed records of all capital purchases, including invoices, receipts, and contracts. Trust me, this makes life so much easier when tax season rolls around or if your business ever gets audited.

    Tools and Tips for Streamlined Accounting

    Nobody wants to handle CapEx with a pen and paper in this day and age. Thankfully, there are tools to help make the process smoother:

    • Invest in accounting software: Platforms like QuickBooks, Xero, or FreshBooks are fantastic for tracking expenses, depreciation schedules, and more.
    • Work with a professional: If CapEx feels overwhelming, hiring an accountant is worth the investment. They can ensure proper reporting and compliance with tax regulations.
    • Review regularly: Don’t treat your CapEx accounting as a “set it and forget it” task. Schedule periodic reviews to ensure your records remain accurate and up-to-date.

    Making Smart Decisions with Capital Expenses in Mind

    Capital expenses—an investment today that paves the way for future growth and stability. But as exciting (or perhaps daunting) as the term may sound, making smart decisions about these expenses is easier said than done. Don’t worry, though! With a little guidance and a sprinkle of strategic thinking, you can make capital expenses work in your favor while avoiding missteps along the way.

    What’s the Big Deal About Being “Smart” with Capital Spending?

    At its core, smart decision-making with capital expenses boils down to one key principle: maximizing returns while minimizing risks. Every dollar you put toward capital expenses should yield long-term benefits—whether that’s greater efficiency, improved infrastructure, or future revenue. So, how do you ensure you’re hitting that sweet spot?

    Key Questions to Ask Before Making a Capital Investment

    Before greenlighting a major expenditure, make it a habit to ask yourself (or your team) these critical questions:

    1. Is the timing right? Consider both your current financial standing and market conditions. Are you in a position to spend, or is it wiser to hold off?
    2. Does it align with long-term goals? Any investment in fixed assets—machinery, buildings, new technology—should tie into the broader vision for your business or personal financial plan.
    3. What’s the return on investment (ROI)? While not every capital expense will have a direct monetary return, understanding its value (be it increased productivity or reduced costs) is essential.
    4. Have all risks been evaluated? Unexpected costs, delays, or maintenance requirements can derail even the best-laid plans. Make sure you’ve accounted for those.

    By putting these questions front and center, you can approach capital expenses proactively instead of reactively—giving you a better chance at making informed decisions.

    A Few Tried-and-Tested Tips for Smart Spending

    Here are some expert tips to keep you ahead of the curve:

    • Create a capital expense budget: Set aside funds specifically for long-term investments. This not only helps you avoid overspending but also ensures you’re prepared for opportunities when they arise.
    • Don’t shy away from professional advice: Engaging with financial advisors or industry experts can provide clarity on potential purchases and help you understand their implications.
    • Regularly review your assets: Sometimes, fixing or optimizing what you already have can be more effective than purchasing something new. A thorough audit of your existing assets can reveal hidden opportunities.
    • Aim for flexibility: Choose investments that allow some adaptability. For example, modular equipment or scalable software can grow with you instead of becoming obsolete after a few years.
  • What does per diem mean

    What does per diem mean

    Let’s face it—latinate terms like “per diem” can sound a bit intimidating at first. But don’t worry, it’s simpler than it seems! At its core, “per diem” is just a fancy way of saying “per day.”

    In practical terms, per diem is a daily allowance provided for specific purposes, most often related to work or travel. So instead of having someone keep receipts for every cup of coffee, meals, or random hotel extras, the concept allows for a fixed amount to cover these expenses on a day-to-day basis. Convenient, right?

    What Does Per Diem Cover?

    Here’s an easy way to think about per diem: it’s money given to you to cover costs associated with living or working away from your regular circumstances. The “living” part means daily necessities—food, lodging, and incidental expenses when you’re traveling or working in an unfamiliar location. It’s a kind of no-fuss method to ensure that you won’t have to dip into your own wallet to stay fed and have a comfy pillow to rest on.

    • It can include meals and incidental expenses (sometimes nicknamed M&IE in accounting jargon). This might refer to anything from breakfast to a tip left for hotel staff.
    • It can cover lodging, but not always. Some companies treat lodging as part of a separate policy.
    • It’s often tied to specific rates. For instance, organizations might use government per diem rates as a guideline to determine fair daily amounts for certain locations.

    How is Per Diem Different Than Just Paying Expenses?

    Great question! What makes per diem super useful is its simplicity. Instead of tracking every penny spent on meals, gas, or accommodations, you’re handed a predetermined sum upfront or reimbursed a set amount later. This eliminates the boring job of combing through receipts—or worse, having heated debates about whether that $6 airport coffee was “really necessary.”

    Employers love the predictability this system offers. Employees love the flexibility—no need to explain why Taco Tuesday was worth the splurge!

    Is Per Diem Always the Same Amount?

    Not quite! The amount can vary depending on where you are, who you work for, or any specific policies your company follows. For example:

    1. Location matters: Larger cities or high-cost areas often mean higher per diem amounts. If you’re visiting a bustling hub like New York City, your daily allowance is likely to be higher compared to a small rural town.
    2. Job specifics: Your industry might also determine rates. Contractors or consultants working on temporary assignments may get different allowances than salespeople attending a conference.

    Per Diem in Work and Travel: A Practical Guide

    When you hear the phrase “per diem,” what comes to mind? A confusing work expense? A mysterious line on a company’s travel policy? Don’t worry—per diem isn’t as complex as it sounds, and we’re here to make it crystal clear for you. Understanding how per diem is applied to work and travel could save you time, simplify your professional expenses, and even make business trips more enjoyable.

    What Is Per Diem in Work and Travel Settings?

    In the most straightforward terms, per diem refers to a daily allowance that employers provide to employees to cover work-related expenses when they’re away from home. Rather than tracking every cup of coffee or restaurant bill, the employee receives a fixed amount each day to simplify the process.

    Sounds convenient, right? It is! Employers set these amounts to cover specific categories, such as:

    • Meals
    • Lodging (if not pre-arranged by the employer)
    • Incidental expenses (think tips, snacks, or small purchases)

    The goal is to make work travel hassle-free, allowing employees to focus on their tasks rather than stress over compiling endless receipts or itemized reports.

    How Does Per Diem Actually Work?

    Employers typically set per diem rates based on federal guidelines, industry standards, or specific company policies. For instance, in the United States, the General Services Administration (GSA) provides updated per diem rates for lodging and meals, which vary by location.

    Here’s how it usually works:

    1. The company defines the daily per diem rate, which may differ for high-cost and low-cost destinations.
    2. Employees traveling for work receive the set amount, either via direct reimbursement or as part of their paycheck.
    3. The employee uses the money for qualified expenses and doesn’t typically need to provide detailed receipts (although exceptions may exist for unusual circumstances).

    Once the trip is over, there’s often no need for back-and-forth expense audits—it’s all wrapped up with a single rate!

    Key Benefits of Using Per Diem

    Wondering why per diem policies are so popular? They’re a win-win for both employers and employees. Here’s why:

    • Simplifies Expense Tracking: Fixed amounts eliminate the need for compiling stacks of receipts.
    • Encourages Smart Spending: Employees have more control over how they allocate their meal or lodging budgets.
    • Reduces Disputes: Pre-set rates make costs predictable and transparent, avoiding arguments over what’s “reasonable.”
    • Saves Time: Both parties save time on reporting, approvals, and processing.

    Tips for Employers and Employees

    Whether you’re a manager implementing a policy or an employee on the road, keep these tips in mind when working with per diem:

    • Stay Informed: Employees should familiarize themselves with the employer’s specific per diem rates and rules before heading out.
    • Track Exceptions Carefully: If your work trip covers unusual expenses (like an industry gala or long-term stays), check ahead to ensure those costs fit within the employer’s guidelines.
    • Align with Federal Guidelines: Employers, make sure the per diem rates you set are reasonable and compliant with any government standards that apply.

    Common Scenarios Where Per Diem Applies

    Ever wondered why businesses and organizations use per diem? That’s because it serves as a simple, standardized, and practical way to handle costs. Let’s dive into some common scenarios where per diem comes into play so you can see how it works in real-world situations.

    1. Business Travel

    One of the most familiar uses of per diem is for covering business travel expenses. Imagine you’re an employee traveling to another city for a conference or client meeting. Instead of submitting a pile of receipts for meals, lodging, and minor expenses, your employer sets a daily per diem rate. This provides you with the freedom to manage your budget within those limits. Easy, right?

    For instance, a company might offer a per diem of $200 per day to cover hotel stays, meals, and transportation. If you’re frugal and spend less, you get to pocket the difference in many cases (depending on the organization’s policy). It’s a win-win for both employers and employees—less paperwork, more convenience.

    2. Temporary Assignments

    Another common use of per diem is for employees on temporary assignments. Let’s say your employer asks you to work on a project in a different city for a few months. Instead of relocating entirely or spending endless hours tracking every expense, you’d receive a daily per diem to cover essential living costs like meals and lodging while you’re away from home base.

    This situation is especially popular in industries like construction, where workers often take on short-term projects far from home. It allows employees to focus on their work while ensuring their travel-related needs are met in a stress-free way.

    3. Freelancers and Contractors Working Off-Site

    Per diem isn’t just for full-time employees! Freelancers and independent contractors might also receive a per diem when companies hire them for assignments requiring off-site work. Say you’re a photographer hired to shoot an event in another city. The company may provide a per diem to cover your meals, lodging, and related expenses, rather than reimbursing every receipt you submit. It simplifies everything for both parties.

    This use of per diem is particularly helpful for creative professionals, consultants, and project-based workers who frequently work on location.

    4. Government and Military Roles

    Government employees, as well as military personnel, frequently rely on per diem when traveling for official duties. The General Services Administration (GSA) in the U.S. even publishes standardized per diem rates for various locations, which cover lodging, meals, and incidental expenses (M&IE). These rates are adjusted based on the city you’re visiting, as costs may vary between a bustling metropolis and a small rural town.

    This structured approach ensures fair compensation and helps personnel focus on their tasks without worrying about expenses or compliance with budgeting rules.

    5. Training and Educational Programs

    Attending a training seminar, workshop, or even certification program off-site? Many companies and organizations provide per diem in such instances. This is especially common for jobs that require continuous learning or skill upgrades, such as healthcare professionals, legal experts, or IT specialists. Per diem in these cases typically includes allowances for meals and transportation but may not always extend to accommodation, depending on the program’s location and duration.

    Per Diem vs. Reimbursement: Key Insights

    When it comes to covering work-related expenses, you’ve likely heard two terms thrown around: per diem and reimbursement. At first glance, they might seem similar—both deal with footing the bill for employees’ expenses. But understanding the differences can help you navigate these concepts more effectively, both as an employee and an employer. Let’s break it down in a friendly, straightforward way!

    What Exactly Is Per Diem?

    Per diem is Latin for “per day,” and that’s exactly how it works. It’s a daily allowance that employers provide to cover specific work-related costs, like meals, lodging, or incidental expenses (think tips or minor on-the-go costs). Instead of itemizing receipts, employees receive a set amount, often based on established rates, such as those provided by government agencies or company policies.

    The biggest perk? Simplicity. With per diem, it’s “here’s X amount, spend it wisely.” No hassle of keeping dozens of receipts or worrying about going over the budget (as long as you stay within the per diem limit).

    What About Reimbursement?

    Reimbursement works differently. Here, employees pay for work-related expenses upfront, track their spending meticulously through receipts, and then submit those costs for repayment. For example, if you’re on a business trip and pay for a hotel, lunch, or a taxi ride, you’d provide proof of payment later to get your money back.

    While reimbursement offers employees the freedom to itemize every need, it adds layers of complexity. It requires tracking every single expense—sometimes down to the dollar. Employers, on the other hand, have to validate and approve each expense, a process that can get time-consuming fast.

    How Are Per Diem and Reimbursement Different?

    Let’s make things even clearer with some side-by-side comparisons:

    • Simplicity: Per diem wins this round. It gives employees a flat daily allowance, eliminating receipts in most cases. Reimbursement, on the other hand, requires detailed documentation of every cost.
    • Flexibility: Reimbursement gives more freedom. Employees can spend on whatever is necessary (within reason) and get reimbursed. Per diem may feel restrictive if daily allocations don’t match actual costs.
    • Transparency: Reimbursement offers a clear picture of spending but at the cost of time and effort. With per diem, the spending breakdown isn’t as detailed, though it’s easier to handle.
    • Predictability: Employers often prefer per diem because it creates a fixed expense, making budgeting easier. Reimbursements can fluctuate depending on employees’ spending habits.
    • Employee Impact: Some employees appreciate the freedom to spend allotments from per diem as they choose, while others may prefer not to front their own money (a key drawback of reimbursement).

    When Is Each Approach the Best Fit?

    The choice between per diem and reimbursement often depends on the situation:

    1. Per diem: Ideal for employees who frequently travel, such as consultants, trainers, or sales reps. It’s an excellent option for simplicity and a clear allocation of funds.
    2. Reimbursement: Better for occasional expenses or unique purchases outside the scope that a flat per diem couldn’t cover—like equipment, client dinners, or last-minute travel changes.

    Tax Rules and Compliance: What You Need to Know About Per Diem

    Let’s be honest: taxes can often feel like a minefield, especially when it comes to understanding unique concepts like per diem payments. But don’t worry—we’re here to break it down in a simple, straightforward way. Whether you’re an employee, a business owner, or someone who loves to stay informed, understanding tax rules and compliance surrounding per diem is essential. So, let’s dive in and untangle the world of taxes and per diem together!

    What Makes Per Diem Tax-Friendly?

    Here’s the good news: per diem payments are not always taxable. That’s right! When used appropriately and within IRS guidelines (for those in the U.S.), per diem payments for travel expenses like lodging, meals, and incidental costs can often be excluded from taxable income. Essentially, these payments act as a reimbursement for work-related travel rather than a direct form of additional compensation.

    However, there’s a catch. To keep these payments non-taxable, both employers and employees need to follow certain rules. If the payments exceed the IRS-approved rates or are not properly documented, they could become taxable. And trust me, no one wants that surprise on their paycheck or financial statements!

    The Golden Rule: Stick to the IRS Guidelines

    The IRS publishes standard per diem rates each year, covering lodging, meals, and incidental expenses for various locations. These rates are critical to follow for compliance purposes. Here’s a pro tip: the rates often vary depending on the city you’re traveling to—major metropolitan areas typically have higher allowances than rural towns. Make sure to check the IRS website for the latest rates before starting any business travel.

    Employers need to ensure that any per diem payments stay within these guidelines to remain tax-free, while employees should double-check that any amounts they receive are aligned with what the IRS allows for their destination.

    Recordkeeping: Your New Travel Best Friend

    Want to keep things tax-free? Then you’ll need to embrace the power of documentation. Whether you’re receiving or issuing per diem payments, accurate recordkeeping is non-negotiable. For employees, this might mean submitting an itemized expense report that includes:

    • The date and location of the business trip
    • The purpose of the travel
    • Receipts for covered expenses, when necessary

    Employers, on the other hand, should have systems in place to ensure these reports are reviewed and stored properly (hello, organized files!). Failure to provide or maintain adequate records could shift those per diem payments into the taxable column—a headache for all involved.

    FAQs: Clearing Up Common Confusions

    1. What happens if per diem payments exceed IRS rates?
      Any amount above the IRS-approved rates becomes taxable income for the employee, which has to be reported on their W-2 form.
    2. Can I deduct per diem as a self-employed individual?
      Absolutely! Just be sure to use the standard rates and keep meticulous records of your travel-related expenses for tax purposes.

    How Employers Define and Implement Per Diem Policies

    When it comes to providing financial support for employees who travel or work away from home, per diem policies are a popular solution. But how do employers actually decide on and implement these policies? Let’s dive into the mechanics of it all, breaking things down into simple, easy-to-understand insights.

    Understanding the Basics: What Employers Aim to Achieve

    From an employer’s perspective, per diem policies serve a dual purpose: they simplify expense management while ensuring employees are adequately covered for work-related travel costs. Whether it’s meals, lodging, or incidental expenses, the goal is to avoid the hassle of collecting and processing endless receipts, while still offering fair compensation for out-of-pocket costs.

    Employers design these systems to strike a balance between supporting their staff and maintaining financial efficiency. This ensures that traveling employees feel supported without creating unnecessary administrative burdens or overspending from the company’s budget.

    Key Components of a Per Diem Policy

    Crafting a per diem policy requires thoughtful planning and attention to detail. Here are some of the main elements employers consider:

    • Daily Rate Limits: Employers often set a fixed amount for daily expenses based on government guidelines (like those from the General Services Administration [GSA] in the U.S.) or industry standards. This ensures consistency while taking into account cost-of-living differences across various regions.
    • Covered Categories: Policies typically specify what the per diem covers. This could include meals, lodging, and incidental expenses—like tipping taxi drivers or hotel staff. Some companies split the allowance for clarity (e.g., $50 for meals, $20 for incidentals).
    • Travel Destinations: Per diem rates may vary depending on the travel destination. High-cost cities, for instance, may have higher rates to reasonably accommodate the higher expenses incurred there.
    • Eligibility Criteria: Not all employees qualify for per diem. Employers outline clear rules, such as requiring overnight stays or a minimum distance from the employee’s home or primary worksite.
    • Documentation Requirements: Employees are often asked to document their travel dates and purposes (even if receipts aren’t required for every meal). This keeps the process transparent and ensures proper policy compliance on both sides.

    Tailoring Policies to Fit the Organization

    The best per diem policies aren’t one-size-fits-all; they’re customized to fit a company’s unique needs and operations. For instance:

    1. **Local vs. International Travel:** Different rules may apply for domestic versus international trips. Some employers provide higher per diem rates for employees traveling internationally due to exchange rate considerations or higher costs in certain countries.
    2. **Role-Specific Adjustments:** Executives or employees in senior roles may have slightly higher allowances compared to entry-level positions, though fairness and consistency are still important.
    3. **Frequency of Updates:** Policies need occasional reviews to accommodate changes in living costs, tax regulations, or company budgets.

    How Employers Communicate Per Diem Policies

    A per diem policy is only as good as its communication. Employers typically ensure clarity by including these details in employee handbooks or internal portals. During onboarding or training sessions, hiring managers may walk employees through the policy to avoid confusion—a proactive approach that also cuts down on administrative questions later.

    Moreover, some employers use software or dedicated expense platforms to automate per diem distribution and tracking. These tools make it easier for both the employee and management to stay on the same page.

     Per Diem in Action: Examples Across Different Industries

    Per Diem can sound like just another workplace buzzword, but when it’s implemented in real-world scenarios, it shines as an incredibly flexible and efficient way to handle expenses. Across industries, Per Diem policies are used to make work and travel smoother and more predictable for employees and employers alike. Let’s walk through some practical examples to see how it’s applied.

    1. The Consulting Firm: Staying Productive on the Road

    Consultants are no strangers to travel. In this industry, professionals often hop from one client site to another, sometimes spending weeks outside their home base. Instead of requiring consultants to save every restaurant receipt or hotel bill, many firms provide a Per Diem allowance for food, lodging, and incidental expenses. For example, a consultant traveling to New York City might get a daily Per Diem of $75 for meals and $250 for lodging. This approach not only simplifies bookkeeping but also gives consultants more autonomy to manage their routines without worrying about micromanagement or reimbursement hiccups.

    2. Healthcare Workers on Assignment

    Travel nurses and other healthcare professionals often relocate for temporary assignments, sometimes working in different cities for weeks or months at a time. Here, Per Diem is a game-changer. Hospitals or staffing agencies often provide a daily stipend for housing and meals, helping these workers quickly settle into their new roles. For instance, a travel nurse stationed in Dallas for three months might receive $130 a day to cover meals and other living expenses. This removes the stress of chasing receipts while ensuring the professionals can focus on the crucial task of patient care.

    3. The Entertainment Industry: Lights, Camera, Per Diem!

    The entertainment industry is fast-paced, and production crews, actors, and stage managers often work on location for extended periods. Imagine a filmmaking crew shooting a blockbuster in a remote area. Instead of coordinating meal prep or reimbursing every purchase, the studio could offer Per Diem to each crew member. A standard Per Diem of $50 to $100 per day could cover meals and incidental costs like transportation to and from their lodgings. This setup keeps the production on schedule while maintaining morale (because hungry crew members are *not* happy crew members).

    4. The Nonprofit Realm: Missions with a Purpose

    Nonprofits often send employees or volunteers to support communities in need. Whether it’s disaster relief or sustainable development efforts, these missions involve travel to sometimes remote or underserved areas where tracking expenses can be particularly challenging. By offering Per Diem, nonprofits can ensure their workers have funds for meals and accommodations without dealing with cumbersome reimbursement paperwork. This isn’t just practical—it aligns perfectly with the high-pressure, high-impact nature of their work.

    5. The Tech Industry: Conferences and Training

    In the tech world, employees often attend conferences, hackathons, and training sessions across the globe. Here, Per Diem helps tech companies provide a flat daily rate to cover the cost of meals and incidentals. For example, a software engineer heading to a week-long conference in San Francisco might receive $100 per day for food and transportation. This ensures employees can focus on networking and learning new skills without worrying about reimbursement processes.


  • what does CCD stand for

    what does CCD stand for

    Hello there! Let’s dive right into understanding what CCD stands for and unravel this term in a way that makes sense to everyone. When you first hear “CCD,” your curiosity might immediately spark, and rightly so—it’s a term that pops up in many conversations, especially in technical contexts. But don’t worry, we’ll break it down step by step!

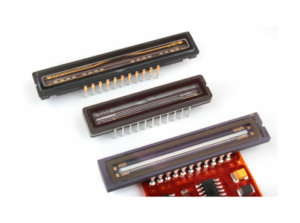
    So, at its core, CCD stands for Charge-Coupled Device. Sounds a bit techy, right? That’s okay! Let’s explore what this actually means and why it’s important. Think of a CCD as a clever piece of technology designed to capture and process light. But more than just a part of tech jargon, CCD is a key innovation that has had a transformative role in modern imaging and beyond.

    Why “Charge-Coupled”?

    Awesome question! The “charge-coupled” part relates to how CCDs work behind the scenes. It’s all about moving electrical charges across the device in a carefully coordinated sequence. These charges, generated when light hits the array of pixels in the CCD, are then processed to create the final image. Cool, right? It’s like a well-choreographed dance where every part has a role to play—resulting in crystal-clear images we enjoy!

    Roots of CCD: Tracing Its Origin Across Various Fields

    Let’s take a little trip back in time and across industries to explore the origins of “CCD” – an acronym you might’ve seen popping up in different conversations, products, or even academic papers. While the term “CCD” may seem ultra-modern, it actually has a rich history woven across multiple fields, from science to education and technology. Here’s how it all began and evolved!

    The Birth of Charge-Coupled Device (CCD) Technology

    If you’ve ever marveled at the beautiful images captured by a digital camera or telescope, you have CCD technology to thank. The concept of CCD originated in 1969 – a crucial year in its history – when George E. Smith and Willard Boyle at Bell Labs created the charge-coupled device. Their goal was to develop a new type of semiconductor memory for computer accelerator cards, but they soon realized it could also capture light and turn it into electronic signals.

    This accidental discovery was revolutionary, especially in photography, astronomy, and medical imaging. Though they were exploring something largely unrelated to image sensors, their breakthrough paved the way for technologies that would give us clearer, crisper images and data at previously unmatched resolutions.

    what is ASO in settlement: Read More.

    Religious and Educational Roots: CCD in Catechetical Teaching

    Outside of the tech space, CCD also finds its origins in religious contexts. In this sphere, CCD stands for “Confraternity of Christian Doctrine.” This program dates all the way back to the 1500s and was established by the Catholic Church in response to the challenges of religious education during the Protestant Reformation.

    Its purpose was simple yet profound: to provide structured catechetical instruction for children and adults, teaching the tenets of Catholic faith. Even today, when someone mentions CCD in a religious framework, it refers to this educational system, often part of preparatory programs for sacraments like First Communion or Confirmation. It’s fascinating to see how this usage has endured through centuries, emphasizing the lasting impact of these programs on Catholic communities worldwide.

    CCD in Academia’s DNA: Studying Colony Collapse Disorder

    Fast-forward to modern academia, and CCD has morphed into yet another context: Colony Collapse Disorder. This term describes the phenomenon where honeybee colonies mysteriously disappear. First reported in the early 2000s, CCD has since become a major area of concern for agricultural scientists, ecologists, and environmentalists alike.

    Honeybees play a critical role in pollinating crops, and their loss can have devastating effects on both ecosystems and food security. The roots of this term stem directly from the need to label and understand this perplexing and alarming issue. From universities to conservation groups, CCD in this context is a rallying point for informed action toward bee conservation.

    Common Misunderstandings: Clearing Up the Confusion

    Let’s face it—acronyms can be frustratingly tricky! When it comes to “CCD,” the waters get surprisingly murky. With its use across various industries and contexts, it’s no wonder people often find themselves scratching their heads. But don’t worry—we’re here to sort it all out and eliminate any confusion you might have about this seemingly small, yet surprisingly important three-letter acronym.

    What Is CCD, Really?

    One of the biggest misunderstandings around CCD is that it stands for only one thing. In reality, CCD is a classic multi-purpose acronym that pops up in vastly different areas of expertise. Depending on the context, CCD could have completely different meanings, which is where the confusion arises.

    For example:

    • In photography and imaging, CCD often refers to a Charge-Coupled Device, a critical component in many cameras and image sensors.
    • In religious or educational circles, CCD might stand for Confraternity of Christian Doctrine, an association for religious education in the Catholic Church.
    • In science and healthcare, CCD can also refer to a Continuity of Care Document, an important standard in medical information exchange.

    As you can see, the same acronym can carry very different meanings depending on the context it’s being used in!

    Why Do We Get So Confused?

    One reason CCD can cause so much confusion is that it’s frequently thrown around in specialized conversations. If you overhear someone discussing CCD without knowing the topic or context, it’s easy to misinterpret the meaning. Imagine someone says, “The school’s CCD program is expanding next year.” If you’re thinking about cameras, you might wonder why a school is getting involved in photography sensors!

    Another common pitfall lies in assuming the meaning of CCD is universal. This is especially true for tech-savvy individuals who associate the term exclusively with camera sensors, unaware of its religious or medical applications. It’s a great reminder that language isn’t always one-size-fits-all.

    Tips to Avoid Mistaking CCD’s Meaning

    If you often find yourself caught in the whirlwind of CCD confusion, here are some tips to help you stay on track:

    1. Pay attention to the context: Listen to or think about who is speaking and what the subject is. Are you in a discussion about cameras, medical records, or religious education?
    2. Don’t hesitate to ask: It’s better to clarify than to assume! Politely ask what CCD means in that particular scenario if you’re unsure.
    3. Get familiar with common uses: Knowing the typical fields where CCD pops up can help you make more educated guesses. (Hint: cameras, religion, medicine, and technology!)

    CCD in Technology: The Revolution in Image Sensors

    Let’s talk about CCD (Charge-Coupled Device) in the world of technology, specifically as it relates to image sensors. Have you ever marveled at the sharp, vibrant photos captured by cameras or stood amazed at the visual clarity of space photographs, like those taken by telescopes? If yes, then you’ve already seen the magic of CCD in action!

    CCD technology was a groundbreaking development in the field of imaging sensors, changing the way we capture and process images forever. It’s like the superhero of image sensors — versatile, consistent, and reliable. Let’s explore CCD’s role in this technological revolution and why it remains a cornerstone in the world of imaging, even amidst newer technologies.

    The Basics of CCD Technology

    At its core, a CCD sensor is a sophisticated device that captures light and converts it into electronic signals. It works in a systematic way, row by row, pixel by pixel, ensuring a high-quality and highly detailed image output. Each pixel on a CCD sensor measures the intensity of the light that hits it, and this data is translated into the beautiful visuals we see.

    Because of its accurate and low-noise image capturing capabilities, CCD paved the way for digital cameras to replace traditional film photography. Without it, we might still be fumbling around with rolls of film and chemical darkroom processes to develop photos!

    CCD in Cameras: First Steps into the Digital Era

    CCD sensors became the backbone of early digital cameras. Before their advent, professional photographers and hobbyists primarily relied on optical film cameras. But CCD technology catapulted photography into the digital age. The ability to capture, store, and share images digitally — thanks to CCD sensors — was revolutionary.

    Initially, CCD technology dominated the consumer and professional camera market in the form of digital still cameras, camcorders, and security cameras. Its ability to produce high-resolution, distortion-free images made it a favorite choice for photographers.

    CCD’s Role in Astronomy: A Window to the Stars

    One of the most striking applications of CCD technology is in astronomy. Thanks to CCDs, telescopes can take stunningly clear pictures of the night sky, distant galaxies, and even black holes.

    Did you know that NASA used large CCD arrays in major space projects like the Hubble Space Telescope? CCD allows astronomers to record faint light sources, distant planets, and comets with precision that older methods could never achieve.

    CCD in Scientific Applications

    Beyond photography and astronomy, CCD plays a vital role in fields like medical imaging (such as X-rays and endoscopy) and LIMS Software research tools like spectrometers and microscopes. Its ability to efficiently capture high-resolution images while minimizing noise makes it invaluable in these areas.

    What Sets CCD Apart? A Legacy of Reliability

    • CCD sensors excel in capturing a high dynamic range, meaning they handle light and dark contrast beautifully.
    • Their pixel uniformity ensures that images are sharp and free from inconsistencies, even in low-light conditions.
    • While newer technologies like CMOS have emerged, CCD remains the gold standard in applications that demand pristine image quality, such as scientific research and satellite imagery.

    Beyond Technology: Other Fields That Use CCD

    When you hear “CCD,” your mind might jump straight to technology, cameras, or those clever little image sensors that deliver those stunning HD pictures. But did you know that CCD isn’t limited to tech alone? That’s right! The world of CCD extends far beyond pixels and screens, making its presence felt in some unexpected fields. Let’s dive into these fascinating applications!

     CCD in Scientific Research

    Think back to that crisp Hubble Space Telescope image of a distant galaxy or the latest discovery about a far-off star system. Odds are, a CCD had a major role in capturing those mind-blowing visuals! In astronomy, CCDs are essential tools. Telescopes equipped with CCD sensors help scientists capture faint light from stars, galaxies, and other celestial objects billions of light years away. Astronomers rely on them to collect clean, precise data that simply wasn’t possible with older film technology.

    But the wonders don’t stop there. CCD imaging is also a staple in fields like biology, chemistry, and materials science. For instance, in microscopy, CCD cameras capture magnified images of tiny cells or chemical reactions in exquisite detail, helping researchers unlock the secrets of the microscopic world.

    CCD’s Role in Medicine

    Yes, even doctors and medical researchers are part of the CCD fan club! In medical imaging, CCD technology powers tools like digital X-rays, endoscopes, and other diagnostic equipment. These systems rely on CCDs to produce accurate, high-quality images of our bodies for diagnosis and treatment planning. Bonus points: CCDs are highly efficient and reduce patient exposure to radiation compared to traditional film X-rays!

    And let’s not overlook pathology. When analyzing tissue samples, scanners equipped with CCD arrays enable the magnification of slides, allowing doctors to detect diseases or abnormalities that the naked eye might miss.

    CCD in Art Preservation and Archiving

    The art world may seem like an odd place for CCDs to shine, but they do! Museums, libraries, and archives use CCD sensors to digitally preserve priceless artifacts, manuscripts, and artwork. These sensors, with their sharp resolution and ability to capture minute details, ensure every brushstroke on a painting or tiny detail in a thousand-year-old manuscript is faithfully recorded.

    This application is especially vital for fragile or deteriorating pieces that need to be protected from handling. With CCD imaging, these cultural treasures can be studied and admired without further wear and tear on the originals.

    National Defense and Security

    The high precision of CCDs has even found applications in defense and security. For example, surveillance systems often employ CCD-based cameras for clear, high-resolution imaging. Whether monitoring borders or securing sensitive areas, these cameras help ensure safety and security.

    On the defense front, CCDs are sometimes utilized in advanced optics systems in aircraft, satellites, and reconnaissance. Their ability to handle extreme conditions and capture reliable data makes them a dependable tool in this high-stakes field.

    Comparing CCD to Similar Technologies: Key Differences

    When it comes to technology, particularly in areas like imaging and sensors, there’s often a confusing array of options to choose from. One of the most enduring debates in this realm is how Charge-Coupled Devices (CCD) stack up against other similar technologies. Let’s break it all down, so you can gain a clearer picture of how CCD stands out!

    CCD vs CMOS: The Big Debate

    The most common comparison you’ll hear is CCD versus CMOS (Complementary Metal-Oxide-Semiconductor), as both are widely used in digital imaging. While they serve the same purpose—capturing light and converting it into electrical signals—there are some key differences in how they operate:

    • CCD technology: CCD sensors use a single pathway to transfer pixel data, much like a conveyor belt. This leads to uniformity, as each pixel is processed the same way, resulting in higher image quality and minimal noise. It’s why professional-grade cameras and space telescopes often use CCD sensors.
    • CMOS technology: CMOS sensors use individual transistors at each pixel to process data. This allows for on-chip processing, which is faster and more cost-effective, making CMOS a popular choice for smartphones and consumer-grade cameras.

    So, which is better? It really depends on the application. CCD shines in scenarios where image quality and accuracy matter most—think scientific research, filmmaking, or astronomy. CMOS, on the other hand, wins in everyday devices where speed, cost, and power efficiency are priorities.

    CCD vs Film: The Analog vs Digital Dilemma

    While modern imaging is dominated by digital technologies, traditional film still holds a place in the hearts of many enthusiasts. How does CCD compare to good old-fashioned film?

    1. Digital convenience: With CCD sensors, you can instantly review your photos or data, a stark contrast to the wait-and-develop process of film photography.
    2. Precision: CCD captures more fine-tuned details and is less prone to degradation over time. On the other hand, film quality can fade with improper storage.
    3. Nostalgia factor: Let’s not underestimate the charm of film! While CCD might deliver outstanding digital results, film offers an aesthetic quality that feels raw and authentic.

    The verdict? It’s less a question of one being better than the other and more about the purpose. CCD is logical for modern convenience and precision, while film remains a beautiful choice for artistry and tradition.

    CCD vs Infrared and Other Sensor Types

    CCDs are often compared to other types of sensors, such as infrared scanners or LiDAR (Light Detection and Ranging). These technologies aren’t directly interchangeable but are designed for specific kinds of data collection:

    • Infrared sensors: These excel at detecting heat signatures or motion, making them ideal for thermal imaging, night vision, or weather forecasting.
    • LiDAR: This technology is widely used in self-driving cars and mapping tools, offering 3D imaging capabilities that are beyond the scope of CCDs.

    What gives CCD an edge here? It’s their superior ability to capture high-resolution, broad-spectrum light images with extraordinary clarity. However, in situations like heat detection or depth-mapping, specialized sensors like infrared or LiDAR simply perform better.

    Everyday Impacts of CCD: How It Affects Regular Life

    Let’s talk about something fascinating — how CCD (Charged-Coupled Device) technology is quietly working behind the scenes to make your daily life better! You might not realize it, but CCDs are everywhere, playing a role in amazing ways without grabbing the spotlight. It’s the unsung hero of the tech world, and today, we’ll uncover its influence in simple, relatable terms.

    Your Photographic Memories

    Think about your favorite photographs — of your last vacation, a family reunion, or even the breathtaking night sky. Ever wonder how cameras, especially older digital ones, capture those incredible details and vibrant colors? That’s CCD technology at work. CCDs are responsible for converting light into electronic signals, enabling cameras to capture crisp, stunningly detailed images. While newer CMOS sensors are more widely used now, CCDs remain cherished in industries that demand top-notch image quality, like medical imaging or professional astronomy cameras. Without CCD advancements, our ability to freeze precious memories might have looked far different!

    Medical Diagnostics: A Better Look Inside

    When was the last time you heard about medical imaging? Whether it’s a scan for diagnosing issues or even dental X-rays, CCD technology plays a vital role here. Its precise imaging capabilities make sure doctors get clear, sharp visuals to make accurate diagnoses. From detecting cavities to spotting intricate internal issues, CCD technology helps keep us healthy by allowing us to see what’s otherwise invisible to the naked eye.

    Stargazing, Enhanced

    Have you ever gazed up at the stars and marveled at the enormity of the universe? CCD plays a major role in astrophotography and space exploration. Astronomers use CCDs in telescopes to capture faint light from distant stars, galaxies, and nebulas. This has led to incredible discoveries and jaw-dropping images of our universe. If you enjoy space documentaries with dazzling visuals, you can thank CCD for those extraordinary details!

    E-commerce and Barcodes

    Ordering groceries or scanning a barcode at the store checkout might seem mundane, but it’s part of the CCD symphony too. Barcode scanners and certain inventory-tracking systems integrate CCD sensors to streamline processes with speed and accuracy. Next time you shop online or breeze through a checkout line, remember the behind-the-scenes tech making it all seamless.

     Entertainment at Your Fingertips

    Ever used a scanner to digitize old photos or played with toys that react to light and motion? Those gadgets often use CCD technology to detect and respond to changes in light. While perhaps a less obvious example, such applications show CCD’s versatility even in entertainment and leisure products that enrich our lives.

    Why Should This Matter To You?

    At the heart of it, CCD technology makes our everyday experiences richer, sharper, and more connected. From capturing life’s memorable moments to advancing science and healthcare, CCD quietly powers tools that create meaningful impacts. Understanding the role of CCD in our lives isn’t just about appreciating technology — it’s about recognizing how innovation improves the way we live and interact with the world.

  • What is a ledger balance

    What is a ledger balance

    Let’s start with a simple yet essential question: what exactly is a ledger balance? Picture it as the official snapshot of all the money sitting in your bank account at the end of a working day. Think of it as a record that tells the story of your deposits, withdrawals, and transfers—essentially, every financial move you’ve made up to that point. It’s almost like the diary of your account, meticulously tracking all its activities in one tidy total.

    First things first, your ledger balance is like your account’s “official record”. Picture it as a snapshot of all your completed financial activity. It includes everything that’s already cleared and finalized – deposits, withdrawals, bill payments, and transfers. Essentially, it tells you how much money you officially have in your account as of the end of the previous business day.

    But what makes the ledger balance so special? Well, it’s your account’s starting point each morning. When your bank opens its doors (either physically or digitally), your ledger balance is already set in stone. This means it doesn’t change throughout the day, even if you go on a bit of a shopping spree or see deposits rolling in. Pretty cool, right? It gives both you and your bank a fixed point of reference for managing funds effectively.

    Why Should You Care About It?

    Understanding your ledger balance isn’t just about banking jargon—it’s about empowering yourself to make confident financial decisions. Let’s break it down with an example: have you ever swiped your card, only to wonder why the payment went through even though your “available balance” looked lower? That’s where knowing your ledger balance can really come in handy.

    Because the ledger balance is calculated at the end of the previous banking day, it doesn’t account for pending transactions like those fancy sneakers you just purchased or the paycheck that’s just about to clear. While this number might not represent every single penny currently in play, it gives you a grounded perspective on the steady money you can rely on—transactions fully processed by the bank.

    How Ledger Balance Differs from Available Balance

    So, here’s the deal – if you’ve ever peeked into your bank account and scratched your head wondering why there are two different numbers staring back at you, you’re not alone. Those figures are ledger balance and available balance, and yes, they are not the same thing. Don’t worry – we’re here to clear up the confusion for good. Let’s dive into what sets them apart!

    What is the Ledger Balance?

    First things first, your ledger balance is like your account’s “official record”. Picture it as a snapshot of all your completed financial activity. It includes everything that’s already cleared and finalized – deposits, withdrawals, bill payments, and transfers. Essentially, it tells you how much money you officially have in your account as of the end of the previous business day. It’s like the permanent record of your account – no surprises, just an accurate log of finalized transactions.

    What About the Available Balance?

    Your available balance, on the other hand, is more of a real-time number. It reflects how much money you can actually use or withdraw at any given moment. The key difference? It takes into account pending transactions that haven’t officially cleared yet. For example:

    • If you’ve swiped your debit card at a restaurant, the amount you spent is subtracted from your available balance (even before the transaction is fully processed).
    • If you deposited a check, your available balance might not immediately reflect the full amount, depending on your bank’s hold policies.

    In short, the available balance is fluid, shifting as your pending transactions come and go, while the ledger balance shows a more static view of your account based on completed transactions.

    Why Does This Difference Matter?

    You might be wondering – why should I even care about these two balances? Isn’t one number good enough? Well, not quite. Knowing the difference can save you from some serious financial headaches.

    1. Avoiding Overdraft Fees: If you’re looking at your ledger balance and making spending decisions, you could accidentally overdraft your account if there are pending transactions you forgot about. Always check your available balance before making any big withdrawals or purchases!
    2. Managing Pending Transactions: Understanding that your available balance factors in pending charges helps you track how much money you truly have at your disposal – no guessing needed.
    3. Reconciling Accounts: If you’re someone who keeps meticulous financial records, the ledger balance is what you’d use to cross-check your account’s statement for accuracy.

    A Simple Tip to Keep in Mind

    Here’s a pro tip: If your bank’s app or website shows both balances, always prioritize your available balance when deciding whether you can afford to spend more. But if you’re trying to reconcile your transactions or review historical activity, that’s when your ledger balance becomes the hero of the story.

    The Role of Ledger Balance in Daily Transactions

    When it comes to managing your money, understanding your ledger balance is key. But what exactly does this balance mean in the flow of your daily financial activities? Let’s dive into how your ledger balance plays a crucial role in your everyday transactions and why it’s essential to keep it in mind when managing your finances. In today’s digital age, partnering with a finance app development company can help individuals and businesses track ledger balances in real time, offering tools and insights that simplify money management and enhance financial decision-making.

    What Does the Ledger Balance Really Tell You?

    Simply put, the ledger balance is the amount of money in your bank account at the end of any banking day, after all the transactions, deposits, withdrawals, and transfers have been fully processed. Think of it as a snapshot — a record of where you stand financially once the dust has settled after a busy day of financial activity.

    This balance is important because it reflects your actual account position based on cleared funds. It helps you get a sense of how much money you truly have and can act as a reliable anchor when planning your expenditures.

    How It Fits into Your Everyday Spending

    Let’s paint a picture. Say it’s morning, and you’ve grabbed coffee on your way to work, paid for lunch, and maybe treated yourself to some online shopping. You might be looking at your available balance, thinking you have enough money left. However, not all of these transactions may have cleared yet with your bank. This is where the ledger balance acts as your guidepost, showing the finalized snapshot of your account after cleared deposits and withdrawals.

    • Planned vs Actual Spending: Your ledger balance ensures you know the real status of your account, helping you avoid overspending or overdraft fees.
    • Budgeting Accuracy: When you rely on your ledger balance rather than just your available balance, you can be more precise with your budgets and spending plans.
    • A Foundation for Financial Health: By monitoring your ledger balance regularly, you develop a habit of financial awareness — a critical skill for maintaining stability.

    Why It Shouldn’t Be Ignored

    Your ledger balance is not just a “number” — it holds power over whether your bills are paid and how smoothly your life operates financially. Ever wonder why a payment might bounce even though your app displayed a sufficient available balance? The culprit could be a delay in processing transactions or unposted items still updating your ledger.

    For instance, while the available balance may tempt you into thinking you have more money, it often includes pending credits or transactions that haven’t actually gone through. Comparing this with your ledger balance before committing to large purchases can save you from unexpected surprises.

    Breaking Down the Components of a Ledger Balance

    Ah, the ledger balance—an essential yet often misunderstood component of financial literacy. If you’ve ever looked at your bank statement or navigated your online banking portal, you’ve likely come across this term. But what exactly makes up a ledger balance, and why should you care? Let’s dive into the nuts and bolts of it, step by step, together!

    What Is a Ledger Balance Made Of?

    The ledger balance, in the simplest terms, is the total amount of money available in your bank account at the close of the previous business day. Picture it as the starting point for your account each morning. Unlike running balances, which fluctuate throughout the day, the ledger balance remains steadfast as a snapshot of your account’s history. But what sits beneath this number? Here’s what contributes to it:

    • Deposits: Any money you or someone else has transferred into your account before the end of the prior business day. This could include paycheck direct deposits, transfers between accounts, or even cash deposits.
    • Cleared Transactions: All transactions, like debit card purchases, checks, or electronic payments, that have officially been processed by the bank. If a transaction is still pending, it won’t affect your ledger balance.
    • Bank Fees: Any monthly maintenance charges, overdraft fees, or other deductions that the bank has processed during the prior business day. Yes, those annoying fees do count here!

    The ledger balance isn’t just some arbitrary figure—it’s a reflection of all the confirmed activity in your account. Think of it as the accountant’s neatly wrapped summary of where your account stood as of last night.

    Understanding What the Ledger Balance Isn’t

    It’s just as important to understand what your ledger balance doesn’t include as it is to know what it does. The key distinction here is timing. The ledger balance doesn’t reflect real-time activity. So, if you’ve made transactions today—such as buying your morning coffee with a debit card or transferring money to a friend—they won’t yet be part of your ledger balance until they clear. This brings us to the next point…

    Why Pending/Uncleared Transactions Aren’t Included

    When you swipe your card or initiate a transaction, it doesn’t immediately shift money out of—or into—your ledger balance. These transactions are typically listed as “pending” until they’re finalized, which can take anywhere from a few hours to a couple of business days. Meanwhile, your ledger balance holds steady, blissfully unaware of the activity yet to come. It’s why you might feel “rich” when your account shows your standard ledger balance, but your “available balance” tells a different story (we’ll leave that discussion for another section!).

    How Financial Stability Relies on the Ledger Balance

    Your ledger balance is the bedrock of financial accountability. By tracking it consistently, you can maintain a clear picture of what funds you’re working with—without the confusion of pending transactions muddying the water. While it might not actively reflect today’s spending, it helps you strategize, providing insights into confirmed deposits and withdrawals.

    The Importance of Timing in Reflecting Ledger Balance

    Let’s talk timing. Yes, it’s everything – in life, relationships, and yes, even with your ledger balance. Curious why timing plays such a vital role in determining what your ledger balance looks like at any moment? Let’s unpack this in a simple, conversational way that’s easy to follow.

    Timing: The Unsung Hero of Ledger Updates

    Think of your ledger balance as a snapshot of your financial activity. It records all transactions that have officially posted to your account. However, and here’s the kicker, timing affects how quickly certain transactions show up on this snapshot. Ever checked your balance right after making a credit card purchase and noticed it hasn’t updated? That’s because your ledger balance doesn’t reflect real-time changes.

    Here’s the gist: payments, deposits, and transfers can take some time to process fully. A deposit you made at 7 p.m. on a Friday might not show as cleared in your ledger balance until Monday morning at 9 a.m. Why? Timing. Financial institutions often work around business hours, weekends, and banking holidays, which means there’s usually a delay before activities are confirmed in the ledger.

    Key Moments Timing Impacts Your Ledger Balance

    If you’ve ever wondered, “Why does my balance seem off?” it’s likely connected to the timing of your recent transactions. Let’s explore a few scenarios:

    • Pending Transactions: These don’t immediately hit your account. Your ledger balance ignores anything not officially posted, so the seemingly missing transaction is just waiting in the wings to settle.
    • Direct Deposits: Ever noticed that direct deposits sometimes show up sooner than expected? That’s because employers or financial institutions may schedule them earlier than the “official” pay date. Timing here can work in your favor!
    • Holidays and Weekends: Transactions initiated on a holiday or over the weekend can sit in limbo and won’t reflect in your ledger balance until the next business day.

    Why You Should Care About This

    Understanding these timing quirks isn’t just trivia; it helps you manage your money smarter. Here’s why:

    1. Avoid accidental overspending: If you solely rely on your ledger balance and forget a pending payment, you might think you have more money than you actually do. Timing awareness can help you maintain better control.
    2. Plan ahead: Knowing when deposits and withdrawals are likely to reflect adds a layer of predictability to your financial management.
    3. Prevent fees: Since insufficient funds fees often stem from misunderstanding your ledger versus actual available balance, keeping timing top of mind can save you unnecessary stress.

    Pro-Tip: Use Alerts and Apps

    Most banks and financial institutions these days offer features like transaction alerts and mobile apps to give you a clearer, more immediate picture of your finances. Turn on notifications to stay updated when payments post or deposits clear. It’s one small step toward mastering timing and staying on top of your ledger balance.

    Common Scenarios That Impact Ledger Balances

    Hello there! Let’s dive into a topic that might sound a little technical at first but is surprisingly relatable once you break it down—common scenarios that can affect your ledger balance. No need to bring a financial dictionary; I’ll explain it in simple and straightforward terms!

    What Is a Ledger Balance, Anyway?

    Before we jump into the scenarios, here’s a quick refresher—it’s always good to have context. A ledger balance represents the total amount of money in your bank account at the end of the previous business day. Think of it as the bank’s official record of your funds. This balance doesn’t reflect immediate changes, like checks that haven’t cleared or pending card transactions, but instead shows your account as it stood at that freeze-frame moment.

    Scenario 1: Automated Payments and Pending Transactions

    The most common situation that can make your ledger balance differ slightly from what you “feel” like you have in your account is when pending transactions occur. For example:

    • You’ve decided to pay your streaming subscription, and the payment’s been scheduled, but it hasn’t been deducted officially yet from your account.
    • This means your ledger balance (from the previous day) may not yet reflect that money moving out, although it’s on hold behind the scenes.

    This is a normal part of how banks operate, but it’s important to keep an eye on these pending payments to avoid accidentally overspending.

    Scenario 2: Deposits That Are Still Processing

    Have you ever deposited a paycheck or transferred money into your account and wondered why it hasn’t shown up immediately? This can impact your ledger balance because deposits often require a processing period to clear. While the funds may show up as pending or even reflected in your available balance, they won’t update your ledger balance until the bank has fully cleared them. Timing, as they say, is everything!

    Scenario 3: Overdraft Protection in Action

    Here’s another big one: if you have overdraft protection, some banks temporarily debit the necessary amount to cover an overdraft and adjust your balances. This can affect your ledger balance post-transaction, potentially creating a mismatch in what you expected versus what’s been updated. Kudos if you use overdraft sparingly—it’s a great safety net but not one you want to rely on too often!

    Scenario 4: Holiday and Weekend Delays

    Ever notice that things tend to move a bit slower on weekends or holidays? If a financial transaction is initiated during these periods, it might not officially reflect on your ledger balance until the next business day. This is just how traditional banking schedules work, even in our fast-moving, digital-first world.

    Scenario 5: Bank Fees or Service Charges

    Ouch, it’s easy to forget about those sneaky fees, isn’t it? Banks sometimes deduct maintenance fees, overdraft charges, or ATM service charges directly from your account. These charges can unexpectedly lower your ledger balance. Pro tip: regularly review your bank’s fee schedule so those little deductions don’t catch you off guard.

    Practical Insights for Managing and Using Your Ledger Balance

    Let’s dive into some handy and practical tips that will help you better manage and utilize your ledger balance. This doesn’t have to feel like Rocket Science 101—we promise to keep it simple, relatable, and beneficial. After all, your ledger balance is a key player in your personal or business finances. Understanding how to effectively manage it makes all the difference, especially when working with professional services such as accountants or financial advisors who rely on accurate ledger balances for planning and compliance.

    Stay Informed About Your Ledger Balance

    Your ledger balance is essentially the snapshot of your bank account balance as of the end of the previous business day. While it might seem static, understanding how it behaves is vital when managing your finances. Stay on top of your balance by regularly checking it, either through your bank’s online portal, mobile app, or statements. This helps you monitor cash flow and avoid surprises.

    Plan Your Spending Around Your Ledger Balance

    One pro tip for those eager to keep their finances in check is learning to plan your spending based on the ledger balance rather than the available balance. Why? Because the ledger balance reflects transactions that have been cleared and finalized by the bank, meaning it’s a more reliable figure. Relying solely on available balance, which includes pending or temporary holds, could lead to overspending if those pending amounts later get deducted.

    Understand the Delays in Updates

    It’s worth noting that not all transactions immediately appear in your ledger balance. For example, suppose you swipe your card on a Friday evening—this might not show up until Monday! Knowing this, you can avoid the trap of thinking you have more funds available than you actually do. A simple habit of keeping receipts or maintaining a running personal ledger alongside your bank statements can help.

    Keep a Buffer for Safety

    Another piece of advice for managing your ledger balance effectively is maintaining a buffer. Emergencies happen, and sometimes unexpected fees or forgotten transactions can impact your balance. Keeping a little extra cushion ensures that even if an unforeseen deduction occurs, you remain in the safe zone and can steer clear of overdraft fees or returned payments.

    Sync Personal Tracking With Your Ledger Balance

    If you’re someone who uses personal finance apps or spreadsheets, ensure your records align with your ledger balance. This habit improves accuracy and highlights discrepancies early. When in doubt, trust your bank ledger but also investigate unmatched transactions—it could mark the difference between catching a financial error or letting it persist.

    Common Mistakes to Avoid

    While managing your ledger balance is straightforward, there are some common pitfalls individuals can face. Here’s what to steer clear of:

    • Over-relying on available balance: Remember, this figure can fluctuate with pending transactions.
    • Ignoring small deductions: Even minor fees or small purchases can add up and affect your overall balance.
    • Forgetting about unpaid checks or automatic payments: These can blindside you if not accounted for.
  • What is a good miles per gallon

    What is a good miles per gallon

    When it comes to buying a car or even just comparing vehicles, one term that pops up over and over is miles per gallon (MPG). But what exactly does MPG mean, and why is it so important? Let’s break it down into clear, simple terms so you can feel confident next time this number comes up in conversation—or at the dealership.

    At its core, MPG is a measure of how far a vehicle can travel on a single gallon of fuel. Think of it as the car’s energy efficiency rating. The higher the number, the more miles you can squeeze out of each gallon of gas, which means more savings for your wallet and generally fewer trips to the gas station—a win-win, right?

    City vs. Highway MPG

    One thing that confuses many people when looking at MPG ratings is that you’ll usually see two numbers: one for city driving and another for highway driving. Here’s the key difference:

    • City MPG: This number reflects stop-and-go driving, like when you’re stuck in traffic or navigating busy streets with frequent stoplights. Your car’s fuel efficiency tends to drop in these situations because constant stopping and acceleration uses more energy.
    • Highway MPG: This number takes into account steady driving on open roads, where the engine can maintain a more consistent speed. Naturally, almost every car performs better on the highway than in city conditions. This is why highway MPG is usually higher than city MPG.

    When comparing vehicles, it’s important to consider how and where you’ll be driving most often. For example, if you’re mainly commuting in crowded urban areas, city MPG will matter more to you than the highway rating.

    What does bi weekly pay mean: Read More.

    How Is MPG Calculated?

    In case you’ve wondered, car manufacturers don’t just pull MPG numbers out of thin air—they’re calculated through standardized testing. In the U.S., the Environmental Protection Agency (EPA) oversees this process. Vehicles are tested in controlled conditions that simulate city and highway driving to give potential buyers a sense of the car’s fuel efficiency. While these numbers are a great starting point, it’s worth noting that real-world MPG can vary depending on driving habits, road conditions, and even weather.

    Fuel Efficiency Standards: What Do They Tell Us?

    Have you ever wondered what fuel efficiency standards actually mean, or how they influence the vehicles we buy? Let’s explore this fascinating topic together, because understanding these standards can give us a better appreciation of what goes into achieving that “miles per gallon” (MPG) number on your car window sticker.

    What Are Fuel Efficiency Standards?

    Fuel efficiency standards exist to keep automakers accountable and ensure their vehicles meet certain environmental and performance thresholds. These regulations require manufacturers to design vehicles that strike a balance between fuel economy and emissions reductions, while maintaining practical capabilities like speed and cargo capacity.

    In the United States, the Corporate Average Fuel Economy (CAFE) standards play a key role. Established in 1975 as a response to the oil embargo, these rules aim to reduce fuel consumption and improve overall energy security. Globally, different regions have their own versions, like the European CO2 emissions targets or Japan’s fuel efficiency requirements. Despite regional variations, the shared goal is to create vehicles that burn less fuel for a longer road trip while being friendlier to the planet.

    Why Do These Standards Matter to You?

    It all boils down to two major things: saving money at the pump and cutting carbon emissions. Vehicles that meet or exceed these standards tend to be more fuel-efficient, meaning you’ll spend less on gasoline over the life of your car. Additionally, because they emit fewer greenhouse gases, they also contribute to slowing climate change.

    In essence, these standards set the stage for innovation. Automakers are inspired (or pressured, depending on your perspective!) to build better cars with advanced technology, such as turbocharged engines, lightweight materials, and streamlined aerodynamics—all focused on improving MPGs without sacrificing performance.

    The Numbers Behind the Standards

    Have you noticed modern cars achieving higher MPG figures compared to those from a few decades back? You can thank fuel efficiency regulations for that. For instance, under recent CAFE standards, manufacturers are required to achieve an average fleetwide fuel economy of about 49 MPG by 2026. Achieving this isn’t easy, so manufacturers are leveraging hybrid engines, electric vehicles (EVs), and other green tech to close the gap.

    How Do They Affect Your Car Choices?

    When shopping for a car, understanding these standards can help you make informed decisions. Cars that align with stricter regulations will often perform better in terms of fuel economy and emissions. These will be the vehicles that allow you to travel farther while using less fuel—a win-win for your wallet and the environment.

    So, if you’re torn between two vehicles, take a closer look at their MPG ratings and emissions certifications. Dig a little deeper into how these cars compare against the official standard benchmarks. Being proactive will ensure you get a vehicle that matches your priorities, whether that’s saving money, reducing emissions, or both.

    Gasoline vs Hybrid vs Electric: How MPG Varies

    When it comes to figuring out what “good” miles per gallon (MPG) means, it’s important to understand how different types of vehicles measure up. Gasoline-powered cars, hybrids, and electric vehicles (EVs) all bring something unique to the table when it comes to efficiency. Let’s break it all down so you can compare your options and find the right fit for your driving needs.

    Gasoline Cars: Tried and True, but with Limits

    Traditional gasoline-powered cars have been around for over a century, which means their MPG standards are well-established. For most compact and midsize cars, you can expect an average mpg in the range of 25 to 35 MPG for highway driving. Certain fuel-efficient models, like sedans with smaller engines, can push up to 40 MPG or even higher.

    However, larger SUVs and trucks tend to average much lower MPG — somewhere in the 15 to 25 MPG range. The bottom line? Gasoline cars can still be efficient, but they’re heavily influenced by the weight and design of the vehicle, as well as driving habits.

    Hybrids: The Best of Both Worlds

    Hybrids bridge the gap between gasoline and electric power, giving drivers significant improvements in fuel efficiency. Thanks to their ability to rely on batteries in addition to a gas engine, many hybrids achieve stellar MPG results. A popular hybrid, like the Toyota Prius, can deliver a combined mileage of 50 MPG or more. That’s a big leap compared to most gas-only models!

    Hybrids shine particularly in city driving due to their ability to operate on electric power at low speeds. Stop-and-go traffic doesn’t hit their MPG as hard as it does traditional gas cars. If you’re a driver who spends a lot of time commuting in urban areas, a hybrid could be a game-changer for your wallet.

    Electric Vehicles: MPG in a Whole New Light

    Wait a minute — do EVs even have MPG? Sort of! Since fully electric vehicles don’t use gasoline, their efficiency is measured in something called Miles Per Gallon Equivalent (MPGe). MPGe calculates how far an EV can travel on the energy equivalent of a gallon of gas.

    For most EVs, the MPGe can range from 100 to 140 or higher. Tesla’s Model 3, for example, boasts an MPGe of well over 130, depending on the version. One of the biggest advantages of EVs is that they completely eliminate the need for gas, making them far more efficient than standard cars. While the up-front cost of EVs is higher, they’re winners when it comes to low fuel costs — especially if you charge at home using renewable energy sources and an OCPP gateway.

    Evaluating Terrain and Driving Habits: Why They Matter

    When it comes to miles per gallon (MPG), the numbers on paper often look great, but reality has a funny way of complicating things. Did you know that your car’s MPG can fluctuate significantly depending on the terrain you drive on and how you drive? Let’s dive into how these factors can influence your fuel efficiency and what you can do to optimize it in everyday driving.

    Terrain: It’s Not All Flat Roads and Sunshine

    Not all miles are created equal, especially if you’re navigating hilly, mountainous, or stop-and-go city environments. Here’s how different types of terrain can impact your MPG:

    • Hilly and Mountainous Roads: Driving uphill forces your car to work harder, typically revving the engine and burning more fuel. Even with a fuel-efficient vehicle, expect lower MPG in these conditions. The upside? You’ll often regain some efficiency on descents thanks to gravity helping the car roll downhill. Many modern vehicles with regenerative braking (common in hybrids and EVs) can even recapture some energy!
    • Flat Highways: This is where most vehicles shine. Cruising at a consistent speed on flat terrain minimizes the engine’s workload. If you want to maximize your MPG, highway driving in these conditions is your best bet.
    • Urban Traffic: Stop-and-go city driving is notoriously hard on MPG. Constant braking, idling, and acceleration guzzle up fuel, making those EPA numbers seem like a distant dream. Pro tip: If you’re caught in heavy traffic, preserve fuel by turning off features like air conditioning and avoiding aggressive accelerations.

    Understanding the kind of terrain you encounter regularly can help you align expectations with reality. Plus, it gives you the chance to make small adjustments to improve efficiency.

    How Your Driving Habits Play a Key Role

    Your driving style isn’t just about how fast you get from point A to point B. It’s also a major factor in determining your MPG. Here are a few tips for habit tweaks that could make a real difference:

    1. Ease into the Gas Pedal: Rapid acceleration may feel fun, but it’s a fuel efficiency killer. Instead, accelerate gradually, especially in urban settings, to keep your MPG high.
    2. Brake Wisely: Frequent hard braking wastes the energy that could have been used to keep the car moving. Anticipate stops ahead and coast whenever possible.
    3. Don’t Idle Longer Than Necessary: If you’re parked and waiting, turn off the engine. Modern engines are designed to restart efficiently, and idling for long stretches burns unnecessary fuel.
    4. Watch Your Speed: Once you hit freeway speeds, resistance from wind and tires grows exponentially. Driving at 55 mph instead of 75 mph could significantly boost your MPG.
    5. Lighten Your Load: Carrying extra weight — think roof racks, heavy cargo, or stuffed trunk spaces — forces the engine to exert more effort. Travel light for better fuel economy.

    MPG Benchmarks for Different Vehicle Classes

    When it comes to understanding what qualifies as “good” miles per gallon (MPG), it’s important to note that not all vehicles are created equal. Different types of vehicles serve unique purposes, and naturally, their MPG benchmarks vary to align with their design and function. Let’s break it down into vehicle classes to paint a clearer picture.

    1. Compact Cars

    Compact cars are often the darling of the fuel-efficiency world. Though small in size, they pack a punch when it comes to MPG. Most modern compact cars offer an average of 30–40 MPG on the highway, with many hybrids exceeding that range. If you’re a city commuter looking to save big at the pump, a compact car is an excellent choice.

    2. Sedans

    Slightly larger and more powerful than compact cars, sedans still score well in the fuel-efficiency game. Standard sedans typically average around 20–30 MPG, but hybrids and plug-in hybrid sedans can climb much higher, sometimes reaching that magic 50+ MPG range. If you’re trying to balance space, comfort, and efficiency, a sedan often hits the sweet spot.

    3. SUVs

    Ah, SUVs: spacious, rugged, and versatile. But how do they measure up in the MPG department? Smaller, crossover-style SUVs can deliver 25–30 MPG, while full-size SUVs often range in the 15–25 MPG zone. Hybrids and electric SUVs are starting to make major improvements here, with some models pushing well beyond the 30 MPG threshold.

    Quick Tip: If SUV functionality is a must but you’re MPG-conscious, consider a hybrid SUV model — it’s an excellent way to balance performance with fuel savings.

    4. Trucks

    For those in need of serious power and towing capacity, trucks often prioritize performance over efficiency. Gas-powered trucks typically average around 15–20 MPG. Diesel trucks, while somewhat better, may climb closer to 20–25 MPG. That said, there’s been a steady push toward hybrid and electric options for trucks, offering new opportunities for drivers to enhance their efficiency without losing muscle.

    5. Luxury and High-Performance Cars

    Luxury and sports cars might turn heads, but they aren’t winning any MPG awards. The average conventional model in this category gets around 15–20 MPG. However, certain high-end brands are incorporating hybrid or even electric technologies to boost efficiency without compromising on power and prestige. If you’re eyeing something in this range, be prepared to see lower MPG numbers than more practical alternatives.

    6. Electric Vehicles (EVs)

    For EVs, we measure efficiency a bit differently, using “MPGe” (miles per gallon equivalent). While EVs don’t precisely have a gallon of fuel stored anywhere, MPGe gives you an idea of their energy efficiency compared to gas-powered cars. Many EVs achieve 100–120 MPGe or more, far surpassing traditional vehicles. If lowering your carbon footprint is a priority, EVs are hard to beat!

    Balancing MPG with Practical Needs: When Efficiency Isn’t Everything

    We all want that magical number on our car’s dashboard—the one that signifies stellar miles per gallon (MPG) and promises savings at the pump. But let’s face it: chasing the highest MPG isn’t always the wisest or most practical move. Life isn’t a numbers game; it’s about striking the right balance for your unique needs. Let’s dive into how you can weigh efficiency against practicality without pulling your hair out over decimal points.

     Not All Lifestyles Are Built for High MPG

    Are you someone who frequently hauls gardening supplies? Or maybe your large family requires a spacious SUV for those cross-country trips? The reality is, smaller, high-MPG cars like compact sedans or hybrids may not suit every lifestyle. Sometimes, you just need a vehicle that gets the job done, even if it drinks a little more fuel than you’d love. Remember: a car isn’t just a tool for saving gas money—it’s a tool for living your life.

    For example:

    • If you’re a contractor carrying heavy equipment, a pickup truck will outperform a hybrid hatchback any day, even if the MPG difference is significant.
    • Parents packing strollers, sports gear, and a week’s worth of groceries will appreciate the extra space in a minivan or midsize SUV instead of squeezing into a high-MPG compact.

    Ultimately, it’s not about always choosing the most fuel-efficient vehicle—it’s about choosing the one that fits your needs, while keeping MPG in mind as part of the equation.

    Time Versus MPG: Why Trade-Offs Are Okay

    Picture this: you’re heading out on a weekend road trip. You’ve got two choices—stick to the straight-shot highway route where your vehicle operates at peak efficiency, or wind through scenic routes and hilly terrain that might tank your MPG. Which do you choose? Taking the hit on your fuel economy for an unforgettable trip through gorgeous landscapes might be the better decision for your overall happiness.

    Additionally, certain practical decisions that boost convenience may impact efficiency short-term. Need to blast the A/C in a summer heatwave? Go for it. Stuck in city traffic, where stop-and-go driving drains efficiency? That’s just life. Don’t beat yourself up for prioritizing comfort and practicality in the moment.

    Specialized Needs and Non-MPG Benefits

    Thinking about your vehicle’s overall utility helps put MPG into perspective. Consider factors beyond fuel efficiency, like towing capacity, safety features, off-road capabilities, and even pet-friendliness. If you and your giant Great Dane love camping, a fuel-efficient compact sedan just won’t cut it. A larger vehicle, even with lower-than-ideal MPG, ensures your furry companion rides in comfort—and that you’re ready for rougher terrain.

    Is Higher Always Better? Finding the Sweet Spot

    When it comes to miles per gallon (MPG), it’s tempting to think that higher is always better. After all, who doesn’t want to save money on fuel and help the environment, right? But, like most things in life, there’s a balance to be struck. Let’s explore why more MPG isn’t always the universal answer and how to find the right fit for your needs.

    What Does MPG Actually Represent?

    First, let’s quickly recap: MPG measures how far a vehicle can travel on one gallon of fuel. A higher MPG means better fuel efficiency, which can save you money at the pump and reduce your carbon footprint. But there’s more to this equation than meets the eye, and chasing the highest MPG doesn’t always translate to a win for everyone.

    The Limits of Chasing ‘High MPG’

    While it seems logical to think “the more MPG, the better,” there are trade-offs involved. For one, vehicles that achieve extremely high MPG—such as some hybrids or electric vehicles (EVs)—are often compact or built with a specific purpose in mind. If you need a car for towing, transporting large families, or off-road adventures, then the ultra-efficient compact won’t meet your needs.

    On the flip side, opting for a vehicle with middling MPG because it’s more practical for your lifestyle can still be a sensible choice. The key is to weigh fuel efficiency against what you’ll actually use the car for. Essentially, the best MPG for you is one that balances long-term savings with functionality.

    How Far Can You Go with Efficiency?

    • Environmental Benefits: A higher MPG vehicle burns less fuel, which means lower emissions. If reducing your carbon footprint is a priority, going for a car with better efficiency is a win.
    • Savings at the Pump: The higher your MPG, the less often you’ll need to stop and refuel. However, the upfront cost of fuel-efficient vehicles (like hybrids or plug-in hybrids) can sometimes offset potential savings for drivers who don’t do a lot of mileage.
    • Performance Trade-offs: High-MPG vehicles often focus on efficiency, which can sometimes come with sacrifices like reduced engine power or limited load capacity.

    Practical Considerations: Your Sweet Spot

    Finding the “sweet spot” in MPG boils down to asking the right questions:

    1. What are your typical driving patterns? Long commutes or short trips? Highway or city driving?
    2. Do you frequently carry passengers, cargo, or both?
    3. How much are you willing to spend upfront for better fuel efficiency?
    4. Are environmental concerns a top priority for you?

    Consider a scenario: If you drive a lot, but mostly on long highways, you might want to look for vehicles with strong city- and highway-MPG ratings. On the other hand, if you’re just zipping around town, the absolute highest MPG isn’t likely to make as much of a difference compared to having the flexibility and comfort you need.

  • What is an asset account

    What is an asset account

    Before diving deep into the world of asset accounts, it’s important to start at the root: what exactly are they, and why should you care? Let’s unpack this in straightforward terms. Asset accounts are essentially the backbone of any financial system, capturing all the resources a business or individual owns that have value. Think of them as the financial “inventory” of what you own, ranging from cash in the bank to properties and equipment.

    To understand asset accounts at their core, it’s helpful to think of them as categorized records that help track and manage these resources. At the most basic level, they answer a simple question: “What do I own?” But here’s the twist — it’s not just about what you physically see and touch. Assets also include things like receivables (money owed to you) and intangible assets like patents.

    Why Asset Accounts Matter

    If you’re someone who tends to gloss over accounting terms thinking they sound too complex or irrelevant, let this sink in: good financial decisions are impossible to make without knowing what you have. Imagine planning a vacation but having no clue how much money you’ve saved—asset accounts are the tool that helps avoid that chaotic uncertainty.

    • Clarity: Asset accounts provide financial transparency, whether for business operations or personal management. You’ll know exactly what’s in your “financial toolbox.”
    • Decision-making: From deciding on investments to calculating risks, understanding these accounts allows you to make calculated, confident moves.
    • Compliance: Many financial regulations and processes, such as tax filings, specifically require accurate representation of assets.

    In short, if financial stability is your goal, building a strong understanding of asset accounts is where it all starts.

    Breaking It Down: Tangible vs. Intangible Assets

    An important concept to grasp early on is that not all assets are created equal. In fact, asset accounts are generally broken down into two major categories:

    1. Tangible Assets: These include physical and easily identifiable things like machinery, real estate, and even inventory. For example, the laptop you’re using to read this could count as a tangible asset in a business setting!
    2. Intangible Assets: These are less “visible” but no less important. Think copyrights, trademarks, patents, or brand value. They may not be as straightforward to measure, but they can be game-changers for businesses.

    Understanding the distinction isn’t just academic; it plays a real-world role in bookkeeping and tracking. Policies for depreciation, valuation, or even selling these assets often differ depending on their nature.

    The Double-Edged Sword of “Value”

    Here’s an interesting quirk about assets: their value can change over time. A brand-new car, for instance, is worth less the moment you drive it off the lot (thanks, depreciation). On the other hand, a well-maintained vintage car might gain value over the years. Asset accounts help track these changes so that your financial snapshot stays accurate and relevant.

    Pro Tip: Always double-check how market conditions or organizational decisions impact the value of your assets. It’ll save you headaches — and potentially money — down the road!

    Types of Asset Accounts and Why They Matter

    Asset accounts are the backbone of financial tracking. They aren’t just numbers in a ledger—these accounts breathe life into your financial story. Whether you’re a business owner, a budding accountant, or simply someone trying to better understand their personal finances, knowing the types of asset accounts and their significance can give you a real edge.

    What Are Asset Accounts?

    Before diving into the types, let’s start simple. An asset account is essentially anything you own that has value. Think of it as your company or personal “treasure chest.” From the cash in your bank to that shiny piece of equipment, all these are assets. Tracking them properly ensures you’re organized and fully aware of your financial standing. Now, let’s break down the magic behind the types of assets.

    Main Types of Asset Accounts

    There’s a wide variety of asset accounts out there, but they generally fall into two main categories: Current Assets and Non-Current Assets.

    1. Current Assets

    These are assets that you can easily convert into cash within a year. They’re your liquid warriors, ready to be used for day-to-day operations. Here’s what you’ll usually find under current assets:

    • Cash and Cash Equivalents: The most liquid asset of all. Think cash in hand, bank balances, or short-term investments that are as good as cash.
    • Accounts Receivable: Money owed to you by customers. If you’ve ever sold something on credit, this is where those amounts live.
    • Inventory: Products you’ve bought or made, just waiting to be sold.
    • Prepaid Expenses: Payments made in advance for things like insurance or rent. Technically, this is money you’ve already invested, giving you future value.

    2. Non-Current Assets

    These are the big-ticket items that offer long-term value. While they’re less liquid than current assets, they’re just as important in painting the full picture of your wealth. Here’s what typically falls under this category:

    • Property, Plant, and Equipment (PPE): Fancy accounting speak for your physical, long-term investments like buildings, machines, and vehicles.
    • Intangible Assets: Non-physical assets like patents, trademarks, and goodwill. They may not take up physical space, but their impact on your balance sheet is very real.
    • Long-Term Investments: Investments you plan to hold for years, like stocks or bonds that you don’t intend to cash out anytime soon.

    Why These Types Matter

    Understanding the various types of asset accounts isn’t just about checking boxes—it’s about staying in control. Not all assets are created equal. Some provide immediate financial relief (like cash), while others offer long-term benefits (like property). Knowing how to differentiate them allows you to:

    1. Make Better Budgeting Decisions: By knowing what’s liquid and what’s not, you can make smarter operational choices, avoiding nasty surprises like cash flow shortages.
    2. Improve Reporting Accuracy: Accurate reporting of current and non-current assets keeps your financial statements compliant while giving a clearer picture to stakeholders.
    3. Plan Strategically: Recognizing long-term assets helps you map out big-picture goals, whether it’s scaling your business or securing financial independence.

    A Fun Way to Remember the Types

    If all of this feels a bit abstract, try this analogy: Current assets are like snacks in your pantry—ready to be consumed or used right now. Non-current assets are the sturdy appliances like your oven or fridge—bigger investments that stick around for the long haul. Both are important, but they serve distinctly different purposes.

    The Role of Asset Accounts in Financial Statements

    Understanding the role of asset accounts in financial statements is essential for anyone looking to get a grip on their finances, whether you’re a business owner, accounting professional, or just someone keen to grow your financial literacy. Let’s dive into how these accounts connect the dots between financial transactions and the overall picture of a company’s value.

    Why Asset Accounts Matter in Financial Statements

    At their core, financial statements are designed to paint a clear picture of a company’s financial health. Asset accounts form one of the foundational building blocks of these documents. Assets represent everything a company owns that holds value—think physical items like equipment or intangible resources like patents.

    In financial statements, asset accounts appear in the balance sheet, listed under the broader category of total assets. They tell a story of what the company owns and how these resources contribute to its operations and ability to generate revenue. Without accurate and updated asset accounts, this story becomes incomplete—or worse, misleading.

    The Connection to the Balance Sheet

    The balance sheet is often referred to as the backbone of financial statements. It provides a snapshot of a company’s financial position at a specific point in time. Asset accounts are one of the three main components of the balance sheet, alongside liabilities and equity:

    • Assets: What the company owns (cash, inventory, property).
    • Liabilities: What the company owes (debts, loans, accounts payable).
    • Equity: The owners’ residual interest after debts are subtracted from assets.

    Assets are always displayed at the top of the balance sheet, and they’re categorized into current assets (those that can be converted into cash relatively quickly, like accounts receivable) and non-current assets (long-term investments, land, and machinery).

    Providing Financial Insights

    Thanks to accurate asset accounts, financial statements can answer critical questions, such as:

    • How liquid is the company? (i.e., how quickly can it turn its assets into cash to pay obligations?)
    • Does the company have sufficient resources to support its operations?
    • What is the company’s overall worth when liabilities are deducted from assets?

    These insights allow stakeholders—whether they’re investors, lenders, or management teams—to make informed decisions about the business. For instance, if a company’s current assets aren’t sufficient to cover its current liabilities, this could be a red flag for creditors. Similarly, investors looking for a profitable company will analyze the balance sheet to determine how effectively assets are being leveraged to generate returns.

    Accurate Tracking Is Non-Negotiable

    Think of asset accounts as the foundation of financial statements. If they’re inaccurate, the entire structure wobbles. For example:

    1. Incorrect Valuation of Assets: Overstating or understating the value of assets can distort financial reality. Imagine listing obsolete equipment at its full purchase price—this creates a misleading impression of the company’s worth.
    2. Overlooked Depreciation: Many non-current assets, like vehicles or machinery, lose value over time. Properly tracking depreciation ensures asset accounts reflect their true current worth.
    3. Missed Updates: Acquiring new assets or selling existing ones without updating records can throw off financial calculations.

    Practical Examples to Bring Asset Accounts to Life

    Let’s face it: financial concepts can feel a bit abstract until we see them in action. Asset accounts, while fundamental to understanding accounting, make way more sense when anchored in real-world examples. So, let’s explore some relatable scenarios that breathe life into these accounts. Whether you’re running a business or managing your personal finances, these examples will help you see the practical side of asset accounts.

    1. The Cash in Hand Example

    Picture this: You own a small bakery, and someone pays you $50 in cash for a batch of cupcakes. This money is immediately added to your “Cash” account, which is one type of asset account. Cash is considered the most liquid form of an asset because you can use it instantly to buy ingredients, pay employees, or even reinvest in your business. As simple as it sounds, tracking cash is critical for staying on top of your finances.

    Pro Tip: Always reconcile your cash account regularly. It’s surprisingly easy for numbers to get out of sync if you don’t stay on top of deposits and withdrawals!

    2. Accounts Receivable Example for Businesses

    Now let’s say you’re a freelance web designer and you just wrapped up a project for a client. You invoice them for $2,000, but payment hasn’t been received yet. This money isn’t in your pocket now, but it’s on its way. Here, you would record the amount in an “Accounts Receivable” asset account. It reflects money owed to you — a core asset that shows up on your balance sheet as a future benefit.

    Pro Tip: Regularly follow up on overdue payments. Letting those receivables sit too long not only affects cash flow but also creates unnecessary stress.

    3. Inventory in Action

    If you sell physical products, the inventory you own before selling them is another critical example of an asset account. Let’s say you run an online clothing store and currently have $10,000 worth of jeans, shirts, and jackets sitting in storage. This is categorized as inventory, a valuable current asset that contributes directly to your profit when the items are sold.

    Pro Tip: Don’t overstock inventory. While it increases your asset value, too much unsold stock can tie up cash or lead to waste if not managed well.

    4. Fixed Assets for Long-Term Investments

    Consider a small dental clinic that invests in a new X-ray machine costing $50,000. This is a perfect example of a fixed asset. While it doesn’t provide immediate cash flow, the X-ray machine is a long-term resource that helps the clinic run its operations and generate revenue over time.

    Pro Tip: Track the depreciation of fixed assets over time to ensure your records accurately reflect their current value.

    5. The Tech Startup and Intellectual Property

    For a tech startup, intangible assets like patents or trademarks can also fall into the asset account category. For instance, if your company develops software and secures a patent, you would record its value under an intangible assets account. Though these can’t be physically touched, they hold immense value by providing competitive advantages.

    Common Mistakes When Managing Asset Accounts

    Managing asset accounts isn’t rocket science, but it does require attention to detail and some good practices. Unfortunately, it’s all too easy to fall into traps that can lead to errors, misstatements, or even financial headaches. Don’t worry, though! Here, we’ll explore some common mistakes many people make when managing asset accounts, and I’ll show you how to avoid them like a pro.

    1. Failing to Regularly Reconcile Asset Accounts

    One of the most common mistakes in asset management is not reconciling accounts regularly. Think of reconciliation like balancing your checkbook, except on a business level. If you’re not routinely matching your records to actual balances (such as bank statements or physical asset inventories), discrepancies can spiral out of control.

    ✔ What to do instead: Set up a recurring schedule for reconciliation—monthly works well for most types of assets. Make it a habit to ensure what’s recorded matches what’s actually there.

    2. Misclassifying Assets

    Not all assets are created equal, but sometimes people treat them like they are. Misclassifying assets—like lumping short-term assets (cash or accounts receivable) together with long-term assets (like machinery or real estate)—can throw off financial reports and decision-making.

    ✔ What to do instead: Brush up on asset classifications and always double-check. Assets are typically divided into tangible vs. intangible, or current (liquid) vs. non-current (long-term). Keeping these categories straight will save you a headache later.

    3. Ignoring Depreciation (Or Getting It Wrong)

    This one’s a biggie! Fixed assets, like equipment and vehicles, lose value over time. If you’re not properly recording depreciation, your financial records won’t reflect the reality of your business’s worth or expenses. Worse, overstating asset values might lead to compliance issues during audits.

    ✔ What to do instead: Learn and apply appropriate depreciation methods (straight-line, declining balance, etc.) based on the asset type. Use accurate records of purchase dates and values to calculate depreciation with precision.

    4. Overlooking Obsolete or Missing Assets

    Ever forget an old item that’s no longer in use, but it’s still sitting in your records? That’s a surprisingly frequent pitfall. Holding on to assets that are obsolete, lost, or destroyed can inflate balances and distort financial ratios.

    ✔ What to do instead: Conduct regular inventory audits. If an asset is no longer useful or in possession, update your books and, if necessary, write it off.

    5. Failing to Maintain Adequate Documentation

    A tragic but avoidable mistake in asset management is a lack of proper documentation. Without invoices, receipts, and detailed descriptions, it’s hard to substantiate the value or ownership of an asset.

    ✔ What to do instead: Save everything! Digitize records where possible and store them securely. Good documentation makes reporting and audits far less stressful.

    6. Neglecting to Use Technology

    Many people still track their asset accounts manually, using spreadsheets or even paper records. While these methods can work, they’re vulnerable to human error. Plus, they lack the efficiency and accuracy of modern tools.

    ✔ What to do instead: Invest in reliable accounting software designed to handle asset management. This simplifies processes like tracking depreciation and reconciling accounts—saving you both time and energy.

    Software Solutions That Simplify Asset Account Management

    Managing asset accounts can sometimes feel like juggling spinning plates—there’s so much to track, from inventory and fixed assets to intangible assets like trademarks and patents. Thankfully, technology has come to the rescue with a variety of software tools that simplify asset account management. Let’s take a closer look at why these solutions can be a game-changer—and which features to keep an eye on when choosing the tool that’s right for you.

    Why Do You Need Software for Asset Account Management?

    Manually tracking assets, especially for growing businesses, can be a daunting task. The potential for errors, missed updates, or overlooked depreciation is high, and even modest mistakes can lead to costly financial discrepancies. Here’s how the right software can save the day:

    • Accuracy: Automation ensures fewer errors compared to manual entry, giving you reliable data every time.
    • Efficiency: Software streamlines time-consuming processes, allowing you to focus on more strategic tasks.
    • Organization: A centralized platform lets you keep all asset-related information—purchase dates, values, depreciation schedules—conveniently in one place.
    • Compliance: Many tools are designed to help you adhere to tax laws and financial reporting standards, thereby reducing your regulatory risks.

    Key Features to Look for in Asset Management Software

    Not all software solutions are created equal, so it’s important to choose the one that aligns with your needs. Here are the standout features to prioritize:

    1. Intuitive Interface: Nobody wants to spend weeks learning how to use overly complex software. Look for tools with user-friendly dashboards and simple navigation.
    2. Customizable Asset Categories: Whether you’re managing office equipment, buildings, or intellectual property, the software should let you create categories tailored to your business.
    3. Depreciation Tracking: Keeping tabs on depreciation can be tricky, but a good tool calculates it automatically and integrates it into financial reports.
    4. Cloud-Based Accessibility: A cloud solution lets you access and update data from anywhere, perfect for remote teams or businesses with multiple locations.
    5. Integrations: Look for tools that sync with your accounting software (such as QuickBooks or Xero) to ensure seamless financial reporting.
    6. Scalability: Is your business growing? Choose software that can grow with you, accommodating increased asset additions without breaking a sweat.

    Popular Tools You Might Consider

    Feeling overwhelmed by all the options? No problem! Here are a few popular and reliable software solutions to kick-start your search:

    • Asset Panda: A flexible, user-friendly solution well-suited for small to medium businesses. It offers customizable workflows and mobile app access.
    • FMIS Fixed Assets: Ideal for companies needing advanced functionality, such as support for complex depreciation methods and multi-currency accounting.
    • Sage Fixed Assets: A great choice for those needing robust fixed asset reporting and compliance capabilities.

    When and How to Update Asset Account Records

    Updating your asset account records might not be the most glamorous part of managing finances, but trust me, it’s an essential skill that can save you from future headaches. Let’s dive into when and how you should give your asset accounts the attention they rightfully deserve. Think of it like a health checkup—not always fun, but oh-so-important!

    The Key Moments to Update Asset Accounts

    First things first—let’s talk timing. Knowing when to update your asset accounts ensures they remain accurate and meaningful. Life changes fast, and your financial records should keep up. Here are moments when an update is absolutely necessary:

    • After major business transactions: Sold or bought new equipment? Made a big investment? These transactions directly impact your asset accounts, so they need to be reflected promptly.
    • At the end of a reporting period: Whether it’s monthly, quarterly, or annually, closing out a reporting period is your cue to review and adjust asset account records to prepare clean financial statements.
    • When there’s a change in asset value: Assets like property, vehicles, and inventory often appreciate or depreciate over time. Adjust your records to align with their current market value.
    • When conducting audits or preparing for them: During internal or external audits, accurate and up-to-date records are crucial for compliance and providing clarity into your financial health.
    • During mergers, acquisitions, or restructuring: Big changes to your organization often mean big changes to your asset structure. This is the perfect time to revisit and refine your asset records.

    Best Practices for Updating Asset Records

    So, how do you ensure your updates are smooth and headache-free? By following some tried-and-true best practices. Let’s break it down:

    1. Keep your documentation in order: Every update should be backed by proper paperwork—receipts, appraisals, or contracts. This helps verify changes and makes your updates defensible during audits.
    2. Separate fixed assets from current assets: When updating records, ensure that long-term assets (like buildings or vehicles) and short-term assets (like inventory or accounts receivable) are classified correctly. Trust me, this saves confusion later on!
    3. Use software for accuracy: If you’re manually updating spreadsheets, it’s time to consider accounting software. Software solutions can automate calculations, flag discrepancies, and maintain a clear record trail.
    4. Collaborate with your team: If your organization involves multiple departments, communicate changes across teams. For instance, finance, operations, and procurement should align closely to ensure all asset updates are properly captured.
    5. Adopt a proactive mindset: Don’t wait for big deadlines to roll around. Regularly review your asset accounts to ensure they’re always accurate, even mid-reporting period. A little diligence goes a long way!

    Why Regular Updates Matter

    Still not convinced? Updating your asset records isn’t just for compliance—it’s for clarity and confidence. Accurate records allow you to:

    • Make informed decisions: Whether you’re planning an expansion or cutting costs, having accurate asset data is the foundation of good financial decisions.
    • Reduce errors and discrepancies: Inaccurate or outdated records can lead to mistakes in financial statements, and no one wants to deal with that mess.
    • Enhance credibility: For businesses, precise asset records provide stakeholders with a clear picture of your financial integrity. This goes a long way in building trust.
  • What is ASO in settlement

    What is ASO in settlement

    Alright, let’s dive into the basics of ASO and why you should care about it. ASO, or Administrative Services Only, might sound like jargon at first, but once you get the hang of it, it’s actually pretty straightforward. Essentially, ASO is an arrangement where an organization outsources administrative tasks — think claims processing or payroll services — while keeping certain core functions in-house.

    Imagine you’re running a large organization. One of your key responsibilities is managing the settlement process, which can encompass everything from paying out claims to handling employee benefits. The larger and more complex your organization, the trickier it is to handle all these nitty-gritty details yourself. That’s where ASO teams come in — they handle the admin-heavy tasks so you don’t have to. It’s all about streamlining operations and letting the experts take the wheel on the paperwork.

    So, What Does ASO Really Cover?

    Great question! The beauty of ASO lies in its customizability. These services can be tailored based on what your organization needs most. Some common areas managed through ASO arrangements include:

    • Claims Administration: Processing claims for health insurance or other programs efficiently and accurately.
    • Compliance Handling: Ensuring your organization meets any legal and regulatory requirements.
    • Benefits Management: Overseeing employee benefits like medical plans, making sure they’re implemented without hiccups.
    • Reporting and Analytics: Offering detailed reports for smarter operational insights.

    Having a team that specializes in this stuff can not only help cut down on errors but also allow you and your team to focus on the big picture instead of drowning in administrative details.

    What is a good miles per gallon: Read More.

    Why Should You Care About ASO?

    Here’s why ASO really matters: It saves time, resources, and money, all while helping you stay agile. Say goodbye to the stress of overseeing piles of paperwork or ensuring compliance with tricky settlement-related laws — with ASO, that’s all handled for you.

    Let’s say your company has been recently expanding and you’re now juggling benefits for hundreds (okay, maybe thousands) of employees. Without ASO, you’d need a massive in-house team to sort through everything. But with ASO, you offload those tedious parts of the process to professionals who specialize in exactly this — and they’re backed by technology that makes the whole process seamless.

    How to Know If ASO Is Right for Your Business

    If your organization is dealing with complex administrative tasks or growing at a rate where paperwork and compliance are becoming unmanageable, ASO could be a game-changer. It’s ideal for medium to large companies that want to focus on strategic growth instead of sweating the day-to-day admin work.

    Here’s a pro tip: Before diving into an ASO arrangement, take stock of your company’s specific needs. What are the processes that are slowing you down? Which administrative tasks tend to be the biggest headache? Once you pin those down, you’re in a better position to choose an ASO solution that works for you.

    The Role of ASO in Simplifying Settlement Processes

    When it comes to settlement processes, things can get complicated quickly, right? Between managing claims, tracking payments, and ensuring compliance, it’s easy to feel overwhelmed. That’s where Administrative Services Only (ASO) comes into play, acting as a game-changer. Let’s dive into why ASO is like putting your settlement processes on cruise control.

    What Exactly Does ASO Do?

    ASO is a service where an external provider manages administrative responsibilities, such as claims processing, settlements, and paperwork, on behalf of your organization. But unlike full-service outsourcing, the risk and funding responsibility remain with your business. Essentially, ASO takes your tedious settlement processes and handles them far more efficiently. You get to focus on your core operations while leaving the nitty-gritty to the experts.

    Why Is It So Effective for Settlement Processes?

    Good question! Settlement processes typically involve a lot of moving pieces, from reconciling payments to dealing with various legal and compliance requirements. Here’s where ASO shines:

    • Streamlined Operations: An ASO provider is equipped with specialized tools and expertise that ensure faster and smoother processing of settlements. No more bottlenecks caused by manual intervention or inefficiencies.
    • Error Reduction: Settlement errors can be costly, both financially and legally. With a dedicated ASO team handling the administrative tasks, the chances of errors go down significantly.
    • Compliance Confidence: Settlement processes often involve navigating complicated regulations. ASO providers stay up-to-date on compliance requirements, ensuring your business stays on the right side of the law.

    Who Benefits the Most from ASO?

    ASO isn’t just for large corporations; it’s for any business looking to simplify its settlement workflows. Here’s where the magic happens:

    1. HR Teams: Say goodbye to headaches caused by endless paperwork. ASO providers lift that burden, allowing HR teams to focus on improving workplace culture rather than diving into spreadsheets.
    2. Finance Departments: Settlement figures require precision. With ASO handling claims processing, payment tracking, and reconciliation efforts, finance leaders can breathe easier.
    3. Business Owners: For business owners, fewer administrative worries mean more bandwidth to focus on growth strategies and scaling operations.

    How Do You Know It’s Working?

    An effective ASO partner brings measurable improvements to the table. You should see faster resolution times, fewer claims disputes, and clearer reports outlining settlement statuses. If your workflows feel more seamless and your team has fewer administrative distractions, you’re doing it right!

    How ASO Contracts Affect Your Business Operations

    ASO, or Administrative Services Only, may sound like complex industry jargon at first glance, but its relevance to business operations can’t be overstated. If your organization deals with employee benefits, health plans, or other managed services, understanding ASO contracts is crucial. So, let’s get into the nitty-gritty of how these contracts can influence your business!

    What Is an ASO Contract, Anyway?

    In simple terms, an ASO contract is an agreement between your business and an external service provider. The provider typically administers specific services – think claims processing, compliance management, or general administrative tasks – but they don’t bear the financial risk of those services. This means your organization retains control over funding and risk, while the ASO provider handles the day-to-day details. Pretty handy, right?

    The Immediate Impact on Business Workflow

    One of the most immediate and noticeable effects of an ASO contract is a streamlined workflow. By outsourcing time-consuming and specialized tasks, your internal HR or finance teams can focus on strategic initiatives rather than chasing down paperwork or deciphering regulations. Here’s why that matters:

    • Increased Efficiency: Your team can concentrate on core business activities, which means greater productivity.
    • Reduced Errors: Administrative services managed by seasoned experts often result in fewer mistakes.
    • Time Savings: Delegating administrative duties allows your business to save valuable hours.

    In a world where juggling tasks is the norm, ASO contracts bring some much-needed breathing room to your operations.

    Financial Implications: The Budgetary Balancing Act

    When it comes to finances, ASO contracts can be game-changers. Since the ASO model primarily covers admin services and leaves claims funding in your hands, your business gains a higher level of financial transparency and control. This is particularly beneficial for organizations looking to manage health benefits for employees.

    Here’s a breakdown of the financial impact to consider:

    1. Cost Predictability: Traditional insurance plans often come with unpredictable rate hikes. With ASO, costs for administration are usually set, so you can better project future spending.
    2. Customizability: Unlike cookie-cutter insurance plans, ASO contracts let you tailor services and funding to meet your business’s unique budget and goals.
    3. Scalability: ASO contracts grow with your business. Whether you’re a small business just starting out or a larger organization expanding, you can adapt your ASO arrangement as needed.

    Compliance & Legal Benefits

    Staying compliant in today’s regulatory landscape is no walk in the park. ASO providers help here by keeping up with changing laws and maintaining detailed records. As a result, you’re less likely to face penalties or legal complications. Plus, having experts guide you through these waters adds an extra layer of security to your operations.

    Potential Challenges and Mitigations

    Of course, it isn’t all sunshine and rainbows. ASO contracts can have their challenges, such as:

    • Finding the Right Provider: Not all ASO providers are created equal, so due diligence is vital in choosing a trustworthy partner.
    • Upfront Responsibility: Since the client retains financial risks, you’ll need robust financial planning in place.

    However, these hurdles can be addressed with thorough research, strategic planning, and ongoing communication with your ASO provider.

    Breaking Down ASO Costs: What You Need to Know

    When it comes to Administrative Services Only (ASO) agreements, understanding the cost structure is essential. Whether you’re a small business exploring efficient settlement processes or a seasoned organization refining your operational expenses, breaking down ASO costs gives you greater clarity and control over your budget. Let’s dive into it together and untangle the key components of these costs.

    What Makes Up ASO Costs?

    The costs in an ASO arrangement aren’t one-size-fits-all. They vary based on the size of your organization, the specific services you’re outsourcing, and the level of customization you require. Generally, ASO costs fall into the following categories:

    • Administrative Fees: This is the fee you pay to the ASO provider for managing administrative tasks. It typically covers claims processing, customer support, and reporting services. These fees are often calculated on a per-employee-per-month (PEPM) basis.
    • Technology Costs: Many ASO providers offer access to advanced technology, such as settlement processing tools, compliance software, or employee portals. These are sometimes bundled into your administrative fees but can also be an additional cost if optional features are added.
    • Claims Costs: In an ASO arrangement, claims payouts typically remain the responsibility of your organization. This means that while your provider administers the claims, you’ll need to budget separately for the actual settlement amounts.
    • Stop-Loss Insurance: To protect against large and unexpected claims that could disrupt your finances, many businesses opt for stop-loss insurance. This adds another layer of cost to consider, but it’s invaluable for mitigating financial risks.

    Flat Fees vs. Variable Costs

    Here’s something you’ll want to keep an eye on: your costs could fall into flat-rate or variable categories. Flat fees, like administrative fees, are easy to predict and can help with consistent budgeting. But variable costs, such as claims payouts, can fluctuate based on the volume and nature of claims submitted.

    For businesses looking for predictability, you might want to negotiate caps on certain fees or ensure you have a quality stop-loss insurance plan in place. This will help balance predictability while safeguarding against unpredictable, higher-than-expected claims expenses.

    Hidden Costs: What to Watch Out For

    Transparency is important when working with any ASO provider. Sometimes, costs that seem small can add up quickly. Be mindful of the following potential hidden fees:

    1. Customization Charges: Tailoring administrative services to your specific needs can incur extra costs. Ask ahead of time if adjustments to your tasks or reports come with a price tag.
    2. Upgrade Fees: If you’re adding features like advanced analytics dashboards or enhanced customer support for settlements, confirm whether these are part of your contract or come at a premium.
    3. Contract Termination: Some providers include early termination fees if you decide to end your ASO arrangement before the contract period is over. Be sure to read the fine print!

    Comparing ASO with Traditional Settlement Methods

    When it comes to managing settlements, there’s no shortage of options available. Two popular routes are Administrative Services Only (ASO) and traditional settlement methods. If you’re unsure about how these two approaches stack up and which might be right for you, don’t worry. Let’s break it down step by step and get to the core of what makes ASO stand apart from its traditional counterparts.

    Understanding Traditional Settlement Methods

    In a traditional settlement setup, businesses rely on full-service providers or insurers to handle all administrative tasks and claims processes. Essentially, these providers take over the end-to-end management, from processing payroll reimbursements to calculating claim settlements. While convenient, it often comes with a higher price tag and less flexibility.

    For businesses, particularly smaller ones, these traditional methods can feel like you’re getting a “one-size-fits-all” plan. There’s a lack of customization, and over time, the costs—though predictable—might not align with your needs as you evolve. Traditional methods are reliable but can occasionally be cumbersome.

    What Makes ASO Different?

    Now let’s talk about ASO. ASO offers more flexibility and control compared to traditional settlements. With an ASO arrangement, you’re essentially taking an active role in the back-end processes while outsourcing the administrative headaches to a trusted provider. Businesses get the freedom to fine-tune their settlement strategies while still leaning on expert administrative support.

    • Tailored solutions: Unlike traditional plans, ASO allows customization to suit your specific business needs instead of forcing you into a pre-designed mold.
    • Cost-effectiveness: While traditional methods often involve a bundled fee, ASO helps reduce costs by letting you pay for only the services you need.
    • Transparency: With ASO, you have greater visibility into how settlements are processed because you’re closer to the action. That visibility can lead to better decision-making for your business.

    Is ASO Right for You?

    Every business is different, and what works for one might not work for another. That being said, here are some signs that an ASO approach might align better with your operations:

    1. Your business wants more control over the settlement process.
    2. You’re seeking a cost-efficient, transparent system free from unnecessary overhead.
    3. You operate in an agile, fast-moving environment where flexibility is key.
    4. Your team has some understanding of settlements, or you’re open to learning the ropes with the support of an ASO provider.

    Traditional or ASO: Making the Switch

    If you’re already using traditional settlement methods, transitioning to ASO may seem daunting, but it doesn’t have to be! Start small by discussing your needs with experienced ASO providers. They’ll assess your current system, identify areas for improvement, and map out an ASO plan to streamline the process.

    Pro tip: Make sure to choose an ASO provider who understands your industry well and is equipped with the tools and expertise to manage your settlement needs seamlessly.

    Key Benefits of ASO for Modern Businesses

    ASO, or Administrative Services Only, is rapidly becoming a go-to solution for modern businesses navigating the complex world of settlements. But why is it hailed as a game-changer for companies? What makes it stand out? Today, we’re diving into the key benefits ASO offers, breaking them down into digestible chunks so you can see why businesses are turning to this strategy.

    1. Streamlined Administrative Efficiency

    One of the biggest headaches for businesses is the administrative burden that comes with managing claims, payments, and settlements. With ASO, a specialized provider takes on all those back-office responsibilities for you—freeing your team to focus on core business tasks. Think of it as outsourcing your administrative stress to the pros!

    • Less time spent on tedious paperwork.
    • Improved accuracy and fewer accounting errors.
    • An expert partner who knows the ins and outs of settlement processes.

    Simply put, ASO can significantly lighten the load for your internal teams, allowing them to dedicate more energy to projects that grow your business rather than bottling up resources in repetitive tasks.

    2. Cost Control and Transparency

    Here’s another reason businesses love ASO: cost control. Instead of blindly navigating fluctuating expenses, you gain clear insight into settlement processes and pricing structures. Most service providers offer detailed breakdowns, which ensures greater transparency in managing business finances.

    And here’s the bonus: because you only pay for the services you use (hence “Administrative Services Only”), you avoid unnecessary overhead associated with traditional settlement approaches. Who doesn’t want a leaner, more cost-efficient system?

    3. Tailored Solutions for Modern Needs

    Not every business operates the same way, so why use a cookie-cutter solution? With ASO, flexibility is key. Providers often offer tailored services that align with your unique business needs.

    Are you a growing startup in need of basic administrative support? Or are you an established company dealing with complex claims that require dedicated expertise? Either way, ASO providers can craft a solution that fits your operations perfectly, setting you up for success without wasted features you won’t use.

    4. Enhanced Focus on Core Competencies

    Imagine being able to shift your team’s focus from tedious settlement-related tasks to innovation and customer satisfaction. That’s one of the most overlooked benefits of ASO! By offloading administrative responsibilities to a trusted third party, businesses can become more agile and competitive in their respective markets.

    Pro tip: Less time and energy on settlements mean more bandwidth to stay ahead of market trends and invest in strategic initiatives. This is especially critical for businesses aiming to scale smartly.

    5. Compliance Peace of Mind

    Regulatory compliance can feel like walking through a minefield. Fortunately, ASO providers are experts in staying aligned with the latest legal and industry standards. This helps businesses avoid costly fines and other repercussions stemming from compliance lapses.

    Plus, knowing that your provider stays up-to-date on ever-changing regulations means you get to enjoy peace of mind—something every business leader values.

    6. Improved Risk Management

    With experienced ASO providers handling settlements, potential risks (like errors in claims handling or missed deadlines) become far easier to manage. These experts mitigate risks before they spiral into larger issues, saving your business from unnecessary expenses and reputational damage.

    Choosing the Right ASO Provider for Optimal Results

    When it comes to Administrative Services Only (ASO) arrangements, selecting the right provider is like finding the missing puzzle piece in your settlement process. Your ASO provider plays a crucial role in ensuring the smooth handling of administrative tasks, so making an informed and confident choice is essential. Let’s walk through some key considerations and tips for picking the perfect ASO partner!

    What Makes an ASO Provider “Right” for You?

    If you’re just starting your search, you may feel overwhelmed by the options available. The most important step is to understand what your business needs are. Every organization comes with unique challenges, so an ASO provider should feel like an extension of your team, rather than a “one-size-fits-all” solution.

    • Flexibility: Does the provider offer customizable services that align with your specific requirements, or do they force you into rigid, pre-packaged solutions?
    • Expertise: Do they have experience in your industry or a proven track record in handling settlements like yours?
    • Technology Integration: Do their systems seamlessly integrate with your existing tools and software for better efficiency?
    • Transparency: Are their pricing structures clear and straightforward, without hidden fees? Look for transparency to avoid surprises down the line.

    Key Qualities for Long-Term Success

    The right ASO provider will not just meet your current needs but will help you grow and adapt with time. Consider the following factors to ensure you’re setting up your organization for long-term success:

    1. Strong Communication: Remember, you’ll be working closely with your ASO provider, so responsiveness matters! Are they proactive in updating you about changes or resolving issues?
    2. Compliance Knowledge: A top-notch provider stays updated on industry regulations to help your business stay compliant. This ensures you’re avoiding costly pitfalls while focusing on growth.
    3. Cost-Effectiveness: The cheapest provider isn’t always the best. Instead, look for a balance between competitive pricing and high-value service. Think of this as an investment rather than just a line item in your budget.

    Questions to Ask Before Finalizing a Partner

    To feel truly confident, you’ll want answers to some practical and essential questions. Here are a few conversation starters when you meet with potential ASO providers:

    • “How do your offerings adapt as our company grows or changes?”
    • “Can you provide client testimonials or case studies relevant to businesses like ours?”
    • “What does your onboarding process look like? How quickly can we get started?”
    • “What kind of reporting or insights will you provide to keep us informed and in control?”
  • what does a billing address mean

    what does a billing address mean

    Let’s talk about something that pops up in almost every payment process: the billing address. You’ve probably encountered this term while shopping online, setting up a subscription, or paying bills, but have you ever wondered what it actually means? A billing address, simply put, is the address linked to your payment method—whether it’s a credit card, debit card, or even some other form of online payment.

    This is the address your bank or card issuer has on file for you, and it often serves as a point of verification. For example, when you enter your card details while making an online purchase, you’re typically prompted to provide your billing address as well. This ensures that the transaction aligns with the cardholder’s details and is one of the many ways financial institutions work to prevent fraud.

    In most cases, your billing address is wherever your credit card statements—or other billing communications—are sent. For many people, this is their home address. However, it could also be a business address or even a P.O. Box, depending on what you’ve set up with your bank or service provider. The key here is that this address must match the one your bank has on record. If there’s even a small mismatch (think typos or outdated information), your payment can be declined!

    Why Do Billing Addresses Matter?

    While a billing address might seem like a simple detail, its importance can’t be overlooked. It’s not just another box you fill in—it plays a big role in ensuring smooth transactions. Here are some highlights:

    • Transaction Verification: Your billing address helps vendors cross-check that you’re the rightful cardholder.
    • Fraud Prevention: Mismatched addresses are one of the red flags for detecting suspicious activity. A correct billing address can help safeguard your financial information.
    • Seamless Billing: When the billing address on record is correct, you’ll receive statements and notifications without delay.

    Imagine ordering something online only to have it canceled or delayed because of an address discrepancy. Frustrating, right? That’s why it’s essential to pay attention to this small—but critical—detail.

    location address

    How Do You Know Your Billing Address?

    If you’re unsure of what your billing address is or if it has changed recently, don’t worry! It’s usually quite easy to identify or update. Here’s a quick tip: check your most recent credit card or bank statement. The address where those statements are mailed is very likely your registered billing address. Alternatively, you can always contact your bank or log in to your account to verify or update it. Keeping your billing information up to date is crucial, especially if you’ve moved or are managing multiple addresses.

    By understanding the basics of a billing address and its role in everyday transactions, you’re already ahead of the game. Next time you’re at checkout, you’ll know exactly why this piece of information matters. So, whether you’re paying for a Spotify subscription or ordering that must-have gadget, keep your billing address accurate and up to date for smooth sailing!

    Why It Matters: Connecting Billing Addresses to Payment Security

    Let’s talk about secure payments—a critical component of any financial transaction. Whether you’re ordering a cup of coffee, renting a movie online, or making a large purchase, the billing address is more than just a line of text you type while checking out. Its relevance goes far beyond convenience; it’s deeply tied to payment security and safeguarding your financial information.

    What Role Does the Billing Address Play in Payments?

    Your billing address is like the digital gatekeeper of your financial identity. It serves as a verification tool to ensure that the transaction being made matches the information on file with your bank or credit card issuer. When you enter your card details, the payment processor cross-checks the address you’ve provided against the one your bank has on record. This process is often referred to as an Address Verification System (AVS).

    If there’s a mismatch between the billing address you enter and the one stored on your account, the transaction may be flagged, delayed, or even declined entirely. While mistakes or typos can cause frustration, these measures are in place to safeguard your money and prevent unauthorized access to your accounts.

    Protecting Against Fraud and Identity Theft

    In a world where online fraud and identity theft are increasingly common, the billing address acts as an essential security layer. Here’s how:

    • The primary purpose of checking a billing address is to ensure that the person using the payment method is authorized to do so.
    • In cases such as stolen credit cards or hacked payment information, fraudsters are less likely to know the correct billing address. A mismatch might immediately raise a red flag and stop the transaction before any damage is done.
    • It’s especially critical in online shopping, where the physical presence of the card can’t be confirmed, making address verification key to preventing fraud attempts.

    By requiring the billing address, companies add an extra hurdle for would-be scammers. While it might feel like an extra step, this layer of security plays a significant role in keeping your funds and personal information safe.

    When It Matters Most

    There are specific transaction types where entering the correct billing address becomes even more important:

    1. High-Value Purchases: When you’re buying expensive items, payment systems tend to scrutinize the transaction more rigorously to verify it’s legitimate.
    2. Subscription Services: When signing up for monthly or yearly subscriptions, providing accurate billing details ensures uninterrupted service.
    3. Cross-Border Transactions: Banks are especially alert when dealing with international payments. A mismatch in the billing address here can cause transactions to fail entirely.

    Tips for Getting it Right

    Here are a few simple habits to ensure your billing address information doesn’t cause unnecessary hiccups:

    • Keep your address updated: Any change in residence should be reflected in your bank records immediately to avoid a mismatch.
    • Double-check your spelling: Typos, misspelled street names, or incorrect ZIP codes are small errors that can cause big headaches.
    • Know how your bank formats your address: Some systems might abbreviate “Street” as “St.”—make sure your input matches exactly.

    Differences You Should Know: Billing vs. Shipping Address Explained

    Whether you’re shopping online or updating information for an account, you’ve probably encountered the terms “billing address” and “shipping address.” While they may sound similar, they serve distinct purposes in the transaction process. Understanding the difference between the two can save you from unnecessary confusion, delays, or even canceled orders. Let’s break it down together!

    So, What Exactly is a Billing Address?

    Simply put, a billing address is the address tied to the payment method you’re using. It’s usually the address where your credit card statements, bank correspondences, or other financial documents are sent. This is how payment systems verify that the person making the transaction is indeed the cardholder. Think of it as the “official” address for your payment details.

    And a Shipping Address?

    On the other hand, your shipping address is where your package, product, or order is physically delivered. It’s where you want the purchased items to end up. This address doesn’t necessarily have to match your billing address. For example, perhaps you’re sending a gift to a friend or shipping an order to a work address instead of your home. It’s a flexible option to ensure deliveries reach you—or someone else—wherever it’s most convenient.

    Key Differences in a Nutshell

    • Purpose: The billing address is tied to payment verification, while the shipping address determines where the item will be delivered.
    • Privacy: Your billing address is often personal and tied to sensitive financial records. Shipping addresses, in contrast, can vary and don’t necessarily involve security checks.
    • Use Cases: You might have one fixed billing address but different shipping addresses depending on the transaction or recipient.

    Why This Difference Matters

    Recognizing the difference between the billing and shipping address is more than just useful—it’s essential. Here’s why:

    1. Accuracy Prevents Delays: Mistaking one for the other could lead to a delayed order or, worse, a failed payment. Triple-check those fields!
    2. Security Checkpoints: Most online retailers and payment processors use the billing address as a security measure. Entering an incorrect billing address could flag a transaction, causing it to be declined.
    3. Flexible Shipping Options: This distinction allows you to send items to friends, family, or workspaces while still securely paying with your own card.

    Real-Life Scenarios to Watch Out For

    Let’s look at a couple of relatable situations:

    • Buying a Gift: You’re ordering a birthday gift. The billing address is your home address since that’s tied to your credit card. The shipping address is your friend’s address because you want the gift sent directly to their house.
    • Splitting Accounts: Imagine using a work credit card for a transaction. The billing address might be your company’s headquarters, but the package could be shipped right to your office location.

    How to Find Yours: Locating or Updating Your Billing Address

    Ever struggled to remember which address you used for billing or wondered how to update it when moving to a new place? Don’t worry—it’s easier than you think to locate or update your billing address. Let’s break it all down step by step, so you can keep everything running smoothly. It’s not rocket science, promise!

    What Exactly Is Your Billing Address?

    First things first—before hunting it down, let’s clarify what we’re talking about. Your billing address is the address connected to your payment method, like your credit or debit card. Banks and payment processors use this address to ensure the legitimacy of your transactions. It’s a critical piece of information, so it pays to keep it accurate!

    How to Check or Locate Your Billing Address

    If you’re unsure of the billing address associated with your card, here’s how to figure it out:

    • Check Your Bank Statements: Your billing address usually appears on monthly statements sent to your home or email. If you receive paper statements, just glance at the mailing address. For online banking customers, it’s available under their account settings.
    • Log Into Your Card Account: Most credit or debit cards have companion online platforms or apps. Just log in, go to settings or personal details, and verify the billing address listed there.
    • Call Customer Support: If you’re still not sure, contacting your bank or card issuer is always a reliable option. They’ll let you know what address is on file for your account.

    How to Update Your Billing Address

    Moving to a new space? Changed your information? Here’s how you can update your billing address hassle-free:

    1. Log In to Your Online Account: Whether it’s for your bank or favorite shopping platform, the easiest way to update your billing address is through their website or app. Most platforms have a profile or settings section where you can edit billing details.
    2. Use Customer Service Assistance: Not tech-savvy? No problem! Call or visit your bank directly. They’ll help you update your billing address in their records.
    3. Update Relevant Merchants: If your billing address is tied to online subscriptions or recurring payments, make sure to update it with those vendors too. Otherwise, payments might fail!

    Avoiding Common Pitfalls

    While updating or locating your billing address might seem simple, it’s easy to overlook small details. Make sure:

    • To double-check your entry—especially things like apartment numbers and postal codes. These seemingly tiny mistakes can lead to failed transactions!
    • You use consistent formatting to avoid confusion. For example, don’t switch between spelling out “Street” and using “St.”
    • Your new address is updated across all accounts. If your card information and billing address don’t match, you might face verification issues.

    Common Mistakes: Avoiding Issues When Entering Your Billing Address

    Let’s be honest—entering your billing address might seem like a boring, trivial task. But don’t underestimate its importance! One little error can cause payment failures, delays in your order, or even unnecessary headaches when you’re trying to figure out what went wrong. To help you steer clear of these hiccups, let’s break down some of the most common mistakes people make when entering their billing address—and more importantly, how to avoid them.

    1. Typographical Errors

    It’s easier than you think to slip up on your own address, especially when you’re in a rush. Maybe you misspelled your street name, left out your apartment number, or simply added an extra digit to your zip code. These tiny mistakes can have surprisingly significant impacts, as billing systems often match your address exactly as it’s registered with your bank or credit card provider.

    Tip to avoid: Double-check your input before hitting submit. Slow down, read your entry word-for-word, and verify that every piece of information matches your official billing records.

    2. Forgetting to Update Your Address

    Moved to a new place? Congrats! Just don’t forget to update your billing address accordingly. Using an outdated address can disrupt transactions because most payment processors cross-check the address you provide during a purchase with the one on file with your financial institution. If they don’t match up, the payment could fail.

    Tip to avoid: As soon as you move, notify your bank or credit card provider to update your billing address. It only takes a few minutes, and it ensures all your future transactions go through smoothly.

    3. Confusing “Billing Address” with “Shipping Address”

    This might sound basic, but it’s one of the most common mix-ups. Many people accidentally put their shipping address (where they want the package delivered) into the billing address field. This can lead to a rejected payment if the addresses don’t align with your card information.

    Tip to avoid: Pause for a moment when filling out forms and take note of whether you’re entering your billing address (linked to your payment method) or your shipping address (where the goods should go). Some platforms allow you to “check a box” to copy the same address into both fields if applicable.

    4. Using Nicknames or Abbreviations

    It might feel natural to use nicknames or shorthand while typing out your address—for example, “St.” instead of “Street,” or writing “Bill Smith” when your card says “William Smith.” However, precise matching with the financial institution’s records is key to a successful payment process.

    Tip to avoid: Use the exact name, address, and formatting style as it appears on any correspondence from your bank or from your credit card provider. Consistency is key.

    5. Mistaking Zip Codes for Postal Codes (Especially in International Transactions)

    In some regions, zip codes and postal codes are quite different! Entering inaccurate or incomplete postal information during international purchases is another common pitfall. This might confuse the payment gateway or flag the transaction as suspicious.

    Online Shopping Insights: The Role of Billing Address in E-Commerce

    Online shopping has transformed the way we shop—bringing convenience, variety, and excitement straight to our fingertips. But have you ever stopped to think about why you’re asked for your billing address every single time you make a purchase online? It’s not just one of those pesky fields meant to take up your time; your billing address plays an essential role in ensuring your payment goes through smoothly and securely.

    Why Your Billing Address Matters in E-Commerce

    When you shop online, your billing address acts as a critical piece of the puzzle in verifying your identity. Think of it as the digital equivalent of an ID check at the door—it confirms that you, and only you, own the payment method you’re using. This validation process helps protect both the retailer and the customer from fraudulent activity.

    How does this work? Credit card companies and other payment processors cross-check the address you’ve provided with their records. If the addresses match, your payment is likely to sail through smoothly. If they don’t, you might hit a frustrating “payment declined” message—and that’s often your bank trying to protect you from potential fraud.

    The Link Between Billing Address and Payment Security

    Fraud prevention is one of the biggest reasons billing addresses are required in e-commerce. Online businesses use a feature called Address Verification System (AVS) to help detect fraudulent transactions. Here’s how it works:

    • You input your billing address when you check out.
    • Your payment processor compares the address you provided with the one on file for your card.
    • If they match, it’s a green light! If not, the system may flag the transaction as suspicious.

    Without this extra layer of security, cybercriminals could potentially use stolen payment details to make purchases with ease. So, while typing in your billing address may feel tedious, remember—it’s there to protect you. A few extra seconds of effort can prevent a world of trouble.

    Tips for Hassle-Free Shopping with Your Billing Address

    To make sure your transactions go off without a hitch, follow these quick tips:

    1. Double-check your address: Always ensure that the billing address you input matches exactly what’s on file with your bank or card provider.
    2. Keep your bank updated: If you move, don’t forget to update your billing address with your bank. Using an outdated address is one of the top reasons payments fail online.
    3. Pay close attention to formatting: Something as small as a misplaced apartment number or spelling error can cause issues. When in doubt, refer to your official bank statements to confirm the exact format of your billing address.

    How Billing Addresses Improve Your Experience

    It’s not all about security—your billing address can also make shopping itself more streamlined. For example:

    • Billing addresses can help businesses determine the correct taxes and fees to apply based on your location.
    • Many online retailers use billing addresses to tailor ads, promotions, or localized services to you.

    Ultimately, your billing address does more than just confirm you’re the cardholder. It’s an invisible but invaluable part of the online shopping ecosystem, keeping your transactions safe and your experience customized.

    International Billing Addresses: What to Be Mindful of Across Borders

    Shopping or managing transactions across borders can be an exciting yet challenging experience, especially when it comes to handling international billing addresses. The process requires a little extra care to avoid any hiccups in smooth transactions. Whether you’re a seasoned globetrotter, a frequent online shopper exploring stores abroad, or handling payments for international clients, understanding the nuances of international billing addresses is essential.

    Why Are International Billing Addresses Different?

    At its core, a billing address is specific to the location tied to your payment method—often your bank account or credit card. However, because every country formats their address system differently, entering an international billing address can be tricky. Some common differences include:

    • The order of address components (e.g., postal code placement).
    • The presence (or absence) of specific details like province, state, or region.
    • Distinct formats for ZIP or postal codes.
    • Non-Latin alphabets or unique character sets used in specific countries.

    These differences matter because most payment processors use strict address verification systems to reduce fraud. A mismatch in formatting or missing information could result in declined transactions—even when your payment method is valid.

    Top Tips for Accurate International Billing Address Input

    Here’s the good news: With just a bit of preparation, you can confidently handle international billing addresses like a pro. Check out the following tips:

    1. Review the Address Format: Research how addresses are structured in the country you’re dealing with. For instance, Japan lists addresses from largest to smallest (country > prefecture > city > street), while it’s often the reverse for the United States or Canada.
    2. Match Your Payment Method’s Records: Ensure that the billing address you input matches the one linked to your credit card or bank exactly. If you’re unsure, log into your banking portal or contact your provider to confirm.
    3. Abbreviate Carefully: Some systems may shorten certain address components, like “Street” to “St.” If you’re uncertain, mimic the format listed on your recorded billing address.
    4. Use Latin Characters Where Required: Many international e-commerce platforms require Latin characters for address entry. If your address includes special characters, look up transliterated alternatives.
    5. Double-Check Postal Codes: Postal/ZIP codes vary greatly, from alphanumeric strings in Canada (e.g., “H0H 0H0”) to numbers-only codes in Australia. Precision is key—using even one wrong digit can jeopardize your purchase.

    The Role of Currency and Local Regulations

    An often-overlooked aspect of international billing addresses is how they interact with local currency and banking regulations. Some regions (e.g., the EU) may require additional steps like two-factor authentication during payment. Additionally, your international billing address could influence currency conversion fees or authorize additional identity verification. Familiarize yourself with these nuances based on your intended merchant or card provider’s policies.

    When to Seek Help

    Despite your careful efforts, introducing an international billing address might not always go as planned. There’s no shame in reaching out for help if you’re stuck:

    • Your card issuer or bank: They can verify and correct your billing address if needed.
    • The merchant/support team: Many online platforms have customer service teams well-versed in resolving international billing issues.
    • Online forums or guides: The shopping community is often an excellent place to find crowdsourced solutions.
  • what is a rotating shift, complete guide

    what is a rotating shift, complete guide

    Let’s face it—when it comes to work schedules, things can quickly get complicated. Some of us are familiar with the traditional 9-to-5, Monday-to-Friday routine, but not everyone’s work life fits neatly into this box. This is where the concept of rotating shifts comes into play. If you’ve ever heard the term and scratched your head trying to decode its meaning, don’t worry—you’re not alone! Let’s break it down in a simple, easy-to-digest way.

    A rotating shift is a type of work schedule where employees alternate between different shifts over a specific period of time. These shifts could cover mornings, afternoons, evenings, or even overnight hours, depending on the nature of the job. It’s a way to ensure that operations run smoothly and continuously, often in industries where a round-the-clock presence is necessary.

    But what does this look like in action?

    Imagine you work in a facility that’s open 24/7, such as a hospital or a factory. Instead of working the same shift day in and day out, you might be part of a system where your schedule rotates. For example:

    • Week 1: You work the morning shift from 7 a.m. to 3 p.m.
    • Week 2: You work the afternoon shift from 3 p.m. to 11 p.m.
    • Week 3: You work the night shift from 11 p.m. to 7 a.m.

    This pattern ensures that no single group of employees is stuck working the “unpopular” hours all the time. Sounds fair, right? This type of schedule isn’t exclusive to just one kind of workplace; it’s surprisingly common in various fields—but more on that in another section!

    work shift

    Why do companies use rotating shifts?

    Great question! One of the primary reasons companies implement rotating shifts is to keep their operations running seamlessly. Think about businesses that require 24-hour coverage, such as hospitals, manufacturing plants, customer service centers, or even transportation hubs. Rather than relying on one static group to handle the graveyard shift indefinitely, rotating schedules distribute the workload more equitably. This can help prevent burnout and makes the working environment a little fairer for everyone involved.

    Another reason is to accommodate fluctuating workloads. For instance, some businesses might have busier periods during specific parts of the day. By rotating shifts, they can ensure that enough employees are available during peak hours, while still covering the quieter times.

    Should you be worried about working rotating shifts?

    Not at all! While adjusting to a rotating shift may seem daunting at first, many people find that there are perks to this type of schedule. For example:

    1. You get a fresh perspective—working different shifts can help break the monotony of a fixed schedule.
    2. Rotating schedules often come with built-in rest days, giving you more flexibility in your routine.
    3. In some cases, jobs with rotating shifts offer higher pay, especially for those covering unconventional hours like nights or weekends.

    Still, like any work setup, there are challenges. Staying flexible with your sleep patterns and maintaining work-life balance can be key to thriving in a rotating schedule. But don’t worry—we’ll leave those tips for another section in this discussion!

    In a nutshell, rotating shifts are a clever way to balance workplace fairness with operational needs. They may take some getting used to, but armed with the right mindset and strategies, both employees and businesses can benefit hugely from this approach.

    Common Industries and Workplaces Using Rotating Shifts

    Let’s face it, not every job works conveniently within the traditional 9-to-5 window. For some industries, the work never stops, which is where rotating shifts come into play. Commonly used across a variety of sectors, rotating schedules keep operations running smoothly around the clock while ensuring that everyone gets a fair chance at different shifts. So, whether you’re job hunting or just curious, let’s explore the industries where rotating shifts rule the roost!

    The Healthcare Heroes

    First and foremost, let’s give a big shoutout to healthcare workers. Hospitals, clinics, and urgent care centers don’t sleep, and neither do the rotating shifts that keep them operational 24/7. Whether it’s a nurse on the night watch, a doctor on a weekend rotation, or lab technicians working after hours, this field epitomizes the importance of round-the-clock care. Rotating shifts here ensure that patients always have access to life-saving help and that no single employee shoulders the brunt of undesirable shift times.

    Manufacturing and Production Powerhouses

    Ever wonder how factories run like clockwork to churn out everything from cars to cans of soda? Rotating shifts are often the backbone of the manufacturing and production world. With global demands and tight deadlines to meet, companies use rotating schedules to cover three primary shifts: mornings, evenings, and overnight. This ensures a non-stop production cycle while preventing burnout among workers. If you’ve got a knack for working with machines or managing production lines, prepare to embrace rotating schedules!

    The Efficiency Wizards in Transportation and Logistics

    Next time you receive a package on an ordinary weekday night, think of the logistics teams hustling behind the scenes. Industries like shipping, freight, and delivery rely on rotating shifts to manage warehouses, transport goods, and coordinate deliveries in near real-time. Truck drivers, air traffic controllers, and warehouse operators often work at unpredictable hours, all thanks to their rotating schedules. Without them, your online orders would probably take forever to reach you!

    Public Safety and Emergency Services

    If there’s one industry where rotating shifts are non-negotiable, it’s public safety. Firefighters, police officers, and 911 dispatchers often work schedules that demand both flexibility and stamina. These employees can’t afford to let their guard down, and rotating shifts make sure there’s always a fresh team on duty to address emergencies, no matter the time of day or night. Hats off to these brave professionals!

    Energy and Utilities: Powering the World

    Ever notice how your lights stay on regardless of whether it’s dawn or dusk? That’s the magic of the energy and utilities sector. Rotating shifts are essential for power plants, water treatment facilities, and other utility services to ensure 24-hour coverage. From operating control rooms to monitoring systems, professionals in this field work around the clock so the rest of us can enjoy uninterrupted services at home or work.

    The Entertainment and Hospitality Night Owls

    Finally, rotating shifts are a staple in industries like hospitality and entertainment. Think about hotels that staff their front desks 24/7, casinos that attract night crowds, or concert venues prepping for after-dark fun. Workers in these fields—the bartenders, hotel managers, and security guards—often rotate their schedules to cover both high-energy evenings and quieter daytime hours.

    Different Types of Rotating Shift Schedules

    Rotating shifts, while common in many industries, are not a one-size-fits-all solution. There are several types of rotating shift schedules, each designed to match the needs of specific workplaces, employee availability, and workload demands. Let’s break down some of the most common types of rotating shift schedules. Perhaps you’ll even find inspiration for your team or better understand the structure you’re working in!

    1. Fixed Rotation Schedule

    This type of rotation follows a predictable pattern, making it easier for employees to plan their lives around work. For example, a nurse might work the morning shift for one week and then rotate to the night shift the following week. The benefits of this schedule are its predictability and fairness in sharing less-desirable shifts. Employees know what to expect well in advance, reducing the stress of uncertainty.

    Pros: Easy to understand and implement, fosters better planning for personal commitments.

    Cons: May not fully address the fatigue caused by constantly switching between day and night shifts.

    2. Continuous Rotation Schedule

    Think of this as a cycle that never takes a break. Whether it’s a 24/7 manufacturing plant, an emergency services hotline, or a hospital, continuous rotations ensure there’s no interruption in service. Employees might work on a weekly or biweekly rotation covering all shifts in a repeating cycle (e.g., mornings, evenings, nights).

    Pros: Maintains seamless operations around the clock, ensures all employees equally bear the load of varying shifts.

    Cons: Can be draining without adequate rest between demanding rotations, especially for overnight shifts.

    3. Split Rotation Schedule

    Split rotations involve dividing a workday into two or more distinct shifts—think morning and evening—or even multiple short shifts in one day. This is often used in retail or food service, where peak times don’t necessarily fill an entire 8-hour stretch.

    Pros: Flexible scheduling optimizes staffing during busy times, can create part-time opportunities for employees with other commitments.

    Cons: Interruptions between shifts can be inconvenient and reduce overall relaxation time for employees.

    4. Backward Rotation Schedule

    In backward rotations, employees shift from evening shifts to morning shifts, working in the opposite direction of natural circadian rhythms. While this is less common, certain industries adopt it to address specific staffing challenges.

    Pros: Can provide an operational advantage when specific coverage needs arise.

    Cons: Often considered the least desirable schedule due to its disruptive effect on sleep patterns and health.

    5. DuPont Shift Schedule

    A little more complex in structure, this schedule rotates employees over a series of four teams working two 12-hour shifts, followed by 3–4 consecutive days off. Popular in manufacturing and utilities, it ensures 24/7 coverage while providing long breaks for recovery.

    Pros: Employees love the extended time off, and it works well in labor-intensive workplaces.

    Cons: Day-long shifts can be exhausting, and transitioning between day and night shifts requires careful adjustment.

    Why Understanding These Types Matters

    Choosing the right rotating shift schedule can make the difference between a productive, engaged workforce and burned-out employees. For managers, it’s about balancing operational needs with employee well-being. On the flip side, employees who understand how their schedule is structured can plan better for rest, recreation, and family time.

    How Rotating Shifts Impact Employee Productivity and Health

    Rotating shifts can be a double-edged sword. While they’re often essential for keeping industries like healthcare, manufacturing, or customer service running smoothly 24/7, they can also bring unique challenges to productivity and employee health. Let’s dive into the ways rotating shifts affect workers and explore how both the good and the bad come into play.

    Productivity: The Balancing Act

    It’s not surprising that rotating shifts can influence an employee’s ability to perform at their best. After all, switching between day, evening, and night shifts disrupts the body’s natural rhythm. Here’s how it plays out:

    • Disrupted Circadian Rhythms: Did you know that our bodies are wired to follow a natural sleep-wake cycle, known as the circadian rhythm? Rotating shifts often push employees to work when their bodies expect to rest, leading to reduced focus and slower reaction times.
    • Fatigue and Reduced Efficiency: Sleep deprivation, a common side effect of shift work, can harm productivity. Employees may feel exhausted, make more errors, and struggle to meet deadlines.
    • Adaptability Matters: On the flip side, some employees thrive under rotating shifts when given proper adaptation time. A well-structured schedule can foster creativity, energy, and teamwork.

    But productivity isn’t the whole picture—let’s talk about health.

    The Health Implications of Rotating Shifts

    Our health is heavily dependent on maintaining regular sleep, diet, and exercise habits. Rotating shifts make this tricky, sometimes causing serious issues. Here’s what to watch for:

    1. Sleep Disorders: Irregular work hours often prevent workers from getting the recommended seven to nine hours of sleep. Chronic sleep deprivation can lead to insomnia, sleep apnea, or other long-term conditions.
    2. Increased Stress Levels: Consistently shifting between schedules creates added mental strain. This can lead to burnout, anxiety, or even depression. Imagine juggling your personal life around unpredictable hours—that’s a lot of pressure!
    3. Higher Risk of Chronic Illness: Studies suggest that shift workers are more prone to obesity, cardiovascular disease, and diabetes because of disrupted routines and inconsistent mealtimes.
    4. Digestive Difficulties: Ever tried eating a meal at 3 a.m. during your night shift? Digestive issues like indigestion or acid reflux are frequent complaints among rotating shift workers.

    So, What Can Be Done?

    Managing the impact of rotating shifts requires effort on both the employee’s and employer’s part. Companies can support their staff by providing structured schedules, adequate breaks, and training to help them adapt better. Employees, on the other hand, should focus on developing habits like maintaining a consistent sleep schedule (whenever possible), eating nutritious meals, and staying active even on odd hours.

    Best Practices for Managers in Implementing Rotating Shifts

    Managing rotating shifts can be a challenging but rewarding task. Get it right, and you’ll improve employee morale, foster team productivity, and ensure operations run like clockwork. To make sure your rotating shift schedule works for everyone, let’s explore some best practices that will help you, as a manager, set up an effective and supportive system.

    1. Plan and Communicate Well in Advance

    One golden rule for managing rotating shifts is to always plan ahead. Employees need time to adjust their personal lives to fit around work schedules, so aim to share shift rosters at least two to four weeks in advance. By giving your team ample time to prepare, you minimize confusion and build trust within your workforce.

    When communicating these plans, use multiple channels like emails, team meetings, or workplace scheduling tools to ensure everyone is on the same page. Transparency and consistent updates go a long way in building employee satisfaction.

    2. Create Fair and Balanced Schedules

    Nobody wants to feel like they’re bearing the brunt of tough shifts while others have it easy. A fair rotation schedule is one that spreads out nights, weekends, and holidays evenly across the team. Use an objective system or software to assign shifts, which reduces the risk of favoritism or human error. Better yet, involve your employees in the process—let them swap shifts (within reason) or have input into their preferences. This approach not only improves buy-in but also shows that you care about their needs.

    3. Prioritize Employee Well-being

    Rotating shifts can be physically and mentally demanding. As a manager, you need to prioritize the health and well-being of your team. One way to do this is by designing schedules in a way that minimizes disruption to sleep patterns. For example, forward-rotating shifts (moving from morning to afternoon to night) tend to be easier on the body than backward rotations.

    You can also encourage—and model—healthy habits. Provide employees with tips on managing their schedules, such as maintaining a consistent sleep routine, eating balanced meals, and staying physically active. Offering regular breaks and ensuring everyone has time to recover between shifts is another key step toward long-term well-being.

    4. Leverage Technology to Simplify Scheduling

    Gone are the days of manually creating shift rosters on spreadsheets. Today, there’s no shortage of tools and software designed to manage rotating shifts efficiently. Platforms like When I Work, Sling, or HotSchedules can streamline scheduling, allow for easy shift swaps, and send reminders directly to employees. Use these tools to save time and reduce scheduling errors—your team will thank you for it.

    5. Listen to Feedback and Stay Flexible

    Even the best managers may not get everything right on the first try—and that’s okay! What really matters is your ability to listen and adapt. Check in with your employees regularly to understand their concerns. Ask questions like:

    • “How are you finding the shift rotation?”
    • “What could we change to make things easier for you?”
    • “Are you getting enough time to rest and recharge?”

    Your willingness to make adjustments based on feedback shows your employees that you value them as individuals, not just workers. A little flexibility can go a long way in fostering a positive work environment.

    6. Train Supervisors to Support the Team

    Let’s not forget: your supervisors and team leaders play an essential role in the success of rotating shifts. Provide them with proper training on how to handle scheduling conflicts, recognize signs of burnout, and support employees through transition periods. Empowering your leadership team ensures that your shift roster is executed smoothly, even when you’re not personally overseeing it.

    Adjusting to Rotating Shifts: Tips for Employees

    Adjusting to a rotating shift schedule can feel like a big challenge, especially if you’re used to a fixed routine. But don’t worry — with a few smart strategies, you can learn how to adapt and thrive in this dynamic work structure. Let’s dive into some tips that can help employees conquer rotating shifts while staying productive, healthy, and well-rested.

    1. Prioritize Your Sleep

    Sleep is non-negotiable when it comes to adjusting to rotating shifts. However, we understand that changing your schedule frequently can mess with your body’s internal clock. Here are some ways to adjust:

    • Stick to a Routine: Try to create a consistent pre-sleep routine, even when your shift times change. This helps signal to your body when it’s time to wind down.
    • Optimize Your Sleep Environment: Darken your room using blackout curtains, and consider wearing earplugs or using a white noise machine to block disruptions.
    • Avoid Screens Before Bed: The blue light from phones and laptops can trick your brain into staying awake. Aim to disconnect at least 30 minutes before sleeping.

    2. Watch Your Diet

    What you eat (and when) plays a surprisingly big role in how you adapt to rotating shifts. Unhealthy snacking or erratic meal times can drain your energy and affect your focus.

    • Plan Balanced Meals: Pack nutritious, energy-boosting foods like lean protein, whole grains, and fresh vegetables to keep you going through your shift.
    • Keep Light Snacks Handy: Healthy snacks like nuts, fruits, or yogurt can prevent you from crashing mid-shift.
    • Avoid Heavy Meals Before Sleep: Late-night greasy or heavy eating can disrupt your sleep, no matter how tired you are.

    3. Stay Active

    Finding time to exercise might seem impossible with fluctuating shifts, but staying active reduces stress, improves alertness, and helps with sleep quality.

    • Fit in Short Workouts: Even a 20-minute brisk walk or stretch can keep you recharged and focused.
    • Incorporate Movement at Work: If you have time during breaks, take a quick walk or stretch to get your blood flowing.

    4. Manage Your Energy Levels

    Rotating shifts can leave you feeling drained, but staying mindful of your energy management can make a huge difference.

    1. Hydrate Often: Dehydration can worsen fatigue, so always carry a water bottle and sip throughout your shift.
    2. Take Mindful Breaks: Step away and recharge during breaks, whether that’s taking deep breaths or stepping outside for fresh air.
    3. Avoid Overdoing Caffeine: While coffee can be a lifesaver, having it close to the end of your shift can mess with your sleep later.

    5. Communicate and Create Support Systems

    Rotating shifts can feel isolating at times, especially when your schedule doesn’t align with friends and family. Be proactive in reaching out:

    • Keep Family and Friends Informed: Let them know your schedule so they can plan around your availability.
    • Find “Shift Buddies”: Connect with coworkers who are on the same schedule as you. Venting or sharing tips with someone in the same boat can be incredibly relieving.

    6. Listen to Your Body

    Everybody’s adjustment process is different. Listen to what your body is telling you, and don’t hesitate to make changes to your habits if something isn’t working. If you’re struggling with overwhelming fatigue, it may also be worth consulting a healthcare professional to rule out conditions like shift work sleep disorder.

    Tools and Software to Help Manage Rotating Shifts Efficiently

    Managing rotating shifts can feel like a Herculean task, especially when you’re responsible for ensuring everyone gets fair working hours, avoids burnout, and helps cover all essential responsibilities. That’s where technology swoops in to save the day! Whether you’re a manager overseeing shift patterns or an employee looking for clarity in your schedule, there are a range of tools and software available to keep things running smoothly. Let’s dive into some great options and tips to streamline shift management.

    Why Use Tools and Software for Rotating Shifts?

    Gone are the days when shift managers would break out paper schedules and pencils, hoping not to double-book employees or leave a gaping coverage hole. Using modern scheduling tools comes with several key benefits:

    • Accuracy: Automation minimizes errors like over-scheduling or forgetting critical compliance rules.
    • Time-saving: No need to manually juggle spreadsheets—let the software do the heavy lifting!
    • Transparency: Employees can easily see their shifts and request changes, leading to fewer miscommunications.
    • Fairness: Rotations can be spread evenly, fostering a stronger sense of equity among team members.
    • Adaptability: Tools allow for quick adjustments in emergencies or as personnel needs change.

    Spotlight on Popular Shift Management Tools

    Here are a few amazing tools that any workplace with rotating shifts might want to consider:

    1. Humanity: A super intuitive platform designed for workforce scheduling, Humanity offers great features like automatic shift planning based on staff availability, compliance assistance to handle labor laws, and easy schedule sharing with employees.
    2. When I Work: This tool is a favorite among managers for its user-friendly interface and capabilities, such as mobile notifications for shift reminders, availability updates, and instant approval of shift swaps between coworkers.
    3. Deputy: Deputy excels in creating optimized schedules for rotating shifts. What’s more? It integrates seamlessly with payroll tools, so there’s no headache when it comes to overtime calculations.
    4. Shiftboard: For bigger teams or industries with around-the-clock coverage needs, Shiftboard is great. It focuses on advanced scheduling metrics and analytics, making sure labor costs are controlled while maintaining proper coverage.
    5. Homegrown Spreadsheets with Tools: Sometimes workplaces customize their own systems using tools like Excel or Google Sheets. While not as feature-rich as dedicated software, templates and built-in sharing can meet smaller team needs efficiently.

    Features to Look for in Scheduling Software

    Not sure which tool is right for your team? Consider these must-have features to make scheduling easier and more employee-friendly:

    • Customizable Rotations: Every organization is unique, so the software should adapt to your team’s specific shift cycles.
    • Mobile Access: Employees should be able to check their schedules, swap shifts, or notify managers on-the-go.
    • Analytics: Look for tools that provide insights into labor costs, compliance risks, or irregular scheduling patterns.
    • Integration: The ability to connect with payroll and communication systems can simplify administrative tasks.
  • What does bi weekly pay mean

    What does bi weekly pay mean

    If you’ve ever wondered what “bi-weekly pay” actually means, you’re not alone. Many people see the term on job descriptions, pay stubs, or employment contracts and think, “Okay, sounds good… but what exactly does it mean?” Don’t worry — by the time you’re done reading, you’ll not only understand it, but you’ll also see how bi-weekly pay fits into the broader world of payroll systems. Let’s break it down together!

    At its core, getting paid bi-weekly means you receive your paycheck every two weeks. That’s it — simple, right? But here’s where it gets interesting: depending on the month or the year, there can be either 26 pay periods in a calendar year or occasionally an “extra” check if the stars (or the weeks) align just right.

    Why the Schedule? “Twice a Month” Isn’t Always Bi-Weekly

    Here’s where the magic of bi-weekly schedules lies. Unlike a semi-monthly payment setup where you’re paid twice a month, bi-weekly pay revolves around the number of weeks rather than dates on the calendar. This means you’ll receive payment every two weeks without worrying about whether it’s the 15th or the 30th. More commonly, payday falls on the same day of the week — say, every other Friday — adding predictability to your financial planning routine.

    Let’s put it another way: bi-weekly systems create consistency by essentially translating the 365-day year into 26 equal pay periods. There’s less juggling, and for many workers, knowing that payday always lands two weeks apart is a welcome relief.

    How Does This Affect Your Monthly Income?

    Here’s an intriguing thought: because months don’t divide evenly into weeks, you’ll typically receive two paychecks per month, but sometimes you’ll snag a rare and oh-so-wonderful “third paycheck month.” Yes, those glorious months (think July or December depending on where the payroll cycle begins) where windfall-like extra checks magically appear due to the calendar quirks. Talk about a nice surprise!

    Of course, it’s important to know that receiving paychecks bi-weekly doesn’t necessarily mean you’re earning more. Budgeting-wise, your annual salary or hourly wage is just being divided into more frequent, evenly spaced installments. It’s still your money — just delivered differently.

    Why Does Bi-Weekly Pay Work For Many Employees?

    • Predictability: Once you know your paydays, you can start to schedule bill payments, set savings goals, or even treat yourself guilt-free.
    • Works for Hourly Workers: Bi-weekly pay typically coincides well with billable hours, overtime, or other employment nuances.
    • Incentivized Workweeks: By breaking up earnings into fortnightly segments, employees often feel like payday is always just around the corner.

    How Bi-Weekly Differs From Semi-Monthly: Clearing the Confusion

    Let’s be honest—when it comes to navigating payment schedules, some of us may find ourselves scratching our heads. “Bi-weekly” and “semi-monthly” sound deceptively similar, don’t they? We get it. But fear not! By the end of this breakdown, you’ll be able to confidently tell the two apart and why this distinction actually matters.

    Bi-Weekly vs. Semi-Monthly: The Key Difference

    The primary difference between bi-weekly and semi-monthly pay lies in how they align with the calendar. While both payment methods split the year into multiple pay periods, their schedules don’t work the same way. Here’s what you need to know:

    • Bi-Weekly Pay: This schedule pays employees every two weeks on a fixed day (for example, every other Friday). Over a year, this results in 26 pay periods (or occasionally 27, depending on the calendar year).
    • Semi-Monthly Pay: With this system, employees are paid twice a month, typically on two set dates such as the 15th and the last day of the month. That’s a total of 24 pay periods annually.

    While the math seems fairly straightforward, where things get murky is how these schedules affect payment amounts and timing. Let’s dig a little deeper.

    Timing and Consistency of Paychecks

    The bi-weekly pay schedule is predictable because payments occur at regular intervals—exactly 14 days apart. This consistency can be especially useful for budgeting, as you’ll know your paycheck always lands on a specific day of the week.

    On the other hand, semi-monthly pay isn’t tied to specific weekdays. Since months vary in length, this can create irregular intervals between paychecks. For instance, if you’re paid on the 15th and 30th, one paycheck might come just 13 days after the last, while another could follow a gap of 16 days. This inconsistency could pose challenges if you’re trying to synchronize your bills or manage weekly expenses.

    How Pay Amounts Differ

    Here’s an interesting twist: even though you’re paid more frequently with a bi-weekly schedule, your individual checks tend to be smaller compared to semi-monthly ones. Why? Because your annual salary is divided by 26 pay periods instead of 24.

    This distinction becomes particularly noticeable during months with three bi-weekly paydays (yes, they exist!). If you’re on a semi-monthly schedule, you never get an “extra” paycheck in the year because your salary is simply spread evenly across your 24 pay dates. Those on a bi-weekly plan, however, might get an extra bit of flexibility during those bonus paycheck months.

    Which Is “Better” Depends on Your Lifestyle

    Let’s be clear—neither system is inherently better or worse. It comes down to personal preference and financial planning. Here’s how to think about it:

    1. If You Value Predictability: Bi-weekly pay might be your best friend. Knowing exactly when your paycheck will hit your account gives you a leg up on planning.
    2. If You Like Fixed Income Amounts: Semi-monthly pay can make it easier to align your budget with recurring monthly bills like rent or your mortgage.

     The Nuts and Bolts of Bi-Weekly Paychecks: Frequency and Features

    Let’s dive into the world of bi-weekly paychecks and unpack what makes this system tick. If you’ve ever wondered why employers favor this payment schedule and how it works behind the scenes, you’re in the right place. Bi-weekly pay isn’t just a matter of when you’re paid—it’s a structured approach with specific features and considerations. Let’s break it down in plain, simple terms.

    What Does Bi-Weekly Pay Really Mean?

    Bi-weekly pay means you get paid once every two weeks, typically on the same day, like every other Friday. If this sounds straightforward, that’s because it is! But here’s where it gets interesting: since a calendar year has 52 weeks, this payment schedule results in 26 paychecks a year.

    Here’s something to keep in mind—while most months will have two paydays under this system, two months out of the year will include a glorious third paycheck. (Yes, you read that right—bonus paycheck months!) These “extra” pay periods can feel like a pleasant financial boost.

    Key Features of Bi-Weekly Paychecks

    Now that you know the basics, let’s take a closer look at the core features of bi-weekly pay. These are the aspects that define how this schedule operates:

    • Consistent Schedule: Employees are paid every two weeks, making payday predictable and easy to track.
    • Uniform Work Hours: With bi-weekly pay, employers often calculate pay based on two weeks of work—making this system ideal for employees with hourly or salaried roles.
    • Tax Withholding: Taxes are deducted from each paycheck, but here’s the perk—spreading taxes across 26 pay periods often results in smaller amounts per paycheck compared to semi-monthly pay.
    • Overtime Compatibility: For hourly employees, bi-weekly pay aligns naturally with tracking overtime shifts worked during two-week spans. This makes it easier to calculate premiums for extra hours worked.

    How Does Bi-Weekly Pay Impact Cash Flow?

    If you’re paid bi-weekly, one major strength of this system is its regular cash flow. With paychecks arriving every two weeks, a steady stream of income allows you to plan around recurring expenses like rent, groceries, and bills. It’s almost like having a financial drumbeat—it keeps things moving smoothly.

    That said, budgeting between pay periods becomes critical. Since not every month will have a neat four-week structure, bi-weekly pay schedules don’t always align perfectly with fixed monthly bills. For example, a bill due on the 1st might occasionally fall between paydays. But fear not! With mindful planning, this hiccup can be easily managed.

    Common Fields of Employment That Use Bi-Weekly Pay

    Bi-weekly pay, a system where employees are paid every two weeks, is a popular payroll method across a variety of industries. While the concept is straightforward, the specific fields that rely on this schedule might surprise you. Here, we’ll take a lighthearted yet insightful look at the industries where bi-weekly pay is most common and why it works well for them.

    1. Retail and Service Industries

    The retail and service industries are bustling hubs of bi-weekly payment schedules. Think about it—whether you’re a cashier at your local grocery store, a sales associate at a big box retailer, or a hair stylist at a neighborhood salon, chances are you’re familiar with this pay cycle.

    Why is bi-weekly pay a favorite here? It’s simple. Many employees in these industries are hourly workers, and bi-weekly pay helps employers calculate overtime and hours worked more efficiently than monthly payroll. Plus, it ensures employees have a steady income without stretching too far between paychecks—which can be crucial in customer-facing jobs.

    2. Healthcare Professions

    If there’s one field where precision matters, it’s healthcare. From nurses to administrative staff, many healthcare workers receive their wages bi-weekly. This approach helps align payroll with the varying hours worked by staff, especially those putting in extra-long shifts or rotating schedules. Imagine the chaos of managing bi-weekly reports of shift differentials, on-call bonuses, and overtime without a reliable schedule!

    Hospitals, clinics, and private practices usually favor bi-weekly pay to give their teams financial stability while keeping operational demands manageable. After all, healthcare is a high-stakes field, and predictable paychecks help take one thing off employees’ minds.

    3. Education Sector

    Teachers, administrators, and school support staff often find themselves on bi-weekly payroll systems. Schools—whether public or private—operate on tight funding schedules and predictable cycles, making bi-weekly payroll a logical choice for everyone involved.

    For employees, this setup ensures a reliable income to navigate what can be a financially demanding job. For employers, it spreads payroll costs evenly throughout the year, even during holiday or summer breaks when students aren’t in session.

    4. Public Sector and Government Roles

    Municipalities, state offices, and federal government positions commonly operate under a bi-weekly pay system. This standardization helps ensure transparency and consistency in payroll for both employers and public servants who provide critical services.

    Government agencies often deal with a variety of pay structures, including union contracts and varying shifts, making bi-weekly pay an excellent “happy medium” for maintaining fairness and clarity.

    5. Corporate and Professional Services

    From tech giants to financial advisory firms, bi-weekly pay dominates in corporate landscapes. Why? Because large organizations often have thousands of employees in various roles, from salaried professionals to hourly interns. Having a consistent system means payroll departments can handle complexities like bonuses, commissions, and benefits more effectively.

    Bi-Weekly Pay: Benefits and Challenges for Employees

    Receiving a paycheck every two weeks might initially sound pretty straightforward, right? But when you dig deeper, bi-weekly pay can bring both perks and obstacles to employees. Let’s explore these in greater detail to help you make the most of it — or at least better prepare yourself.

    The Benefits of Bi-Weekly Pay

    Bi-weekly pay, when managed well, can be a surprisingly effective system. Here are some of its key advantages:

    • Frequent Income: Unlike monthly pay, bi-weekly pay means you’re receiving a paycheck every two weeks. This regularity can help ease financial pressure, especially when it comes to covering routine expenses like groceries, rent, or utility bills.
    • Extra Payday “Bonus”: Because there are 52 weeks in a year, bi-weekly pay schedules result in 26 paychecks annually. This means you’ll enjoy two months of the year where you’ll receive three paychecks instead of two — often referred to as “extra pay periods.” Think of these as financial bonuses you can save, invest, or use to treat yourself!
    • Better Budgeting Rhythm: With payments landing at consistent intervals, employees often find it easier to create a realistic budget. Having predictable pay makes accounting for fixed costs (bills, subscriptions) and variable spending (entertainment, dining out) a smoother process.
    • Simplicity in Dividing Expenses: Many people align recurring payments (like rent or mortgage) with their paycheck schedule. Bi-weekly pay periods simplify this, as you can match your bills with the receipt of your earnings. This can lower the risk of late payments or financial stress.

    The Challenges of Bi-Weekly Pay

    Like all systems, bi-weekly pay isn’t perfect. Here are a few challenges employees sometimes face:

    • Inconsistent Pay Dates: Though bi-weekly pay offers a steady rhythm, payday can sometimes feel unpredictable. Some months might end up having three weekends before payday lands, leading to longer gaps between paychecks. If you’re living paycheck to paycheck, this can cause tension.
    • Budget Complexity: Unlike semi-monthly pay (with two paychecks per month), bi-weekly pay shifts dates slightly from month to month. Since 26 paychecks don’t divide neatly into 12 months, budgeting isn’t as clean-cut as you might assume.
    • “Two-Month Lag” for Monthly Expenses: Say your rent is due on the first of every month. Depending on when your paychecks land, you may have to adjust your saving and spending habits to ensure money is set aside in time for recurring monthly obligations. This can initially take getting used to.
    • Misuse of “Extra Paychecks”: While those two extra pay periods can feel like a windfall, they can easily disappear if you don’t proactively plan. Many employees unintentionally spend these additional funds on non-essentials, missing out on unique opportunities to save or invest.

    How to Budget and Plan Finances Around Bi-Weekly Pay?

    Getting paid every two weeks might feel like a dream come true—until you’re staring at a calendar trying to figure out how to make your paycheck stretch. A bi-weekly pay schedule means you’ll receive 26 paychecks a year instead of the 24 you’d get on a semi-monthly schedule. While this can be exciting (hello, extra checks in two months!), it also means you need a solid plan to make your money work for you. Here’s how to ace your budgeting when you’re paid bi-weekly.

    Understand Your Pay Cycle

    First and foremost, know when you’ll get paid. Mark those pay dates on your calendar or sync them with your budgeting app to keep track. Typically, bi-weekly pay results in two paychecks per month, but twice a year, you’ll receive three. These “extra” checks are often referred to as golden opportunities. With an understanding of when this happens, your plan for those months can be extra intentional—save, tackle debt, or splurge responsibly.

    Build a Budget That Matches Your Pay Schedule

    Unlike a monthly paycheck, bi-weekly pay lends itself to a unique budgeting rhythm. Forget about the “one budget fits all months” approach. Here’s a simple method you can use:

    1. Divide and Conquer: Take your regular monthly expenses (rent, utilities, bills) and divide them between your first and second paycheck of the month. For example, if your rent is $1,000, you’ll set aside $500 from each paycheck.
    2. Plan for Non-Monthly Expenses: Some bills (like insurance premiums or quarterly subscriptions) don’t align neatly with a two-week pay period. Allocate a small portion from each paycheck toward these irregular expenses so you’re prepared when they come due.

    Master the Art of “Two Paychecks Per Month” vs. “Three Paychecks Months”

    Ah, the magic of the third paycheck—it’s like finding a little pot of gold! But before you start dreaming of shopping sprees or booking vacations, think strategically about this extra influx of cash. Since most of your regular expenses are already covered by two paychecks, your bonus check can serve as an opportunity to boost savings, pay down debt, or invest in a long-term goal.

    Always Pay Yourself First

    If there’s one golden rule of financial planning, it’s this: pay yourself first. Setting up automatic transfers from your checking account to your savings account as soon as the paycheck hits ensures that you’re prioritizing your future. A good starting point? Aim to save at least 20% of each paycheck if possible, but start with whatever amount feels feasible.

    Don’t Forget Variable Expenses

    A common mistake when budgeting around bi-weekly pay is forgetting about variable or occasional expenses—like birthdays, holidays, and car repairs. Build a buffer for these kinds of costs. Consider setting up a separate savings account for irregular expenses so they don’t disrupt your standard budget.

    Technology Is Your Friend

    Leverage budgeting apps that are designed for bi-weekly pay schedules. Tools like YNAB (You Need a Budget) or Mint allow you to monitor your spending, organize bills, and even highlight the weeks where you’ll receive that third paycheck. These apps align your financial goals with your specific pay rhythm, making your life far more manageable.

     Employer Perspective: Why Businesses Choose Bi-Weekly Payroll

    Ever wondered why so many employers opt for a bi-weekly payroll system? It’s not just a random decision—there are thoughtful considerations behind it! Let’s dive into the reasons businesses prefer this payroll schedule, from organizational efficiency to employee satisfaction, all while keeping it simple and engaging.

    1. Predictable and Balanced Cash Flow Management

    For businesses, cash flow is king. Opting for a bi-weekly payroll allows companies to maintain a predictable payment schedule throughout the year. With 26 pay periods in a standard year, employers can synchronize their financial planning, ensuring operational expenses and payroll obligations are well-balanced. This consistency is particularly helpful for small businesses that need to carefully manage their working capital without surprises.

    2. Easier Payroll Processing

    One of the major perks of a bi-weekly payroll system is its straightforward implementation. Compared to other payment frequencies like weekly or even daily payouts, bi-weekly systems reduce the number of payroll processing periods while still keeping employees happy with regular income. Fewer pay cycles mean less administrative burden for the payroll team, allowing HR and finance employees to focus on other critical functions.

    3. Employee Satisfaction Through Regular Paychecks

    Employers also take their team’s preferences into account. Many workers appreciate the regularity of bi-weekly pay—it’s frequent enough to keep their financial obligations met but not so frequent that it becomes chaotic. Compared to semi-monthly schedules, for instance, bi-weekly pay is consistent in timing (like getting paid every other Friday), which makes budgeting easier for employees. Satisfied employees often perform better, so this scheduling choice can lead to enhanced morale and productivity.

    4. Cost-Effective Approach to Payroll Administration

    There’s also a financial angle for employers here! By opting for bi-weekly payroll over weekly pay schedules, businesses can save on payroll processing fees. Some payroll providers charge per cycle, so reducing the number of cycles per month can translate into direct savings for the company. For businesses operating on tight budgets, this cost-efficiency is a big win.

    5. Simplified Compliance With Labor Laws

    With the complexity of labor and tax regulations, employers need a system that helps them stay compliant. Bi-weekly payroll aligns well with most state and federal requirements, making it an optimal choice for legal and tax reporting purposes. By sticking to this schedule, businesses reduce the risk of errors or penalties arising from inconsistent or poorly managed payment systems.

    6. Supporting Seasonal or Hourly Employees

    Another reason businesses choose bi-weekly payroll is that it works well across various employment types, particularly for hourly or seasonal workers. With two pay periods per month (sometimes three!), businesses can more accurately compensate employees for the hours they’ve worked without extended delays between earning and receiving wages. This flexibility ensures equitable and timely payment, which fosters trust between employers and their teams.