Category: Blog

  • Private Equity Software: Platforms, Features, Categories & How to Choose

    Private Equity Software: Platforms, Features, Categories & How to Choose

    If you’ve started researching private equity software, you’ve probably noticed something frustrating: there’s no single product that does everything. One vendor handles deal sourcing. 

    Another handles fund accounting. A third handles LP reporting. Nobody tells you this up front, so a lot of firms end up buying the wrong thing and rebuilding their stack eighteen months later.

    Private equity software isn’t one category of product. It’s a collection of tools that cover different parts of the investment lifecycle, sourcing, diligence, portfolio monitoring, fund accounting, fundraising, and investor reporting. 

    Some platforms cover two or three of these. None cover all of them well. Understanding that upfront will save you a lot of wasted demos.

    This guide walks through the full landscape: what private equity software actually does, the main categories, the platforms worth knowing in each one, and a practical framework for figuring out what your firm actually needs.

    What Is Private Equity Software?

    1. Private equity software definition
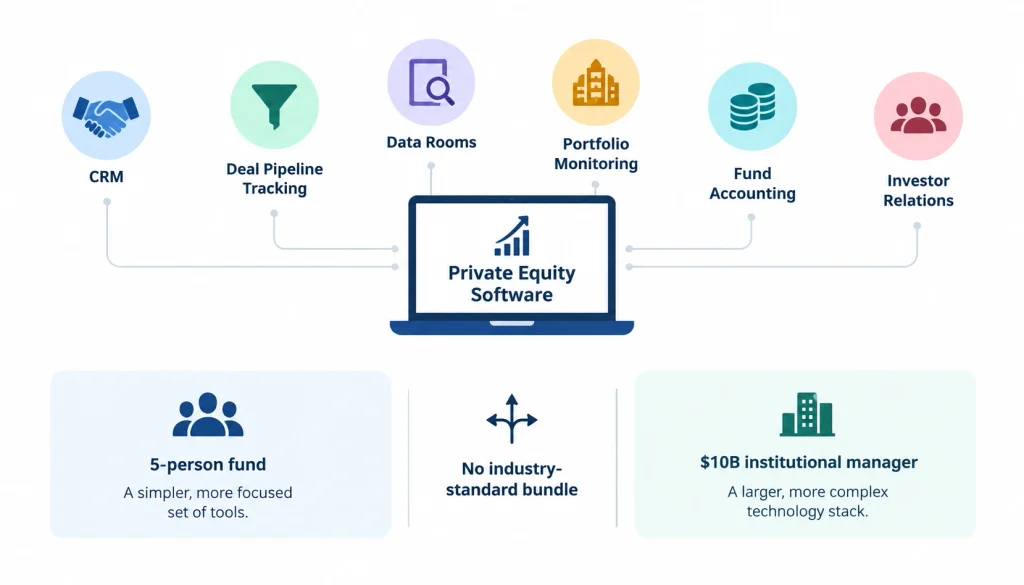
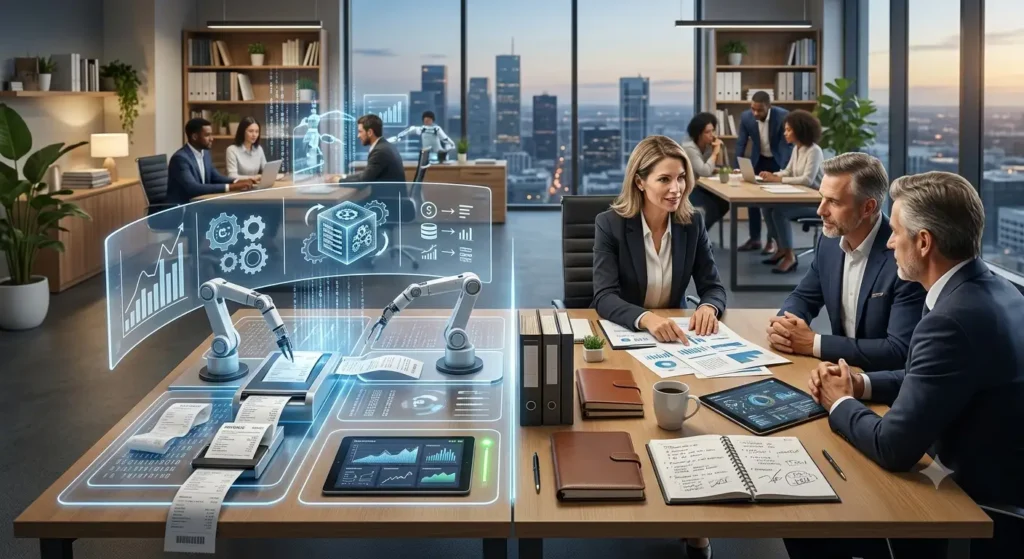
    Private equity software infographic showing CRM, deal pipeline tracking, data rooms, portfolio monitoring, fund accounting, and investor relations tools, with different technology needs for small and institutional PE funds.

    Private equity software is a general term for the technology PE firms use to run their investment operations, everything from finding deals to reporting results to LPs. It typically includes some mix of CRM, deal pipeline tracking, data rooms, portfolio monitoring, fund accounting, and investor relations tools.

    There’s no industry-standard bundle. A five-person fund and a $10 billion institutional manager will describe “our PE software” very differently, because they’ve assembled different pieces for different reasons.

    2. What problems does PE software solve?

    Most firms adopt this kind of software because spreadsheets stop working once the firm grows past a certain size. Common pain points include:

    • Deal information scattered across inboxes and personal notes
    • No visibility into where deals stand in the pipeline
    • Portfolio company KPIs collected manually, quarter after quarter
    • LP reports built by hand in Excel, prone to errors
    • No audit trail on who changed what, and when
    • Compliance and data security gaps as the firm scales

    Software doesn’t fix a broken process on its own, but it does give a firm a shared, searchable record instead of tribal knowledge living in one associate’s inbox.

    3. How private equity software fits into the investment lifecycle

    It helps to think of PE software in terms of the stages a deal and a fund pass through:

    Sourcing → Screening → Due diligence → Investment → Portfolio monitoring → Value creation → Exit → Investor reporting

    Different tools sit at different points on that line. A CRM lives at the sourcing stage. A data room lives at diligence. Fund accounting software lives at the back office, running continuously underneath the whole thing. Keeping this lifecycle in mind is the fastest way to figure out what category you’re actually shopping for.

    15 Private Equity Software Platforms to Know

    Private equity firms rarely rely on one application for every stage of the investment lifecycle. The software landscape spans CRM and deal sourcing, due diligence, portfolio monitoring, fund management, investor relations, and market intelligence.

    The platforms below are best understood by their primary use case, rather than as a single “best-to-worst” ranking.

    1. 4Degrees, CRM & Deal Sourcing

    4Degrees is a private-capital CRM focused on relationship intelligence, deal sourcing, and pipeline management. Its platform can help investment teams identify relationship paths to potential opportunities, organize deal pipelines, and reduce manual CRM data entry.

    Best suited for: PE firms focused on relationship-driven sourcing and deal-flow management.

    Key capabilities:

    • Relationship intelligence
    • Deal pipeline management
    • Contact and company management
    • Workflow automation
    • AI-assisted CRM workflows

    2. Affinity, Private Capital CRM

    Affinity is a CRM built specifically for private capital firms. Its PE offering covers relationship intelligence and deal workflows, while its current platform also emphasizes AI agents for tasks such as meeting preparation, conversation capture, pipeline updates, and investment-memo drafting.

    Best suited for: PE teams that want CRM, relationship intelligence, and automated deal-team workflows.

    Key capabilities:

    • Relationship intelligence
    • Deal sourcing
    • Pipeline management
    • Automatic activity capture
    • AI-assisted workflows
    • Multi-fund deal management

    3. Intapp DealCloud,  Deal Management & CRM

    Intapp DealCloud is an enterprise-oriented platform for investment and deal management. It is particularly relevant to firms with complex workflows that require extensive configuration and integration with broader operational systems.

    Best suited for: Larger or more complex investment organizations.

    Key capabilities:

    • Deal management
    • CRM
    • Pipeline tracking
    • Relationship management
    • Workflow customization
    • Reporting and analytics

    4. Allvue,  Fund Accounting & Portfolio Management

    Allvue provides private equity software combining fund accounting, portfolio monitoring, and investor-portal capabilities. Its private-equity offering is designed to connect front-, middle-, and back-office workflows.

    Best suited for: GPs and fund administrators needing integrated fund and portfolio operations.

    Key capabilities:

    • Fund accounting
    • Portfolio monitoring
    • Investor portal
    • Fund management
    • Reporting
    • Data management

    5. eFront,  Private Markets Investment Management

    eFront, part of BlackRock, provides technology covering areas such as deal sourcing, fundraising, portfolio monitoring, valuations, fund management, fund administration, accounting, investor reporting, and investor relations.

    Best suited for: Investment organizations requiring broad private-markets functionality.

    Key capabilities:

    • Deal sourcing
    • Portfolio monitoring
    • Valuation
    • Fund accounting
    • Fund administration
    • Investor reporting
    • Investor relations
    • Performance analytics

    6. S&P Global iLEVEL,  Portfolio Monitoring & Analytics

    iLEVEL is positioned around portfolio data collection, monitoring, and investment analytics. It can be used to consolidate portfolio-company information and provide investment teams with structured performance data.

    Best suited for: PE firms that need deeper portfolio monitoring and analytics.

    Key capabilities:

    • Portfolio monitoring
    • Data collection
    • KPI tracking
    • Performance analytics
    • Reporting
    • Portfolio-company data management

    7. Chronograph, Portfolio Monitoring

    Chronograph focuses heavily on portfolio monitoring and private-market data workflows.

    Best suited for: Investment teams that need centralized visibility into portfolio-company performance.

    Key capabilities:

    • Portfolio monitoring
    • KPI tracking
    • Investment data
    • Reporting
    • Performance analysis
    • Data management

    8. Juniper Square,  Fundraising & Investor Management

    Juniper Square is focused on private-market fund operations and investor management, including fundraising, investor onboarding, communications, and reporting.

    Best suited for: GPs looking to streamline investor-facing fund operations.

    Key capabilities:

    • Investor onboarding
    • Fundraising
    • Investor communications
    • Reporting
    • Investor management
    • LP experience

    9. Dynamo Software, Fund & Investor Management

    Dynamo provides a broader alternative-investment management platform spanning areas such as CRM, fund administration, investor relations, and reporting.

    Best suited for: Multi-asset investment organizations seeking broader operational coverage.

    Key capabilities:

    • CRM
    • Fund management
    • Investor relations
    • Fund administration
    • Reporting
    • Portfolio management

    10. PitchBook, Private-Market Intelligence

    PitchBook is primarily a private-capital data and research platform rather than a traditional fund-accounting or fund-administration system. Its platform covers company, deal, fund, and market intelligence and includes screening, fund analysis, market research, AI-enabled tools, and integrations.

    Best suited for: PE professionals conducting market research, sourcing, benchmarking, and investment analysis.

    Key capabilities:

    • Company research
    • Deal research
    • Fund research
    • Market intelligence
    • Screening
    • Benchmarking
    • Data/API integrations
    • AI-assisted research

    11. Preqin, Private-Markets Data & Research

    Preqin provides private-markets data, benchmarks, and research used for activities such as manager research, fund analysis, benchmarking, and portfolio evaluation. Preqin is now part of BlackRock and is also integrated into eFront Insight.

    Best suited for: Investment professionals and LPs requiring private-markets research and benchmarking data.

    Key capabilities:

    • Fund data
    • Manager research
    • Performance benchmarks
    • Market intelligence
    • Portfolio analysis
    • Private-markets research

    12. Datasite,  Virtual Data Rooms

    Datasite is primarily relevant to transactions and due diligence rather than fund accounting or portfolio monitoring.

    Best suited for: PE firms requiring secure document exchange during transactions.

    Key capabilities:

    • Virtual data rooms
    • Secure document sharing
    • Due-diligence workflows
    • User permissions
    • Document tracking
    • Transaction collaboration

    13. iDeals, Virtual Data Room & Due Diligence

    iDeals provides virtual data-room technology for secure document management and transaction workflows.

    Best suited for: Deal teams that need controlled document sharing during due diligence.

    Key capabilities:

    • Virtual data rooms
    • Secure document sharing
    • Access controls
    • Due-diligence management
    • Document analytics
    • Collaboration

    14. Ansarada, Deal & Data Room Management

    Ansarada focuses on secure transaction environments and data-room workflows.

    Best suited for: PE and M&A teams managing sensitive transaction information.

    Key capabilities:

    • Virtual data rooms
    • Due diligence
    • Document management
    • Permissions
    • Workflow management
    • Transaction collaboration

    15. S&P Capital IQ Pro,  Financial & Market Research

    S&P Capital IQ Pro provides financial and market intelligence that investment teams can use for company research, financial analysis, screening, and market evaluation.

    Best suited for: PE professionals who need broader financial and market data alongside their investment workflow.

    Key capabilities:

    • Company research
    • Financial data
    • Market intelligence
    • Screening
    • Comparable-company analysis
    • Industry research

    What Software Do Private Equity Firms Use?

    Here’s a quick look at the main categories before we go deeper on each.

    1. Private equity CRM and relationship intelligence
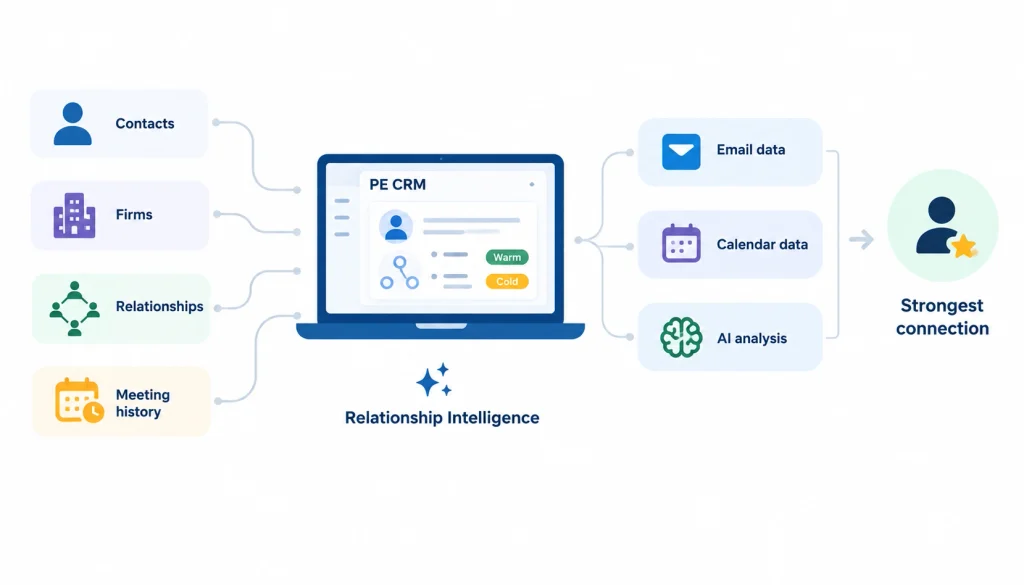
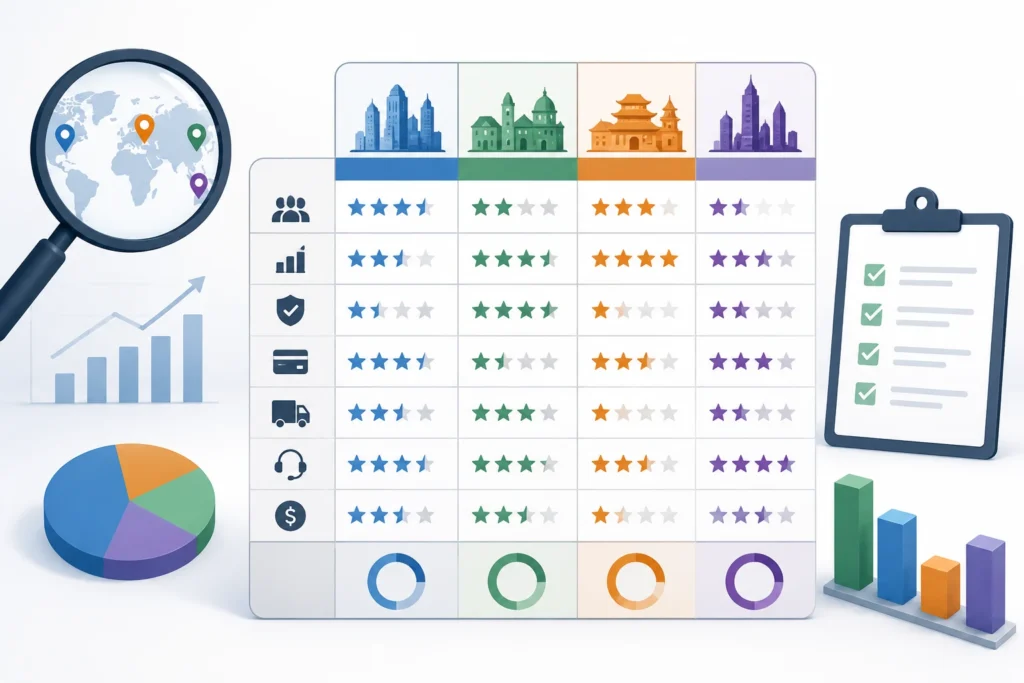
    Private equity CRM infographic showing contacts, firms, relationships, and meeting history connected with email, calendar, and AI analysis to identify the strongest business connection.

    A PE CRM tracks contacts, firms, and the relationships between them, who introduced whom, when a partner last spoke to a target company’s CEO, which deals are warm versus cold. Generic CRMs like Salesforce can technically be configured to do this, but purpose-built PE CRMs (4Degrees, Affinity, DealCloud) add relationship intelligence: they mine email and calendar data to surface who at your firm actually has the strongest connection to a given contact.

    2. Deal sourcing and deal management software

    Deal management software tracks the pipeline itself, stage, deal team, key dates, diligence status. In many products this overlaps heavily with CRM, which is why firms often buy one tool that does both rather than two separate systems.

    3. Virtual data room and due diligence software

    A virtual data room (VDR) is a secure, permissioned document repository used during diligence and deal execution. Datasite, iDeals, and Ansarada are the names that come up most often here. The core job is controlling who sees what, tracking who’s looked at which document, and managing Q&A between buyer and seller teams.

    4. Market intelligence and research platforms

    These tools, PitchBook, Preqin, S&P Capital IQ Pro, provide company, market, and fund data for sourcing and benchmarking. They’re research tools, not workflow tools, but most deal teams treat them as part of the daily stack.

    5. Portfolio monitoring software

    Once a deal closes, portfolio monitoring software collects operating and financial KPIs from portfolio companies on a recurring basis. Instead of chasing spreadsheets from each CFO every quarter, the GP gets a standardized dashboard.

    6. Fund accounting software

    This is the financial backbone: general ledger, capital call and distribution tracking, NAV calculation, allocations across LPs. Because financial workflows vary by industry and organizational structure, industry-specific accounting software can also be useful when evaluating specialized reporting and compliance requirements.

    It’s specialized accounting software, not a general ERP, because fund structures (carried interest, waterfalls, multiple share classes) don’t map cleanly onto standard business accounting.

    7. Fund administration software

    Related to fund accounting but broader, it covers the operational side of running a fund: investor records, compliance filings, capital account statements. Larger firms often run this in-house; smaller and mid-sized firms frequently outsource it to a third-party fund administrator who uses their own software.

    8. Investor relations and LP portal software

    An LP portal gives investors self-service access to their capital account statements, K-1s, fund documents, and performance reports. Juniper Square and Dynamo Software are common names here.

    9. Fundraising and investor onboarding software

    Some of the tools above extend into fundraising: tracking prospective LPs through a pipeline, managing subscription documents, and handling KYC/AML onboarding.

    10. Reporting and analytics software

    Dashboards and reporting layers that pull data from accounting, portfolio monitoring, and CRM systems into LP-facing or internal reports.

    11. Compliance and risk management software

    Tools for tracking regulatory obligations, conflicts of interest, and internal policy compliance, more common at larger, institutional firms with dedicated compliance staff.

    12. AI and workflow automation tools

    Increasingly, PE-specific AI features are showing up inside the categories above rather than as standalone products, think AI-assisted CIM summarization inside a deal management tool, or AI-generated first-draft portfolio company updates.

    Private Equity Software Categories at a Glance

    CategoryMain JobKey FeaturesPrimary Users
    CRMRelationshipsContacts, activity tracking, relationship intelligenceDeal teams
    Deal managementTransactionsPipeline, workflow, diligence checklistsInvestment teams
    Data room (VDR)DocumentsPermissions, Q&A, activity logsDeal teams, advisors
    Portfolio monitoringKPIsFinancial and operating metrics collectionPortfolio ops teams
    Fund accountingFund financesGeneral ledger, NAV, allocationsFinance
    Fund administrationOperationsInvestor records, filings, statementsOperations
    LP portalInvestor accessStatements, K-1s, document accessLPs, IR teams
    Market intelligenceResearchCompany, fund, and market dataDeal teams

    Private Equity Software Comparison

    When you’re actually comparing vendors, put them side by side on the same criteria instead of reading feature pages in isolation. A comparison table should cover: primary category, CRM depth, deal management, portfolio monitoring, fund accounting, investor reporting, LP portal, AI features, integration options, typical best-fit firm size, and rough implementation complexity.

    There’s a reason no credible comparison declares one overall winner: a tool that’s excellent for a 5-person emerging manager (like Juniper Square for investor communication) is the wrong purchase for a multi-fund institutional platform that needs eFront-level accounting depth. Filter by your own requirements rather than someone else’s “best of” list.

    All-in-One vs. Specialized Private Equity Software

    1. What is an all-in-one PE platform?

    An all-in-one platform tries to cover several stages of the lifecycle in a single product, say, CRM, deal management, and portfolio monitoring together. Allvue and eFront lean in this direction.

    2. What is a specialized PE software stack?

    A specialized stack means picking the best tool for each individual job and connecting them, a CRM from one vendor, a data room from another, fund accounting from a third. This is more common at firms with strong opinions about specific workflows, or firms that have outgrown a generic tool in one area but not others.

    3. Hybrid approach

    Most mid-sized firms end up somewhere in between: one core platform for two or three connected functions, plus a couple of best-of-breed tools bolted on for things the core platform doesn’t do well.

    4. All-in-one vs specialized comparison

    FactorAll-in-oneSpecialized stack
    IntegrationSimpler, since it’s one systemRequires connecting multiple tools
    FlexibilityLimited to what the suite offersUsually higher per function
    Vendor managementFewer vendor relationshipsMore vendors to manage
    Best forFirms wanting one throat to chokeFirms with specific, strong workflow needs
    ImplementationCan be a bigger single projectSpread across smaller rollouts

    Neither approach is objectively better. A firm with a lean ops team often prefers fewer vendors, even if each module is only “good enough.” A firm with a dedicated finance and ops function can usually get more value out of best-in-class specialized tools, because they have the staff to manage the integrations.

    Private Equity Software by Firm Size

    1. Software for emerging managers

    A five-person emerging manager raising their first or second fund typically prioritizes CRM for relationship tracking, LP onboarding, basic fund administration (often outsourced), and reporting. Trying to buy a full institutional-grade stack this early usually means paying for modules nobody on the team has time to configure.

    2. Software for middle-market PE firms

    As firms grow into middle-market territory, deal sourcing tools, portfolio monitoring, and more advanced analytics start to earn their keep. This is usually the stage where firms move off spreadsheet-based portfolio reporting.

    3. Software for institutional PE firms

    Larger institutional managers running multiple funds need multi-fund accounting architecture, dedicated portfolio analytics, formal security and governance controls, and reporting that can handle complex allocation structures across many LPs. This is where platforms like eFront and iLEVEL tend to show up.

    4. Software for fund administrators

    Third-party fund administrators serving multiple GP clients need software built for multi-client, standardized workflows rather than a single fund’s specific needs, reporting consistency across clients matters more than deep customization for any one of them.

    Key Features to Look for in Private Equity Software

    Rather than chasing a long feature checklist, focus on the ones that actually change day-to-day work:

    • Deal pipeline management: visibility into where every deal stands and who owns the next step
    • Relationship intelligence: surfacing who at the firm has the strongest connection to a target
    • Portfolio KPI tracking: standardized, recurring data collection from portfolio companies
    • Financial and valuation modeling: support for the models your team actually builds. Firms evaluating reporting and analytics capabilities may also benefit from understanding how accounting software with strong analytics supports dashboards, KPI tracking, and financial reporting.
    • Fund accounting: accurate handling of capital calls, distributions, and carried interest waterfalls
    • Investor reporting: automated generation of LP-facing reports rather than manual rebuilding each quarter
    • LP portal and onboarding: self-service document access for investors
    • Document management: version control and permissioning for deal and fund documents
    • Workflow automation: reducing repetitive manual steps in diligence and reporting
    • API and integrations: the ability to connect with your existing accounting, email, and BI tools
    • Permissions and audit trails: control over who can see and edit what, with a record of changes
    • AI capabilities: genuinely useful assistance, not a feature added for the sake of a marketing bullet point

    How Private Equity Software Connects to Your Existing Tech Stack

    A lot of the frustration firms run into isn’t about any single tool. It’s about tools that don’t talk to each other. Picture the ideal flow:

    CRM → Deal management → Data room → Accounting → Portfolio monitoring → Reporting → LP portal

    This type of connected workflow also depends on effective business data analytics, particularly when firms need to turn information from multiple systems into usable reporting and insights.

    If a deal moves from CRM into execution, the data room should be able to reference the same deal record. Once the deal closes, portfolio monitoring should pick up the company without anyone re-entering it by hand. Financial data from accounting should feed reporting and the LP portal automatically.

    In practice, this rarely happens end-to-end. Most firms maintain a “single source of truth” for deal data in one system, and accept that some manual reconciliation between systems is unavoidable. The goal isn’t a perfectly connected stack. It’s minimizing how much gets typed twice.

    AI in Private Equity Software

    AI has moved from a marketing buzzword to a genuinely useful feature in several parts of the PE workflow, though it’s worth being specific about where it actually helps:

    • Deal sourcing: surfacing companies that match a thesis based on data patterns rather than manual screening
    • Company and market research: summarizing public information on a target faster than an analyst reading ten sources
    • Document and CIM analysis: pulling key figures and flags out of long documents
    • Data extraction: converting portfolio company financials from PDFs or emails into structured data
    • Portfolio monitoring: flagging anomalies in reported KPIs
    • Investor reporting: drafting first-pass LP updates for a human to review and edit

    A McKinsey research note on private markets has pointed to growing planned investment in predictive AI tools among PE firms, which lines up with what’s showing up in vendor roadmaps. That said, AI in this space is still best treated as a drafting and flagging tool. Investment judgment and final sign-off on anything LP-facing still needs a human in the loop.

    Security and Compliance Considerations

    PE firms handle sensitive financial data, LP personal information, and confidential deal documents, so security isn’t optional. When evaluating a vendor, check for:

    • Role-based permissions, so access matches job function
    • Encryption in transit and at rest
    • Single sign-on (SSO) and multi-factor authentication (MFA)
    • Audit logs that record who accessed or changed what
    • Regular data backups and a documented recovery process
    • SOC 2 certification or equivalent security documentation
    • Clear answers on data residency and privacy compliance (relevant under regulations like GDPR for firms with European LPs)
    • A documented process for vendor security reviews, not just a sales rep’s verbal assurance

    Ask for the actual SOC 2 report, not just a badge on the website. Any serious vendor will provide one under NDA.

    Private Equity Software Pricing and Total Cost of Ownership

    1. What determines software pricing?

    Pricing usually scales with number of users, AUM, number of funds under management, which modules you license, data volume, and how much integration or customization you need.

    2. Costs beyond the subscription

    The license fee is rarely the full story. Budget for implementation, data migration from your old systems (or spreadsheets), training time for the team, integration work to connect with existing tools, any custom development, and ongoing administration once it’s live.

    A tool that looks cheaper on the subscription line can end up costing more once you add a six-month implementation and a part-time admin to keep it running. Ask vendors for a realistic total first-year cost, not just the license price.

    3. Questions to ask vendors about pricing

    • What’s included in the base license versus paid as an add-on module?
    • What does implementation typically cost and how long does it take for a firm our size?
    • Is data migration included, or billed separately?
    • What happens to pricing as we add users or funds?

    How to Choose Private Equity Software

    1. Map your investment lifecycle. Write down every stage from sourcing to exit and note where the current process breaks down.
    2. Identify manual processes. Where is the team still using spreadsheets or email as the system of record?
    3. Define must-have features. Separate what you actually need from what sounds nice in a demo.
    4. Decide between all-in-one and specialized systems. Base this on your team’s capacity to manage integrations, not just feature lists.
    5. Audit integrations. Confirm the tool actually connects to what you already use, accounting software, email, calendar.
    6. Evaluate security and compliance. Request documentation, not just a verbal assurance.
    7. Test with real workflows. Run an actual deal or reporting cycle through the demo environment instead of watching a canned walkthrough.
    8. Compare implementation requirements. Ask how long rollout typically takes for firms your size.
    9. Calculate total cost of ownership. Add license, implementation, migration, training, and ongoing admin.
    10. Check scalability and exit options. Understand what it costs, in time and money, to leave this vendor if it doesn’t work out in two years.

    Private Equity Software Demo Checklist

    Before or during a vendor demo, come prepared with specific questions rather than letting the sales team run a generic script:

    • Data: Can we bring a sample of our real deal or portfolio data into the demo?
    • Integrations: Which accounting, email, and BI tools does this connect to out of the box?
    • Security: Can you provide a current SOC 2 report and describe your incident response process?
    • Reporting: Can we see an actual LP report built in this system, not a mockup?
    • Implementation: What does a realistic timeline look like for a firm our size, and who owns the project on your side?
    • Support: What’s the support model after go-live, dedicated rep, ticket system, response time SLA?
    • AI: Which AI features are actually shipped today versus on the roadmap?

    Common Private Equity Software Mistakes

    • Choosing based on the longest feature list rather than the features you’ll actually use
    • Buying an all-in-one platform before mapping your own workflows
    • Ignoring integration requirements until after the contract is signed
    • Underestimating how long implementation will really take
    • Never clearly defining who owns the data if you switch vendors later
    • Skipping a real conversation about reporting requirements with the team that builds LP reports
    • Picking a tool that can’t grow with fund complexity, forcing a re-buy in two or three years
    • Treating AI output as a finished answer instead of a first draft

    Private Equity Software vs. Related Systems
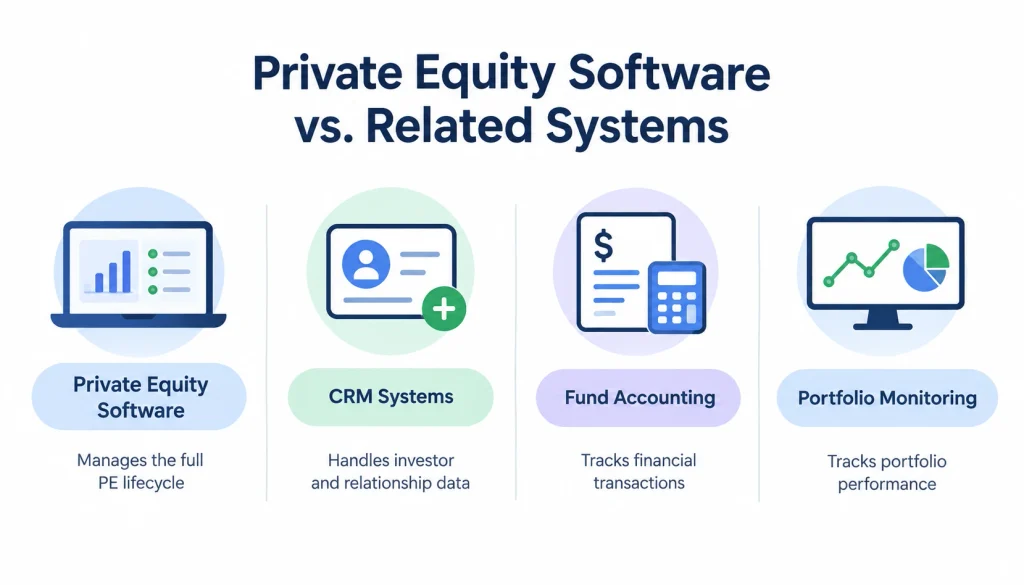
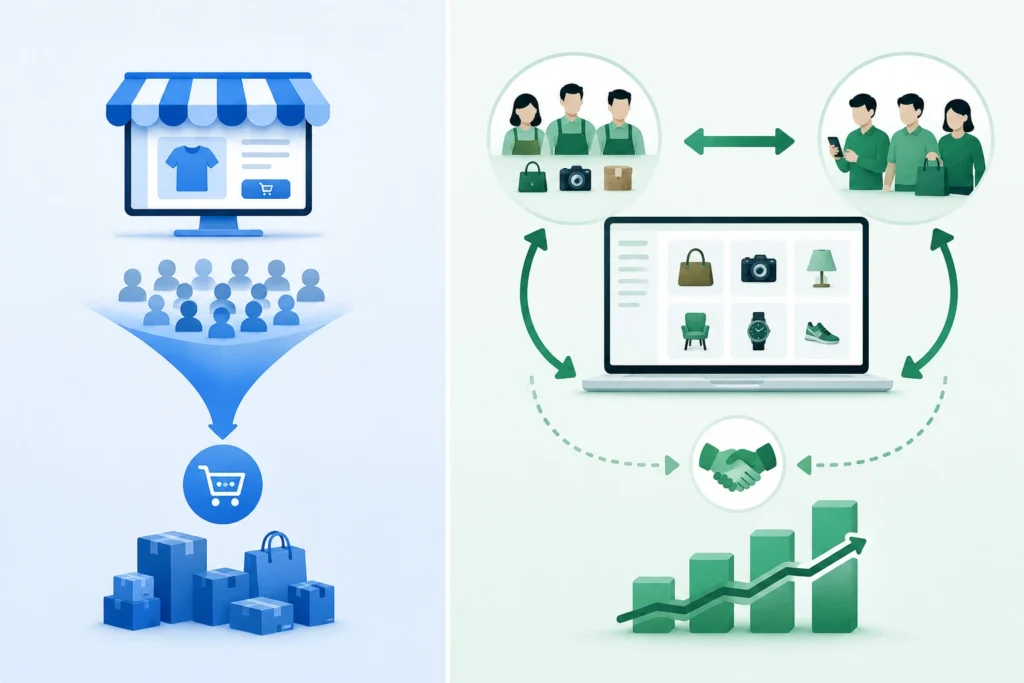
    Private equity software compared with CRM systems, fund accounting, and portfolio monitoring, showing their different roles across the private equity lifecycle.

    It’s easy to conflate PE software with adjacent categories. Here’s the quick distinction:

    • PE software vs CRM: a generic CRM (like base Salesforce) tracks contacts and deals broadly; PE-specific CRMs add relationship intelligence and deal-stage workflows built for the asset class.
    • PE software vs fund accounting software: fund accounting is one component of the broader PE software category, focused specifically on the general ledger, NAV, and capital accounts.
    • PE software vs fund administration: administration is operational (investor records, filings); accounting is financial (the books themselves). Many firms outsource the former, keep the latter closer in-house.
    • PE software vs portfolio management: “portfolio management” in a PE context usually means monitoring KPIs across portfolio companies, which is a narrower slice of the full PE software stack.
    • PE software vs ERP: a general ERP handles a company’s own operations; fund accounting software handles the fund’s investors and investments, which don’t map onto standard ERP structures.
    • PE software vs virtual data room: a VDR is a document-sharing tool for a specific deal or transaction, not an ongoing system of record.
    • PE software vs investor portal: the portal is the investor-facing window into data that lives in fund accounting and administration systems behind it.

    Frequently Asked Questions

    What is private equity software? 

    It’s the set of tools PE firms use to manage the investment lifecycle, deal sourcing, diligence, portfolio monitoring, fund accounting, and investor reporting. It’s not one product; most firms run several.

    What software do private equity firms use? 

    Commonly some combination of a PE CRM (4Degrees, Affinity, DealCloud), a data room (Datasite, iDeals), portfolio monitoring (iLEVEL, Chronograph), fund accounting (eFront, Allvue), and an LP portal (Juniper Square, Dynamo).

    What is the best private equity software? 

    There isn’t a single best option, it depends on firm size, fund complexity, and which stage of the lifecycle you’re solving for. A tool that’s ideal for a 5-person emerging manager is usually the wrong fit for a multi-fund institutional platform.

    What CRM do private equity firms use? 

    4Degrees, Affinity, and Intapp DealCloud are the most common purpose-built options; some firms also configure Salesforce, though it usually needs heavy customization to fit PE workflows.

    What does private equity software do? 

    Depending on the category, it can track deal pipeline, manage due diligence documents, collect portfolio company KPIs, run fund accounting, and generate investor reports.

    Final Takeaway

    Don’t pick private equity software based on which vendor has the longest feature list or the flashiest demo. The better approach is to start with how your firm actually works: how you source deals, manage diligence, track portfolio companies, handle fund accounting, communicate with LPs, and produce reports.

    From there, evaluate whether you need an all-in-one platform, a specialized tool for a specific workflow, or a combination of connected systems. Look closely at integrations, data migration, security controls, reporting capabilities, scalability, implementation requirements, and total cost of ownership, not just the features shown during a sales demo.

    For many firms, the practical answer won’t be one system that does everything. You may end up with two or three connected platforms, each handling a different part of the investment lifecycle. The goal is to build a technology stack that reduces manual work, keeps data consistent, gives your team better visibility, and can scale as your funds and portfolio grow.
  • 12 Unique Business Ideas You Can Start in 2026

    12 Unique Business Ideas You Can Start in 2026

    If you’ve spent any time searching for a new venture, you’ve probably noticed that most “unique business ideas” lists aren’t that unique. They recycle the same 50 suggestions (dropshipping, virtual assistant, candle making) and call it a day.

    This list is different. Each of these 12 unique business ideas takes an existing business model and points it at a specific customer with a specific problem.

    That’s what actually makes something unique: not that nobody’s ever thought of it, but that you’re solving a narrow problem better than the generic version does.

    Below, you’ll find a quick comparison table, then a full breakdown of each idea covering startup costs, required skills, how to land your first customers, and how to know if the demand is real before you spend a dollar.

    12 Unique Business Ideas

    1. AI Workflow Setup Service for Small Businesses

    What the business does

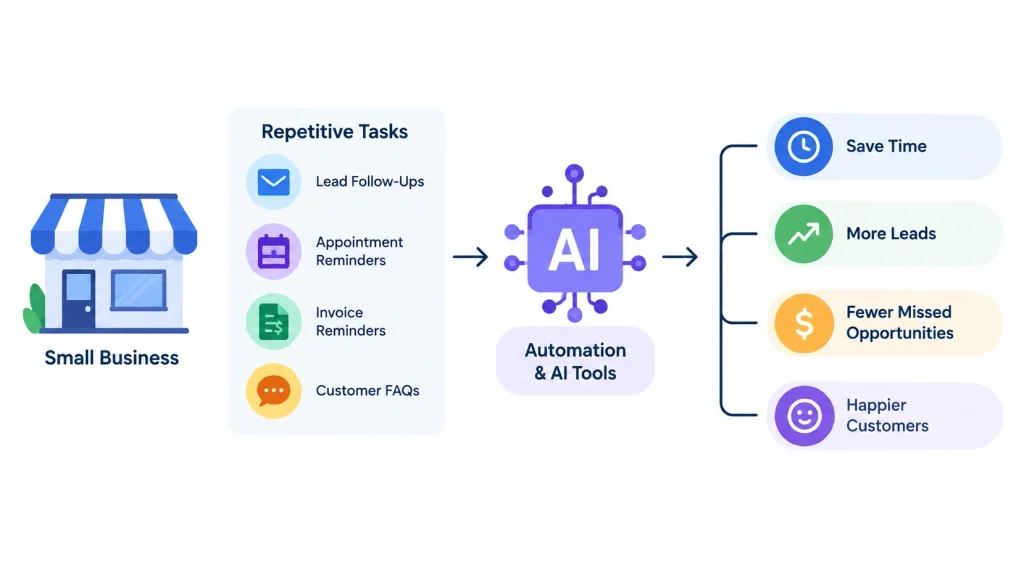
    AI workflow automation for small businesses, showing lead follow-ups, appointment and invoice reminders, and customer FAQs leading to time savings and fewer missed opportunities.

    You help small businesses automate repetitive tasks (lead follow-up, appointment reminders, invoice reminders, customer FAQs) using AI tools and simple automation platforms. You’re not selling “AI.” You’re selling hours saved and leads no longer falling through the cracks.

    Who pays for it

    Local service businesses (contractors, clinics, salons, real estate agents) that get enough inquiries to need a system, but not enough volume to justify hiring a full-time ops person.

    Examples of workflows to automate

    Missed-call text-back, appointment confirmation and reminders, review requests after a job is completed, lead qualification through a chat widget, and basic customer support for common questions.

    Startup costs

    Under $500. Most of the tools you’ll use (Zapier, Make, a CRM’s built-in automation) run on monthly subscriptions, and many have free tiers while you’re learning and building your first client project.

    Skills required

    Comfort with no-code automation tools, basic understanding of how small businesses operate day to day, and enough writing skill to draft the automated messages customers will actually receive.

    How to get the first 3 customers

    Pick one industry (say, dental clinics) and offer a free audit of their booking and follow-up process to two or three local businesses. Build one working automation as a demo, then convert that into a paid engagement.

    How to scale it

    Once you’ve built a workflow for one industry, you can package it as a template and resell it to similar businesses with light customization, instead of starting from scratch each time.

    Expert angle: Sell a defined outcome, like “we recover 15% of missed calls,” not a vague service called “AI consulting.” Buyers pay for results they can picture, not for technology.

    2. Senior Technology Concierge Service

    What problem does it solve?

    Many older adults own smartphones, tablets, and smart TVs they don’t fully know how to use, and they’re often uncomfortable calling a generic tech-support line. A patient, in-person concierge service fills that gap.

    Services you can offer

    Device setup, password and account management, video-call training so they can see grandchildren, scam and phishing awareness, and ongoing monthly check-ins.

    Ideal customers

    Adults 65+ living independently, and their adult children who often pay the bill on their parents’ behalf.

    Startup equipment

    A laptop, a simple toolkit of cables and adapters, and a car. This is one of the lowest-cost businesses on this list to start.

    Pricing model

    Hourly visits, a monthly retainer for ongoing support, or a one-time “new device setup” package.

    Customer acquisition through referrals

    Senior centers, assisted-living communities, churches, and local Facebook groups for caregivers are strong first channels. Word of mouth among adult children tends to be the biggest long-term driver.

    Scaling a personal service

    This business scales less easily than a digital one, because trust and personal rapport are a big part of the offer. A discussion on r/Entrepreneur describes exactly this challenge: one founder running an in-home tech support business for seniors talked through pricing, word-of-mouth growth, and how hard it is to hand the service off to another person without losing that trust (source).

    Treat that as one founder’s real experience, not a guarantee of how it’ll go for you. It’s still a useful preview of the actual day-to-day.

    3. Niche Digital Product Studio

    What you can sell

    Templates, calculators, checklists, planners, and other resources built for one specific profession or hobby: a cash-flow spreadsheet for freelance photographers, or a client-intake template for massage therapists.

    Finding a profitable niche

    Look for a group of people who already pay for tools or software related to their work. If they’re used to spending money to solve problems, a well-made template is an easy add-on purchase.

    Where to sell

    Etsy, Gumroad, or your own simple storefront. Etsy gives you built-in search traffic; your own site gives you better margins once you have an audience.

    Startup costs

    Close to $0 beyond your time, if you’re building templates in tools you already know like Canva, Google Sheets, or Notion.

    How to validate before creating dozens of products

    Build one product first. Post it in a relevant online community or share it with your own network, and watch whether people actually ask to buy it before you build the next nine.

    4. Microlearning Business for Professionals

    What is microlearning?

    Short, focused lessons (five to fifteen minutes) that teach one specific skill instead of a full multi-hour course. It fits into a lunch break or a commute, which is exactly why busy professionals prefer it.

    Profitable niche examples

    A weekly Excel formula for finance analysts, a client-communication script of the week for consultants, or a compliance update tailored to one industry.

    Course formats

    Short video lessons, an email series, or a private community feed. You don’t need studio-quality production. Clarity beats polish here.

    Platforms and technology

    Podia, Teachable, or even a private Substack newsletter with embedded video can work as your delivery platform.

    Pricing

    A modest monthly subscription tends to work better for microlearning than a large one-time course price, because the ongoing content is what keeps people paying.

    How to acquire your first students

    Share free lessons publicly on LinkedIn or in relevant professional groups. The free content proves your teaching is useful before anyone has to pay for it.

    5. Pet Travel Logistics Service

    The problem you’re solving

    Moving a pet internationally, or even on a long domestic move, involves health certificates, airline-specific crate rules, and paperwork most pet owners have never dealt with. It’s confusing enough that people will pay someone to manage it.

    Services to provide

    Booking pet-friendly flights, coordinating vet paperwork and health certificates, sourcing approved travel crates, and managing customs requirements for the destination country.

    Target customers

    Expats, military families relocating, and international adoptive pet owners.

    Partnerships to build

    Veterinary clinics, pet relocation specialists overseas, and airlines’ cargo or pet-travel desks are natural referral partners.

    Local vs. national opportunities

    You can start locally, serving pet owners moving out of your city, and expand into a fully remote consulting model once you understand the process well enough to handle any destination.

    Regulatory and insurance considerations

    Requirements vary significantly by country and even by airline, so this is a business where you’ll want to stay current on regulations rather than memorize a fixed set of rules. Build a habit of checking official government and airline sources before every booking.

    6. Life-Transition Home Reset Service

    What is a home reset service?

    A service that helps people reorganize, declutter, or set up their home during a major life change. It’s not routine cleaning, but a focused project tied to a specific transition.

    Target niches

    New parents preparing a nursery and reorganizing storage, seniors downsizing into smaller homes, families moving into a new house, and remote workers converting a spare room into an office.

    Service packages

    A single-day “reset” for one room, a full-home project spanning several days, or an ongoing maintenance visit once a month.

    Startup costs

    Low. You mainly need organizing supplies, a reliable vehicle for donation drop-offs, and basic liability insurance.

    Local marketing strategy

    Partner with real estate agents (for movers), pediatricians’ offices (for new parents), and senior-living placement services (for downsizers), since each group already interacts with your ideal customer at the exact right moment.

    Referral partnerships

    Movers and real estate agents are especially strong partners, because a home reset naturally happens right before or after they’ve already worked with the same client.

    7. Hyperlocal Specialty Food Brand

    Finding a local product niche

    Look at what your region already does well (a local ingredient, a regional recipe, a food tradition) and build a packaged product around it that isn’t already sold locally.

    Product examples

    A hot sauce made with a local pepper variety, a spice blend tied to a regional cuisine, or small-batch preserves using fruit from local farms.

    Farmers markets and online sales

    Start at farmers markets to test flavors and pricing with real customers face to face, then move to online sales through Shopify or Etsy once you know which products actually sell.

    Packaging and branding

    Simple, clear labeling that tells the story of the ingredient or region tends to outperform generic packaging, especially at markets where customers are buying the story as much as the product.

    Food licensing and compliance

    Most regions require a food handler’s permit and, depending on the product, a licensed commercial kitchen. Check with your local health department before you sell your first jar. Requirements vary a lot by state and product type.

    How to test demand before scaling

    Sell in small batches at markets for a few months before investing in larger production runs or wholesale accounts. Let actual repeat purchases, not compliments, tell you what’s working.

    8. Creator Back-Office Service

    What creators need help with

    Full-time content creators are often good at making content and bad at (or too busy for) the administrative side: scheduling, tracking analytics, repurposing content across platforms, and managing sponsorship deals.

    Services you can bundle

    Content scheduling and publishing, performance reporting, repurposing long videos into clips, and handling sponsorship outreach or contract logistics.

    Finding creator clients

    Mid-size creators (big enough to need help, not yet big enough to have a full team) are your best fit. Look on YouTube, TikTok, and newsletter platforms like Substack for creators in that range.

    Pricing models

    A monthly retainer covering a defined set of tasks tends to work better than hourly billing, since creators want predictable costs.

    Turning a service into an agency

    Once you have a repeatable process, you can hire contractors to handle individual tasks (editing, scheduling) while you manage client relationships and quality control.

    9. Niche Research Subscription

    What is a research subscription?

    A paid newsletter or report service that tracks one narrow industry closely and delivers regular, digestible updates, the kind of research a company would otherwise need a full analyst to produce in-house.

    Industries that could benefit

    Any industry that moves fast and has fragmented information sources: niche B2B software categories, specific regulatory areas, or emerging consumer trends within one category.

    What subscribers receive

    A weekly or monthly digest of what changed, why it matters, and what to watch next: curated and explained, not just a pile of links.

    Subscription pricing

    B2B research subscriptions can command higher prices than consumer newsletters, often in the range of $20–$200 per month, because they save a business real research hours.

    Research workflow

    Set a consistent schedule for monitoring sources, industry publications, regulatory filings, and relevant discussions, then summarize the same way every issue so subscribers know what to expect.

    How to prove value before launching

    Publish a few free issues first. If people forward them to colleagues or ask when the next one is coming, that’s a signal the paid version will have takers.

    10. Sustainable Event-Rental Business

    What can you rent?

    Reusable dinnerware, decor, and furniture for weddings and corporate events, positioned as the alternative to single-use, disposable event supplies.

    Sustainable positioning

    Many event planners and couples are actively looking to cut waste at their events, and a rental model is inherently more sustainable than buying disposable goods, which gives you a real, honest story to tell rather than a marketing gimmick.

    Inventory strategy

    Start with a small, versatile inventory (neutral colors and classic styles) that can work across many event themes instead of niche pieces that only fit one aesthetic.

    Storage and logistics

    You’ll need dry, secure storage space and a reliable way to transport, clean, and inspect items between events. This is one of the higher-overhead ideas on this list.

    Partnerships with event planners

    Wedding planners and corporate event coordinators are repeat referral sources once they trust your inventory quality and reliability.

    How to calculate rental ROI

    Track how many times each item rents before it needs replacing, and compare that lifetime rental income against the original purchase and cleaning costs to know which pieces are actually profitable.

    11. Specialized Compliance Support Service

    Choose one regulation or industry

    Pick a specific, well-defined regulatory area, such as data privacy for small healthcare practices or food safety documentation for small food producers, rather than offering general “compliance consulting.”

    What businesses need help with

    Understanding which rules actually apply to them, building the required documentation, and staying current as regulations change.

    Where expertise is required

    This is one of the higher-skill ideas on the list. You need real, verifiable knowledge of the regulation you’re working in, ideally backed by prior professional experience or certification.

    Tools and workflows

    Templates for required documentation, a tracking system for renewal and audit dates, and a habit of monitoring the regulating body’s official updates.

    Pricing

    Project-based fees for initial compliance setup, plus an ongoing retainer for monitoring and updates as rules change.

    Legal limitations and when to involve professionals

    Be clear with clients about where your support ends and where they need an actual attorney or licensed professional. Compliance consulting that strays into legal advice without a license creates real risk for both you and your client.

    12. Cultural Consulting for Global Businesses

    What cultural consulting involves

    Helping companies communicate, negotiate, and market effectively in a specific country or cultural context they’re trying to enter or already operate in.

    Potential clients

    Companies expanding into a new international market, remote teams working across countries, and marketing agencies localizing campaigns for a new region.

    Services you can provide

    Communication style training for cross-border teams, marketing message review for cultural fit, and negotiation coaching for a specific market.

    Required expertise

    Deep, lived familiarity with the culture and language you’re consulting on. This is a business built on genuine background, not a script you can memorize.

    Finding international clients

    LinkedIn is particularly strong here, since it’s where global business development and HR teams actually search for this kind of expertise.

    Building recurring revenue

    Move clients from one-off training sessions into ongoing retainers that review campaigns, communications, or hiring practices on a regular basis as their international presence grows.

    Quick Comparison: 12 Unique Business Ideas

    Costs and timelines below are estimates. Your actual numbers will depend on where you live, how you price your offer, and how fast you move.

    #Business ideaStartup costSkill levelFirst revenueModel
    1AI Workflow Setup ServiceLowMediumFastService
    2Senior Technology ConciergeLowMediumFastLocal service
    3Niche Digital Product StudioLowMediumMediumDigital products
    4Microlearning BusinessLowMediumMediumEducation
    5Pet Travel Logistics ServiceLow–MediumMediumMediumService
    6Life-Transition Home Reset ServiceLowLow–MediumFastLocal service
    7Hyperlocal Specialty Food BrandMediumMediumMediumProduct
    8Creator Back-Office ServiceLowMediumFastB2B service
    9Niche Research SubscriptionLowHighMediumSubscription
    10Sustainable Event-Rental BusinessMediumMediumMediumRental
    11Specialized Compliance SupportLow–MediumHighMediumB2B service
    12Cultural Consulting for Global BusinessesLowHighFastConsulting

    What Makes a Business Idea Truly Unique?

    1. Unique doesn’t mean nobody else is doing it

    Infographic showing that a unique business idea comes from finding an underserved niche within existing business models rather than relying on originality alone.

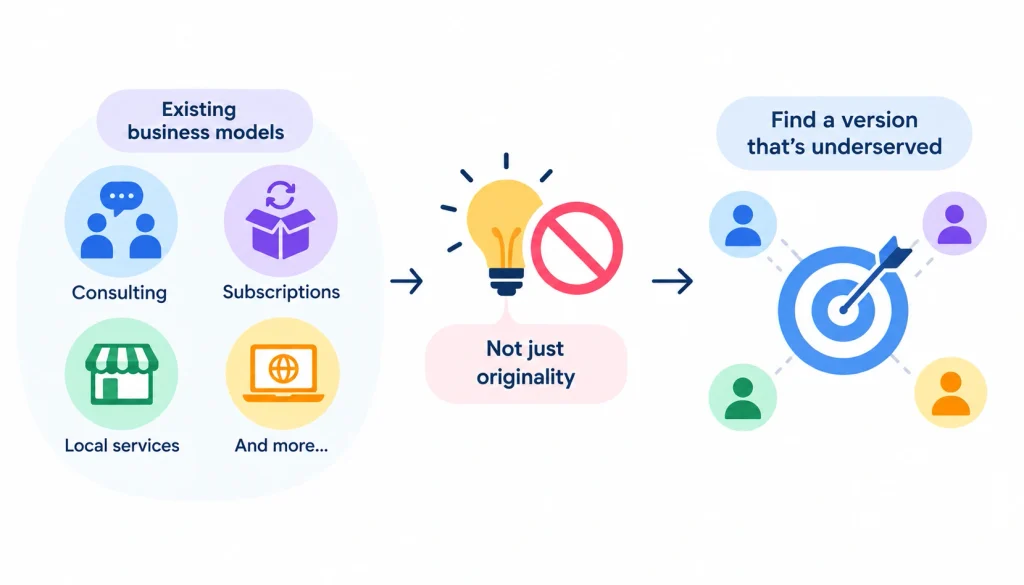
    Almost every business model already exists in some form. Consulting exists. Subscriptions exist. Local services exist. What makes an idea worth pursuing isn’t originality for its own sake, it’s finding a version of that model that the market is currently underserving.

    2. Solve a narrow problem for a specific customer

    “I help small businesses with marketing” is a crowded, forgettable pitch. “I set up automated lead-qualification workflows for local HVAC companies” is a specific offer with a specific buyer. The narrower you go, the easier it is to find, sell to, and become known among your first customers.

    3. Differentiate through delivery, positioning or niche

    You can build a unique business without inventing a new product category. Change who it’s for (a niche), how it’s delivered (in person vs. done-for-you vs. subscription), or how it’s positioned (outcome-based instead of hourly). Any one of those three levers can turn a common business into a differentiated one.

    4. How to tell whether an idea is already saturated

    Search the business type plus your city or niche and see what comes up. If you find ten nearly identical competitors with active reviews and no gaps in their offer, that’s a sign the space is crowded. If you find competitors but they’re all generalists, there’s usually still room for a specialist.

    How to Choose the Right Unique Business Idea

    1. Start with your existing skills

    Infographic showing two paths to getting a first customer: using existing skills for faster results versus learning new skills, which takes longer.

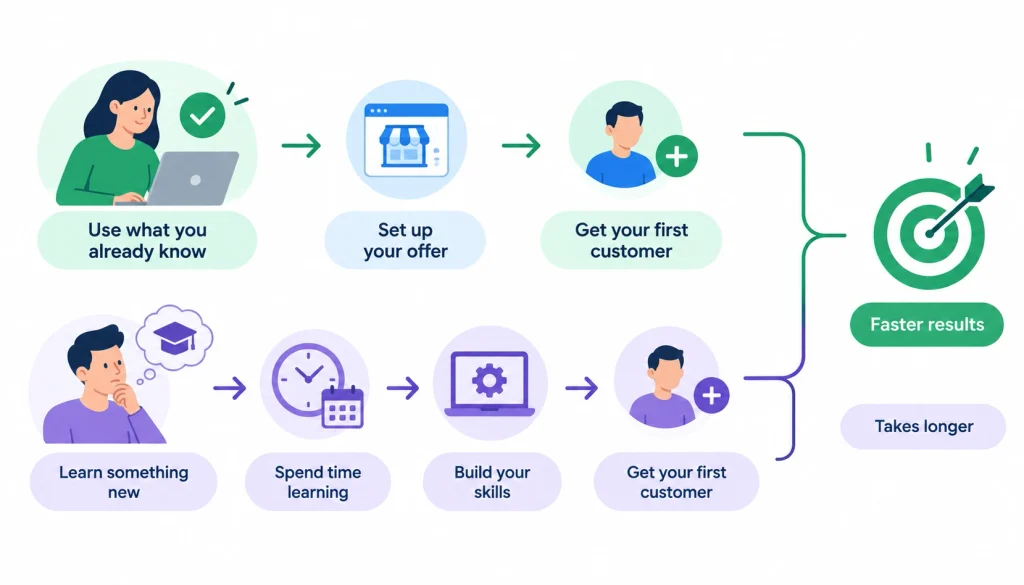
    The fastest path to your first paying customer is usually a business built on something you already know how to do, not something you’d need a year to learn first.

    2. Match the idea to your available capital

    Some of these ideas need under $500; others, like the event-rental business, need real inventory investment. Be honest about what you can afford to lose if the first version doesn’t work.

    3. Decide how much time you can commit

    A side-hustle pace and a full-time pace call for different ideas. Subscription and digital-product businesses can grow slowly in the background; service businesses usually need more consistent hands-on time from day one.

    4. Choose B2B or B2C

    Selling to businesses generally means fewer customers, higher prices, and longer sales cycles. Selling to consumers usually means more customers, lower prices, and faster (but noisier) feedback.

    5. Consider local vs. online delivery

    Local services build trust quickly through in-person interaction but cap your customer pool to one area. Online businesses can reach anyone but take longer to build the same level of trust. If you’re specifically looking for businesses you can operate from home, explore these work-from-home business ideas for additional options.

    6. Assess your customer-access advantage

    Do you already know people in your target market: a professional network, a community, a former employer’s client base? That existing access is often worth more than the idea itself.

    7. Simple decision framework

    Work through it in order: Skills → Problem → Customer → Cost → Distribution → Revenue model → Scalability. If you get stuck at any step, that’s usually the part of the idea that needs more thought before you start.

    How to Validate a Unique Business Idea Before Spending Money

    Step 1: Define the customer problem

    Write down, in one sentence, exactly whose problem you’re solving and why it’s painful enough that they’d pay to fix it.

    Step 2: Interview 10–20 potential customers

    Ask about how they currently handle the problem, not whether they like your idea. People are polite in interviews and will tell you your idea sounds great even when they’d never actually buy it, their current behavior is the more honest signal.

    Step 3: Analyze competitors and substitutes

    Even a “unique” idea usually has indirect competition. Figure out what people use instead today, and why your version needs to be better, cheaper, or more convenient than that.

    Step 4: Build a minimum viable offer

    Create the smallest version of your product or service that still solves the core problem: a single template, one client engagement, one small batch of product.

    Step 5: Create a landing page

    A simple page describing the offer, with a way to sign up or join a waitlist, tells you how many strangers are interested before you’ve built anything elaborate. If you’re building an online presence for your new venture, understanding what a business website does can help you create a page that builds trust and makes it easier for potential customers to take action.

    Step 6: Try presales or paid pilots

    Ask a handful of prospects to pay upfront, even at a discount, for the first version. Money on the table is a far stronger signal than “I’d probably buy that.”

    Step 7: Measure willingness to pay

    Track conversion from interest to actual payment, not just likes or positive comments. That gap is usually bigger than people expect.

    Step 8: Set a go/no-go decision date

    Pick a date in advance to review your results and decide honestly whether to continue, adjust the offer, or move on. Without a deadline, it’s easy to keep tweaking an idea indefinitely instead of deciding.

    How Much Does It Cost to Start a Unique Business?

    1. Businesses under $500

    Digital products, microlearning, senior tech concierge, and the AI workflow service can all realistically start on a few hundred dollars, mostly software subscriptions and basic tools.

    2. Businesses under $2,000

    Home reset services, pet travel logistics, and creator back-office services usually need a modest budget for marketing, insurance, and professional tools.

    3. Businesses requiring $2,000–$10,000+

    Hyperlocal food brands (licensing, ingredients, packaging) and sustainable event rentals (inventory, storage) carry the highest upfront costs on this list.

    4. One-time vs. recurring costs

    Separate your true one-time setup costs (equipment, initial inventory) from recurring costs (software, storage rent, insurance) when you’re budgeting, since recurring costs are what determine your break-even point.

    5. Hidden costs beginners overlook

    Business insurance, licensing fees, payment processing fees, and the cost of your own unpaid time during the slow early months are the ones people forget to budget for.

    How to Get Your First 10 Customers

    Start with your existing network

    Tell people you already know what you’re doing before you tell strangers. Referrals from people who already trust you convert faster than cold outreach.

    Direct outreach

    For B2B ideas especially, personally messaging a short list of well-matched prospects usually beats broad advertising in the first few months.

    Local partnerships

    For location-based businesses, partnering with a complementary local business that already serves your target customer can bring in referrals faster than any ad campaign.

    Referral marketing

    Ask happy early customers directly for introductions. Most won’t think to refer you unless you ask.

    Communities and social media

    Relevant subreddits, LinkedIn groups, and Facebook communities are often where your first customers already gather. Answer questions genuinely there before pitching anything.

    Search and content marketing

    Answering the exact questions your customers are searching for through a blog, videos, or social posts can build a steady stream of inbound interest. Learn more about why SEO for business matters when building long-term visibility.

    Paid advertising only after validating the offer

    Wait until you know your offer converts organically before you pay to send strangers to it. Ads amplify what’s already working, they rarely fix an offer that isn’t.

    Common Mistakes When Starting a Unique Business

    1. Confusing novelty with demand

    An idea being interesting doesn’t mean people will pay for it. Test actual demand before assuming novelty equals opportunity.

    2. Building before selling

    It’s tempting to perfect the product before showing it to anyone. Sell the unfinished version first, and let real customer feedback shape what you build next.

    3. Targeting everyone

    “Anyone who needs X” isn’t a customer. The narrower your first target customer, the easier it is to find them and speak directly to their problem.

    4. Underpricing

    New business owners often underprice out of fear of rejection, then struggle to raise prices later once customers are anchored to the low number.

    5. Ignoring customer acquisition

    A great product with no plan for reaching customers doesn’t become a business. Budget as much thought for acquisition as you do for the product itself.

    6. Spending too much before validation

    Save the bigger investments (inventory, equipment, a polished website) for after you’ve confirmed people will actually pay.

    7. Assuming AI automatically creates differentiation

    Adding “AI-powered” to an otherwise generic business description doesn’t make it unique. The differentiation still has to come from the specific problem you solve and for whom, with AI as a tool rather than the pitch itself.

    Frequently Asked Questions About Unique Business Ideas

    What are 12 unique business ideas?

    An AI workflow setup service, a senior technology concierge, a niche digital product studio, a microlearning business, a pet travel logistics service, a life-transition home reset service, a hyperlocal specialty food brand, a creator back-office service, a niche research subscription, a sustainable event-rental business, specialized compliance support, and cultural consulting for global businesses.

    What is the easiest unique business to start?

    The senior technology concierge and the niche digital product studio are typically the easiest to start, since both need minimal equipment and can begin within days of deciding to launch.

    What unique business can I start with no money?

    A niche digital product studio built with free or already-owned tools (Canva, Google Sheets) comes closest to a no-cost start, though you’ll still eventually want a small budget for a selling platform.

    What business can I start from home?

    The digital product studio, microlearning business, niche research subscription, and creator back-office service can all run entirely from home.

    How do I find a unique business idea?

    Look at problems you’ve personally run into, skills you already have, and groups of people whose needs are currently served by generic, one-size-fits-all options.

    Final Takeaway

    Don’t pick a business idea simply because it sounds unusual or different. A truly promising opportunity starts with a problem you understand, a specific customer you can realistically reach, and a business model you can test without putting a large amount of money at risk. Before investing heavily in equipment, software, inventory, or advertising, use the validation steps above to see whether people actually want what you’re offering and are willing to pay for it.

    That process helps you separate an interesting idea from a viable business opportunity. An idea might look exciting on paper, but if customers don’t have a strong enough problem, you can’t reach them efficiently, or the economics don’t work, it will be difficult to turn it into a sustainable business.

    The goal, then, isn’t simply to find the most unusual idea on a list. It’s to find one of these 12 unique business ideas that matches your skills, resources, and target market, and then prove that people will buy it before you commit significant time and money.

  • Best AI Video Editors for Faster, Smarter Video Production in 2026

    Best AI Video Editors for Faster, Smarter Video Production in 2026

    AI video editors are changing how creators approach post-production. Instead of handling every cut, caption, transition, and adjustment manually, editors can now rely on AI to speed up repetitive tasks and make it easier to turn raw footage into polished content.

    The best tools are not necessarily the ones with the most AI features. A good AI video editor should combine useful automation with enough creative control to let users shape the final result. Some focus on timeline editing, others are built around text-based workflows, and some combine AI generation with traditional editing.

    Here are five AI video editors worth considering in 2026, each suited to a different type of workflow.

    1. Invideo Editor

    Best for: Creators and teams that want AI-assisted timeline editing.

    Invideo editor combines a professional timeline with AI editing agents that can take on repetitive parts of the editing process. Creators can bring in raw footage and give the agents instructions for tasks such as reviewing footage, selecting usable takes, removing unnecessary sections, and assembling a starting cut.

    The resulting timeline remains editable, so users can inspect the AI-assisted changes, replace shots, adjust timing, and refine the sequence manually. This makes it useful for interviews, podcasts, documentaries, social content, and projects involving large amounts of raw footage.

    • Key features: AI editing agents, editable timeline, footage review, take selection, first-cut assembly, timeline editing, collaboration
    • Pros: Reduces repetitive editing work; speeds up first cuts; keeps AI changes editable; useful for footage-heavy projects
    • Cons: Less focused on specialized professional post-production than some desktop editors; users may need time to adapt to AI-assisted workflows
    • Pricing: Free editing access with paid plans available for additional usage and capabilities

    2. Adobe Premiere Pro

    Best for: Professional editors and production teams that need detailed editing control.

    Adobe Premiere Pro combines a traditional professional timeline with AI-powered features designed to speed up specific editing tasks. Its AI tools can assist with transcription, text-based editing, audio enhancement, masking, and other parts of post-production.

    Premiere Pro is particularly strong for editors working on complex productions because it offers extensive control over video, audio, effects, color, and project organization. It also connects with other Adobe applications and Frame.io for broader creative and review workflows.

    • Key features: Text-Based Editing, AI-powered audio tools, Generative Extend, masking, multicam editing, Lumetri Color, Frame.io integration
    • Pros: Extensive professional controls; strong Adobe ecosystem; advanced editing and finishing capabilities; regular feature updates
    • Cons: Steeper learning curve; desktop-focused workflow; subscription required for full access
    • Pricing: Paid subscription plans, with Premiere available separately or through eligible Creative Cloud plans

    3. DaVinci Resolve

    Best for: Filmmakers and editors who need editing, color, effects, and audio in one application.

    DaVinci Resolve brings several stages of post-production into a single desktop application. Its AI-powered features can assist with tasks such as object isolation, tracking, transcription, audio processing, and other editing operations.

    The software is particularly well known for its color grading capabilities, but it also includes dedicated environments for editing, visual effects, motion graphics, and audio post-production. This makes it suitable for projects that require detailed finishing as well as standard editing.

    • Key features: AI-assisted editing, Magic Mask, transcription, multicam editing, Fusion, Fairlight, advanced color grading
    • Pros: Powerful professional toolkit; excellent color tools; strong audio and VFX capabilities; capable free version
    • Cons: Large feature set can be overwhelming; demanding projects require capable hardware; some advanced features require the paid Studio version
    • Pricing: Free version available; DaVinci Resolve Studio is available as a paid upgrade

    4. Descript

    Best for: Podcasts, interviews, tutorials, and other dialogue-heavy videos.

    Descript approaches video editing through text. The platform transcribes recordings so creators can edit the video by changing the transcript. Removing a section of text can also remove the corresponding portion of the video, making dialogue-heavy editing faster.

    Its AI features can help with tasks such as removing filler words, improving audio, generating captions, and creating clips from longer recordings. The workflow is particularly convenient for creators who spend more time editing spoken content than complex visual sequences.

    • Key features: Text-based editing, transcription, filler-word removal, AI voice tools, captions, screen recording, clip creation
    • Pros: Simple approach to dialogue editing; fast transcription-based workflow; useful for podcasts and interviews; accessible to beginners
    • Cons: Less suited to complex cinematic editing; text-based workflow may not fit every project; advanced visual work may require another editor
    • Pricing: Free plan available with paid plans for additional features and usage

    5. CapCut

    Best for: Social media creators producing short-form videos quickly.

    CapCut combines a timeline editor with a wide range of AI-powered and automated features. Creators can generate captions, remove backgrounds, apply effects, enhance footage, and prepare videos for social platforms without needing advanced editing experience.

    Its workflow is particularly suited to short-form content for platforms such as TikTok, Instagram, and YouTube. Templates and automated features make it easy to create visually engaging videos quickly, although professional editors may find its controls less extensive than those of dedicated desktop applications.

    • Key features: AI captions, background removal, effects, templates, text-to-speech, video enhancement, social formats
    • Pros: Easy to learn; strong short-form workflow; large collection of templates and effects; useful AI automation
    • Cons: Less suited to advanced post-production; some features vary by region or plan; template-driven workflows may offer less creative control
    • Pricing: Free version available with paid features and plans

    How We Evaluated These AI Video Editors

    The tools were compared based on how effectively they combine AI assistance with practical editing control. Rather than focusing only on the number of AI features, the comparison considers how each editor helps creators complete real production tasks.

    Key factors include AI-assisted editing, timeline control, footage organization, ease of use, professional capabilities, collaboration, and suitability for different types of content.

    This matters because an editor designed for a filmmaker may not be the best choice for someone producing daily social media videos. The best option depends on where AI can save the most time in your particular workflow.

    Which AI Video Editor Should You Choose?

    There is no single AI video editor that works best for everyone.

    Choose invideo editor if you want AI agents to handle repetitive timeline work and help turn raw footage into an editable starting cut.

    Choose Adobe Premiere Pro if you need detailed professional editing and already work within the Adobe ecosystem.

    Choose DaVinci Resolve if advanced color grading, audio, visual effects, and professional finishing are important to your workflow.

    Choose Descript if most of your editing involves interviews, podcasts, tutorials, or other spoken content.

    Choose CapCut if your priority is creating short-form social content quickly with accessible AI features and templates.

    Final Thoughts

    AI video editing is moving beyond simple automation. The newer generation of tools can help creators find footage, organize projects, remove repetitive sections, edit dialogue, enhance visuals, and build starting sequences faster.

    The right choice depends on how much work you want AI to handle and how much manual control you need. For creators working with large amounts of footage, AI-assisted timeline workflows can remove much of the repetitive work that comes before creative refinement. For professional post-production, established editors such as Premiere Pro and DaVinci Resolve still offer deeper control across specialized areas.

    The most useful AI video editor is ultimately the one that fits naturally into your workflow and gives you more time to focus on the story, rather than the mechanics of editing.

  • How AI Tools Reduce the Need for Manual Frame-by-Frame Editing

    How AI Tools Reduce the Need for Manual Frame-by-Frame Editing

    Video editing can involve hundreds or even thousands of individual decisions. Editors may need to adjust timing, remove unwanted frames, clean up footage, track objects, fix visual issues, and make precise changes across a timeline. For detailed work, frame-by-frame editing gives editors complete control, but it can also be one of the most time-consuming parts of post-production.

    AI tools are changing this process by handling many repetitive adjustments automatically. Instead of manually inspecting every frame for certain tasks, editors can describe what needs to change and let AI analyze the footage, identify relevant frames, and apply adjustments across a sequence.

    This does not remove the need for detailed editing. Rather, it reduces the amount of manual work required to reach a clean starting point, allowing editors to spend more time on creative decisions.

    What Is Frame-by-Frame Editing?

    Frame-by-frame editing means making changes at the individual frame level rather than applying an adjustment to an entire clip.

    Editors may work frame by frame when they need to:

    • Remove a specific visual element
    • Correct a brief visual error
    • Track an object
    • Adjust a transition
    • Fix timing
    • Refine animation
    • Clean up individual frames

    This level of precision is useful when a small change can affect how an entire sequence looks. However, manually checking hundreds of frames can take considerable time.

    Why Is Manual Frame-by-Frame Editing Time-Consuming?

    A video contains many individual images played in rapid succession. A five-minute video at 30 frames per second contains 9,000 frames.

    An editor does not necessarily need to adjust every one of those frames manually, but some tasks require inspecting a large number of them. Repeating the same operation across multiple frames can quickly become tedious.

    For example, removing a moving object from a shot may require the editor to track its position over time. Correcting a visual issue across several clips can involve similar repetitive adjustments.

    AI can reduce this workload by recognizing patterns across frames instead of requiring the editor to treat each frame as a separate task.

    AI Can Detect Objects Across Multiple Frames

    One of the most useful applications of AI in video editing is object detection and tracking.

    Instead of manually identifying an object in every frame, AI can recognize the object and follow its movement through a sequence. This can help with tasks such as applying effects, blurring specific elements, replacing backgrounds, or isolating subjects.

    The editor can then review the tracking result and correct any areas where the AI loses accuracy.

    This approach is much faster than manually selecting the same object frame by frame.

    AI-Assisted Object Removal

    Removing an unwanted object from a video traditionally requires significant manual work. If the object moves through the scene, the editor may need to adjust a mask or selection repeatedly as its position changes.

    AI-powered removal tools can analyze the surrounding frames and determine how the background should appear after the object is removed.

    The editor can provide the initial selection, and the AI can propagate the change across the relevant portion of the video.

    This is particularly useful for removing temporary distractions, unwanted objects, or other elements that appear throughout a shot.

    AI Can Automate Rotoscoping Tasks

    Rotoscoping involves isolating subjects or objects from their backgrounds. It can be used for compositing, background replacement, visual effects, and other creative work.

    Traditional rotoscoping can require an editor or VFX artist to create and adjust masks across many frames. AI-powered segmentation can identify a person or object and track its boundaries through the shot.

    The result may still need manual refinement, particularly around hair, transparent objects, fast movement, or complicated backgrounds. However, AI can create a much faster starting point than drawing every mask manually.

    AI Can Help With Motion Tracking

    Motion tracking is another task that often involves detailed frame-level work.

    An editor may need to attach text, graphics, effects, or other elements to a moving object. Traditionally, tracking points are created and adjusted across the timeline to keep the added element aligned.

    AI can identify movement patterns and follow objects automatically. This allows editors to spend less time adjusting individual frames and more time deciding what should be added to the shot.

    AI-Assisted Frame Interpolation

    AI can also generate intermediate frames between existing frames.

    This is useful when creators want to create smoother slow-motion footage or change the apparent frame rate of a clip. Instead of manually creating intermediate frames, an AI model can analyze the movement between existing frames and generate new ones.

    The technology can be helpful when footage needs to be slowed down without making the motion appear excessively choppy.

    However, generated frames can sometimes contain visual artifacts, especially with complex movement, fast action, or overlapping objects. Editors should therefore review the result rather than assuming every generated frame is perfect.

    AI Can Find and Remove Unwanted Sections

    Not all frame-level editing involves visual effects. AI can also reduce the need for manual timeline cleanup.

    For example, AI can identify long pauses, repeated phrases, filler words, mistakes, or sections of silence in dialogue-heavy footage. Instead of manually searching through the timeline and cutting each section, editors can start with an automated cleanup pass.

    Invideo editor applies this broader approach to timeline editing by combining AI editing agents with a traditional editable timeline. Its agents can review raw footage, identify usable takes, remove unnecessary material, and create a starting cut that editors can then refine.

    This is useful because editors often spend considerable time preparing footage before they even reach the detailed creative editing stage.

    AI Can Apply Changes Across a Sequence

    Another benefit of AI is that an instruction can sometimes be applied to an entire sequence rather than repeated manually.

    For example, an editor may need to remove a particular type of unwanted element across several clips. AI can analyze the footage and apply the requested change wherever it detects the relevant element.

    This does not mean every result will be perfect. Complex footage may require corrections, and editors still need to check the output. But the initial pass can significantly reduce repetitive work.

    How AI Changes the Editor’s Workflow

    AI does not necessarily remove detailed editing from the workflow. Instead, it changes when and how editors perform it.

    A traditional workflow might look like:

    Find the problem → inspect frames → create a mask → adjust the mask → repeat → review

    An AI-assisted workflow can look more like:

    Identify the problem → describe or select it → let AI process the sequence → review → correct specific areas

    The difference is important. Editors spend less time performing repetitive operations and more time reviewing the results and making creative decisions. This shift is also visible in tools such as invideo Editor, where AI editing agents can take on broader timeline tasks rather than requiring creators to perform every operation manually. The editor can provide direction, review the resulting sequence, and then make precise changes where creative judgment is needed.

    Why Human Review Still Matters

    AI tools are not equally reliable in every situation. Fast-moving subjects, reflections, transparent objects, complicated backgrounds, motion blur, and unusual camera movements can all create problems.

    An AI-generated result may look correct for most of a sequence but contain a few frames where the subject’s edges break down or an object is incorrectly identified.

    This is why human review remains important. AI can handle the initial work, but editors need to check the result and correct areas where precision matters.

    How AI Tools Improve Editing Efficiency

    The biggest benefit of AI-assisted frame editing is not simply that it makes individual operations faster. It reduces the amount of repetitive attention required from the editor.

    Instead of spending hours making small adjustments across hundreds of frames, editors can focus on:

    • Deciding what the audience should see
    • Improving pacing
    • Shaping visual style
    • Refining performances
    • Checking continuity
    • Making creative choices

    The technology effectively moves the editor’s role further away from repetitive execution and toward creative direction and quality control.

    Where Manual Editing Still Makes Sense

    There are situations where frame-by-frame editing remains the better option.

    Highly detailed visual effects, complex compositing, animation, precision retouching, and difficult tracking shots may require direct manual control. Professional editors and VFX artists may also prefer manual adjustments when a specific visual result cannot be reliably described to an AI system.

    The best workflow is often a combination of both approaches. AI can handle the first pass, and the editor can take over when precision or creative judgment is required. This balance is central to the workflow in invideo Editor as well. AI can handle repetitive editing and timeline preparation, but creators can still take over for detailed adjustments when a specific frame, cut, or visual decision requires closer control.

    The Future of Frame-Level Video Editing

    AI is gradually changing frame-level editing from a process dominated by repetitive manual adjustments into one where editors can delegate more of the technical work.

    Object tracking, segmentation, removal, interpolation, cleanup, and timeline organization can increasingly be assisted by AI. As these systems become better at understanding motion and visual context, they should require fewer manual corrections.

    The role of the editor will still matter. AI can identify patterns and execute instructions quickly, but creative decisions about timing, storytelling, visual style, and quality remain human responsibilities.

    For creators working with large amounts of footage, the biggest advantage is simple: less time spent controlling individual frames and more time spent shaping the finished video.

  • Contractor Accounting Software: How to Choose the Right System

    If you run a contracting business you already know that simple bookkeeping is not enough. You must track money for each job. You often have three or four jobs at the same time. Each job has its budget, its own subcontractors and its own payment schedule.

    That is why contractor accounting software was created. Contractor accounting software is accounting software designed to match how construction really works. It uses jobs, cost codes, progress billing, retainage and payroll rules that normal small‑business tools never cover.

    This guide explains what contractor accounting software really does. It shows how contractor accounting software is different from accounting software such as QuickBooks or Xero.

    It also tells you which platforms are best, for which type of contractor and how to choose one without wasting six months on an implementation.

    Quick answer: Small contractors with jobs often do fine on QuickBooks or Xero with a few contractor‑focused add‑ons.

    Once contractors are managing active jobs, subcontractors, retainage or certified payroll purpose‑built construction accounting software such as Foundation, Sage 100 Contractor or Premier or a project‑accounting layer such, as Adaptive or Knowify usually pays for itself within a year by reducing billing errors and improving job‑cost visibility. 

    What Is Contractor Accounting Software?

    Contractor accounting software is accounting software built around projects instead of just company-wide totals. Every dollar gets tied to a specific job, so you can see whether that job is actually making money, not just whether your bank balance looks healthy.

    Regular accounting software answers “how is my business doing this month?” Contractor accounting software answers “how is this job doing right now, and what will it cost me to finish it?” That second question matters more in construction, where a business can look profitable on paper while individual jobs are quietly bleeding money.

    Wikipedia’s overview of construction accounting sums up why this field is treated as its own discipline: contractors typically recognize revenue using the percentage-of-completion method, tying earned revenue to the percentage of estimated total cost that’s actually been incurred. 

    That single accounting rule is the reason generic bookkeeping software struggles here: it usually has no concept of “percent complete” at all.

    1. How contractor accounting differs from regular accounting

    Contractor accounting comparison showing a single retail ledger versus multiple construction projects consolidated into one financial dashboard.

    A retail business has one ledger and one set of margins. A contractor effectively runs a separate mini-business inside every job, with its own budget, its own costs, and its own profit or loss.

    Contractor accounting software is built to roll all of those mini-businesses up into one clear picture without losing the job-level detail.

    2. What contractor accounting software actually manages

    At a working level, the software touches:

    • Jobs and cost codes
    • Labor, materials, and equipment costs
    • Subcontractor payments and compliance documents
    • Progress billing and retainage
    • Work-in-progress (WIP) reporting
    • Payroll, including certified and prevailing-wage payroll
    • Cash flow and job profitability

    Best Contractor Accounting Software in 2026

    Before naming names here is the methodology. Each platform below was evaluated on how deep the job costing’s on WIP reporting on payroll capability on billing tools, on how easy it is to set up and on how clear the vendor is about pricing. 

    Software prices change often so treat the numbers here as a starting point. Confirm current prices directly with each vendor. This comparison reflects listed information as of September 2026.

    No single platform is best, for every contractor. The honest answer depends on your size, your trade and how complex your payroll and billing already are.

    SoftwareBest forJob costingWIPPayrollConstruction billing
    QuickBooksSmall contractors, existing QuickBooks usersBasicLimitedAdd-onLimited
    XeroSmall service contractors, cloud-first teamsBasic-to-moderateLimitedVia add-onModerate
    AdaptiveMid-market contractors layering project accounting onto existing systemsStrongStrongDepends on integrationStrong
    Foundation SoftwareSpecialty and mid-size construction firmsStrongStrongStrong (certified payroll)Strong
    Sage Construction (Sage 100/300)Established contractors needing broad financial managementStrongStrongStrongStrong
    Premier Construction SoftwareGrowing contractors ready for an ERPAdvancedAdvancedAdvancedAdvanced

    1. QuickBooks

    QuickBooks contractor accounting software displayed on a laptop with construction tools, blueprints, financial charts, calculator, and accounting documents.

    QuickBooks (Online or Enterprise Contractor Edition) is the first choice for most small contractors. That’s mostly because your bookkeeper or CPA likely already uses it. 

    It does a job with tracking income and expenses by comparing estimates to actual results and preparing 1099 forms for subcontractors.

    It starts to fall short when you need certified payroll, manage multi-tier retainage or generate work-, in-progress reporting that meets bank or surety requirements. 

    If your annual revenue is moving past a million dollars or if you are bidding on public projects that require prevailing wage records you’ll probably outgrow what QuickBooks can do.

    2. Xero

    Xero focuses on cloud-based bookkeeping. It includes bank reconciliation, bills, tracking costs at the project level and a good mobile app. It works well for service and remodeling contractors who need simple project profitability without a hard learning curve.

    Xero does not have built-in construction payroll or advanced work in progress tools. So contractors who handle certified payroll or complicated progress billing usually need a construction- add-on or a different platform altogether.

    3. Adaptive

    Adaptive places itself as a project‑accounting layer that sits beside a company’s existing books. Adaptive links job costs, accounts payable, billing, work in progress and forecasts. Adaptive does this without requiring a rip‑and‑replace. 

    Adaptive makes a choice for mid‑market contractors who already have accounting processes they do not want to abandon but need clearer job‑level visibility. 

    4. Foundation Software

    Foundation is a construction-focused accounting system. It handles job costing, payroll, including payroll, invoicing accounts payable and accounts receivable general ledger and project management all in one place. 

    This system is a choice for specialty contractors and mid-size companies. They need construction accounting features. Don’t want to go all the way to a full ERP system. 

    5. Sage Construction

    Sage’s construction products include Sage 100 Contractor for companies and Sage 300 Construction and Real Estate for bigger ones. These products handle finance, compliance, job costing, payroll work in progress and field access. 

    It is an option for companies that have been around for a while and need full financial management. These companies also have the people to manage a more complicated system.

    6. Premier Construction Software

    Premier is built as a cloud-based construction ERP so its pricing, reporting and feature depth go beyond basic accounting. It includes project management and forecasting tools. 

    This makes it a good fit for growing contractors who have moved past the stage where simple accounting software can handle their day- to-day operations. 

    7. Other platforms worth knowing

    A handful of other names show up regularly in contractor accounting searches, each suited to a different niche: Procore Financials (financial tools bolted onto Procore’s project management platform), Acumatica Construction Edition (cloud ERP with strong customization), CMiC and Viewpoint Vista (enterprise-grade systems for large general contractors), Knowify (project accounting for small-to-mid trade contractors), Buildertrend (project management with construction-aware accounting features), and ComputerEase (construction accounting aimed at mechanical, electrical, and specialty trades).

    None of these need a full profile here. The point is knowing they exist and roughly who they’re for, so you can shortlist correctly before you start demos.

    Contractor Accounting Software vs. General Accounting Software

    This is the decision most contractors actually need help with, more than “which vendor is best.”

    General accounting software such as QuickBooks or Xero manages common bookkeeping tasks effectively, including creating invoices, tracking expenses, reconciling bank accounts and producing simple reports.

    For businesses that want to understand these fundamentals, this guide to bookkeeping explains how tasks such as bank reconciliation, payroll processing, and financial reporting fit into everyday financial management.

    When you require job costing divided into cost codes WIP schedules that a bank will accept, certified payroll for government contracts or multi-tier retainage tracking, across many active jobs General accounting software falls short. 

    A rough way to think about it:

    • General accounting software: fine for a solo contractor or a small crew running one or two jobs at a time with simple billing.
    • Construction accounting software: needed once you’re running several jobs simultaneously, using subcontractors regularly, or billing progressively against a contract.
    • Construction ERP: worth it once accounting, estimating, project management, procurement, and field operations all need to share the same data in real time.

    If you’re not sure which bucket you’re in, a useful gut check: can you tell right now, without pulling a report or calling your bookkeeper, whether your three biggest active jobs are on budget? If not, you’ve likely outgrown general accounting software regardless of your revenue size.

    What Features Should Contractor Accounting Software Have?

    1. Job costing

    Job costing dashboard showing construction project costs, budget tracking, financial charts, calculator, blueprints, hard hat, and home construction model.

    Job costing is about keeping track of every cost that happens during a job. This includes things like labor, materials people you hire to do part of the work and the machines or tools you use. It is all linked to the job that caused the cost. Then you compare those costs to the budget you set for that job.

    For example if a home renovation job has a budget of $30,000 for labor, $20,000 for materials, $15,000 for subcontractors and $5,000 for equipment, good job-costing software will show you how much you are actually spending in each of those areas. It doesn’t just show the total of $70,000.

    This is important because a job might go over budget in one area but still look okay when you look at the total. By the time you notice that problem, on your bank statement it could be too late to do anything about it.

    2. WIP accounting and reporting

    Work-in-progress (WIP) reporting compares what you’ve billed against what you’ve actually earned, based on percent complete. If you’ve billed more than you’ve earned, you’re “overbilled,” meaning you’re sitting on cash you haven’t technically earned yet, which can mask a cash-flow problem down the road. 

    If you’ve billed less than you’ve earned, you’re “underbilled,” meaning you’re financing the job out of pocket. Sureties and lenders look closely at WIP schedules, so software that generates them accurately is worth prioritizing if you do any bonded work.

    3. Progress billing and retainage

    Progress billing lets you invoice a percentage of the contract as work is completed, rather than waiting until the whole job is done. Retainage is the portion of each invoice, often 5% to 10%, that the client holds back until the project wraps up and passes final inspection. Software needs to track retainage separately from regular receivables, since it sits on your books differently and affects cash flow differently.

    4. Change orders

    A change order is any modification to the original contract: added scope, removed scope, or a price adjustment. Software should let you track a change order from proposal through client approval to final billing, and flag any work that’s happening on unapproved changes before it becomes a dispute.

    5. Accounts payable, accounts receivable, and subcontractor management

    Beyond standard AP/AR, contractor software should handle W-9 collection, 1099 preparation, lien waivers, and insurance certificate tracking for every subcontractor on a job. Skipping this is a common way contractors end up with compliance headaches at tax time or during an audit.

    6. Construction payroll

    Contractor payroll often isn’t simple hourly pay. Certified payroll (required on many public projects) demands weekly reporting in a specific federal format; prevailing wage rules set minimum pay by trade and location; union payroll adds fringe benefit calculations on top. Software that handles these natively saves real hours compared to managing them in spreadsheets.

    7. Mobile and field accounting

    Field crews need to log time, snap photos of receipts, and submit expenses from a job site, not from an office desk at the end of the week.

    Software with a solid mobile app keeps job costs current instead of two weeks behind, which matters a lot when you’re trying to catch a budget problem while there’s still time to fix it.

    8. Reporting, dashboards, and integrations

    Look for real-time dashboards showing job profitability and cash position. Accounting software with strong analytics can also help you monitor financial trends, create custom reports, and make better decisions, while integrations connect the system with estimating, project management, payroll, and banking tools

    How Contractor Accounting Software Works Across a Project

    This is where the mechanics come together, and it’s worth walking through end to end because it shows why job-based accounting is genuinely different from company-level bookkeeping.

    1. Estimate the job and build a budget broken into cost codes (labor, materials, subs, equipment, permits).
    2. Set up the job in the software with those cost codes attached.
    3. Track labor and materials as they’re spent, coded to the right job and cost code.
    4. Issue purchase orders and subcontracts, so committed costs show up before the invoice even arrives.
    5. Capture vendor invoices and expenses, matched against the right PO or subcontract.
    6. Bill progressively against the contract as work is completed.
    7. Track retainage and change orders as they happen, not after the fact.
    8. Generate WIP reports comparing billed, earned, and costs incurred.
    9. Compare actual costs to the original budget to catch overruns early.
    10. Measure final profitability once the job closes, and feed that data into your next estimate.

    A residential remodeler with three active jobs and a $50M general contractor with forty follow roughly the same sequence. The scale and the compliance requirements differ, but the workflow itself doesn’t change much.

    Choosing Software by Business Size and Contractor Type

    Rather than a long list of trade-by-trade recommendations, here’s the pattern that actually holds up across contractor types.

    Solo contractors and very small crews usually do fine with general accounting software plus simple invoicing and expense tools. The job complexity doesn’t justify a construction-specific platform yet.

    Small contractors running a handful of jobs at once: this is where QuickBooks or Xero with project tracking, or an entry-level construction package like Sage 100 Contractor, tends to fit.

    Growing contractors juggling multiple crews, subcontractors, and progress billing usually need a purpose-built construction accounting platform like Foundation, Sage, or a project-accounting layer like Adaptive or Knowify.

    Mid-market and enterprise contractors running multiple entities, bonded public work, or complex payroll (certified, prevailing wage, union) tend to need either a full construction ERP like Premier or Acumatica, or an enterprise system like Viewpoint Vista or CMiC.

    Contractors managing multiple entities can also benefit from understanding how accounting software for multiple businesses handles separate financial data while keeping reporting and integrations organized.

    Trade matters less than most software marketing suggests. An electrical contractor and a roofing contractor with similar revenue and similar payroll complexity will usually shortlist the same tier of software. The differences that matter are job count, subcontractor volume, payroll type, and whether you’re bidding public work, not the trade itself.

    How Much Does Contractor Accounting Software Cost?

    Sticker price is the smallest part of the real cost. A fuller picture includes:

    • Subscription or license fees: ranges widely, from roughly $30–$90/month for QuickBooks or Xero plans up to custom enterprise pricing for Sage, Foundation, or Premier that’s quoted per company.
    • Implementation and data migration: moving historical job data and chart of accounts into a new system, which can take weeks for a construction-specific platform.
    • Training: construction accounting software has a real learning curve for cost codes, WIP, and job setup.
    • Integrations: connecting payroll, estimating, or project management tools sometimes carries its own fees.
    • Payroll and payment processing: often billed separately, especially for certified payroll modules.
    • Ongoing support: some vendors include it, others charge extra for priority support.

    Construction ERP software costs more than general accounting software mainly because you’re paying for the compliance and reporting depth (certified payroll, multi-tier WIP, bonding-ready financials) that generic tools were never built to handle.

    A contractor group discussion on r/Construction is a decent gut-check on this: you’ll find plenty of contractors describing the jump from QuickBooks to a construction-specific system as expensive up front but worth it once job costing stopped being guesswork.

    How to Choose the Right Contractor Accounting Software

    1. Define your company size and project complexity. How many active jobs run at once, and how big are they?
    2. Document your current accounting workflow. Know what’s broken before you shop for a fix.
    3. List your required construction features. Job costing, WIP, retainage, certified payroll: rank them by how painful the gap is today.
    4. Review payroll and compliance needs. Public work changes the requirements significantly.
    5. Check integrations with your estimating, project management, and payroll tools.
    6. Compare reporting capability, especially WIP reports if you deal with sureties or lenders.
    7. Calculate total cost of ownership, not just the monthly subscription.
    8. Test the software with a real project, not a demo sandbox with fake data.
    9. Evaluate implementation and training support.
    10. Check data security, backups, and export options before you commit.

    Contractor Accounting Software Demo Checklist

    Bring these questions into every vendor demo:

    • Can you show me a real job-costing example with cost codes, not just totals?
    • What does your WIP report actually look like, and can a surety or bank read it?
    • How is certified payroll handled, and does it generate the required federal forms?
    • Can this integrate with [your estimating/project management/payroll tool]?
    • What does implementation actually involve, and how long does it typically take for a company our size?
    • Is pricing based on users, modules, revenue, or something else?
    • What happens to our data if we cancel? Can we export everything cleanly?

    Common Contractor Accounting Mistakes Software Can Help Prevent

    • Mixing job costs with overhead, which makes every job look more profitable than it actually is.
    • Delayed cost coding, so budget overruns aren’t visible until the job’s nearly done.
    • Missed or unapproved change orders, a frequent source of billing disputes.
    • Sloppy progress billing, leading to over- or under-billing without anyone noticing.
    • Poor retainage tracking, which quietly distorts cash flow.
    • Stale WIP data, which undermines credibility with lenders and sureties.
    • Payroll compliance errors, especially on certified payroll or prevailing wage jobs.
    • No visibility into job-level profitability until the job is already closed and it’s too late to course-correct.

    How AI Is Changing Contractor Accounting Software

    AI features are showing up across most of the platforms named above, mostly in a few practical spots:

    • Automated invoice data extraction: pulling line items off a vendor invoice instead of manual entry.
    • AI-assisted cost coding: suggesting the right job and cost code based on invoice content and history.
    • Exception detection: flagging a cost or invoice that looks out of pattern for a given job.
    • Cash-flow forecasting: projecting cash position based on current WIP and committed costs.
    • AI-assisted WIP analysis: surfacing jobs that look over- or under-billed before it becomes a real problem.

    None of this replaces a controller’s judgment. AI can speed up repetitive data entry and flag anomalies, but approvals, financial controls, and the final call on a WIP schedule still need a person who understands the job and the client relationship.

    Contractor Accounting Software Implementation Guide

    Rolling out new software takes longer than most contractors expect, mostly because of data migration and chart-of-accounts setup, not the software itself.

    • Migrate historical data: decide how far back you actually need job history, rather than dragging over everything.
    • Rebuild your chart of accounts and cost codes to match how the new system organizes things, not just copy the old structure.
    • Connect integrations: payroll, estimating, banking.
    • Set user permissions so field staff, project managers, and accounting see only what they need.
    • Train the team, especially anyone entering costs from the field.
    • Run a parallel test on a live job before fully switching over.
    • Go live, then review after 30–60 days to catch setup mistakes before they compound.

    Frequently Asked Questions

    What is contractor accounting software? 

    It’s accounting software built to track costs, billing, and profitability at the individual job level, rather than just at the company level, with features like job costing, WIP reporting, and construction-specific payroll.

    What is the best accounting software for contractors? 

    There isn’t one universal answer. QuickBooks and Xero suit small contractors with simple jobs, while Foundation, Sage, and Premier fit contractors needing deeper job costing, WIP, and certified payroll.

    Is QuickBooks good for contractors? 

    Yes, for small contractors and businesses already using QuickBooks. It handles job-level tracking and basic reporting well but has real limits on WIP reporting and certified payroll as a company scales.

    Is Xero good for construction companies? 

    Xero works well for smaller, cloud-first service and remodeling contractors who want clean project-cost tracking without the complexity of a full construction ERP.

    Do small contractors need construction-specific accounting software? 

    Not always. A solo contractor or small crew running one or two jobs at a time can usually manage on general accounting software with project tracking turned on.

    Conclusion

    There’s no one choice here and any article that gives you just one is missing the part that really counts: your job complexity, payroll needs and plans for growing.

    As a starting point: a small contractor doing jobs is usually okay with QuickBooks or Xero. A contractor who is growing and handling jobs and subcontractors needs a construction accounting system like Foundation or Sage.

    A contractor who works in a specialty area and has a lot of payroll rules needs help with certified payroll more than nice charts and graphs. A mid-market contractor who wants job tracking with the systems they already use is a good match for Adaptive or Knowify.

    A big contractor or one that works on projects or has many companies under one roof is better off with a full construction ERP, like Premier, Acumatica or Viewpoint Vista.

    No matter which way you go, use the demo checklist above with job data before you make a decision. The right contractor accounting software should show you on any day, where every active job is, not just what your bank account looked like last month.

  • B2B eCommerce Integration Challenges: ERP, PIM and DAM Explained Simply

    B2B eCommerce Integration Challenges: ERP, PIM and DAM Explained Simply

    Most B2B buyers now expect the same speed and clarity they get from consumer shopping sites, but the systems running behind a wholesale or manufacturing storefront rarely make that easy.

    Product data lives in an ERP, images and spec sheets sit in shared drives, and pricing rules change by customer tier. Every serious b2b ecommerce store development project eventually runs into the same question: how do we get these systems to talk to each other without breaking daily operations?

    That question usually comes down to three platforms: ERP, PIM, and DAM. Each does a specific job, and B2B integration problems almost always trace back to how these three interact, or fail to.

    ERP: The System of Record for the Business

    An Enterprise Resource Planning system handles the operational backbone: inventory levels, order processing, pricing, invoicing, and financials. For most B2B companies, the ERP has been in place for years and holds data that the rest of the business depends on to run.

    The trouble starts when a company tries to expose ERP data to a storefront. ERPs were built for internal operations, not for public-facing web pages. Fields are often coded in ways only internal staff understand, product descriptions are minimal or missing, and the system was never designed to sync in real time with a website that customers are actively browsing.

    PIM: Where Product Data Gets Organized

    A Product Information Management system exists to solve the gap the ERP leaves behind. It centralizes product attributes, descriptions, categories, and specifications in one governed location, then distributes that information consistently across the website, marketplaces, and sales channels.

    This matters most for companies with large or technical catalogs, distributors, manufacturers, and industrial suppliers among them, where a single product might carry dozens of attributes, multiple compliance documents, and regional variations. Platforms built for this, such as those delivered through dedicated Pimcore development services, give teams a structured way to manage that complexity instead of maintaining parallel spreadsheets that fall out of sync within weeks.

    Without a PIM layer, product data tends to live in whichever system touched it last. Marketing edits descriptions in one place, sales updates specs in another, and the storefront ends up displaying whatever version happened to sync most recently. Customers notice the inconsistency before anyone internally does.

    DAM: Managing the Assets Behind the Data

    Digital Asset Management handles the media side of the equation: product photography, technical drawings, installation guides, certifications, and marketing files. For B2B sellers with large or regulated catalogs, this library can run into the tens of thousands of files, and version control quickly becomes a real problem.

    A DAM system gives every asset a single source of truth, complete with metadata, approval status, and usage rights. Without one, teams end up emailing files back and forth, uploading outdated spec sheets, or duplicating the same image across a dozen folders with slightly different file names. When a product changes, there is no reliable way to know which files are current.

    Why Integration Is Harder Than It Looks

    Each system on its own is manageable. The difficulty appears when ERP, PIM, and DAM need to function as one connected pipeline, feeding accurate, current information to a storefront that customers are actively using to place orders. A few patterns show up repeatedly:

    • Data ownership disputes. Sales, marketing, and operations each treat a different system as the source of truth, and nobody agrees on which record wins when they conflict.
    • One-way syncs. Data flows from ERP to the website, but updates made on the storefront never make it back, creating a permanent gap between systems.
    • Manual re-entry. Without proper integration, staff copies data between systems by hand, which introduces errors and does not scale as the catalog grows.
    • Inconsistent formats. ERPs, PIMs, and DAMs rarely share a common data structure out of the box, so integration requires mapping and transformation work that is easy to underestimate.
    • Real-time expectations versus batch systems. Customers expect live inventory and pricing, but many legacy ERPs were only ever designed to update in scheduled batches.

    The pressure to solve these problems is not theoretical. Forrester projected that by 2025, more than half of large B2B purchases worth $1 million or more would move through digital self-serve channels such as vendor websites and marketplaces, according to Virto Commerce’s analysis of PIM and ecommerce architecture. That kind of buying behavior leaves little room for a storefront running on stale or incomplete data, since a buyer placing a seven-figure order rarely tolerates a wrong price or an out-of-stock item that was actually available.

    What a Working Integration Actually Looks Like

    Solving this is less about picking the right software and more about establishing a clear data flow with defined ownership at each step. A few principles hold up across most successful projects.

    For organizations managing complex product catalogs, dedicated Pimcore development services can help establish a more structured approach to product information, digital assets, and connected commerce workflows. 

    Treat the ERP as the source of truth for transactional data. Inventory, pricing, and order status should flow from the ERP outward, not be re-entered manually on the storefront.

    Let the PIM own product content. Descriptions, categories, and specifications should be created and approved once, then pushed everywhere they are needed, rather than edited separately in five different places.

    Connect the DAM at the attribute level. Images and documents should be linked directly to the product records they describe, so a single update propagates automatically instead of requiring someone to hunt down every reference.

    Build with APIs, not exports. Scheduled CSV exports and manual uploads might work for a pilot, but they break down quickly at scale. API based integration keeps systems synchronized without constant manual intervention.

    Phase the rollout. Attempting to connect all three systems at once, across every product category, is where most integration projects stall. Starting with a single product line or region, proving the workflow, and expanding from there tends to produce more durable results.

    This shift toward connected, self-serve buying experiences is accelerating. Gartner’s 2025 Magic Quadrant research found the digital commerce market reached $10.2 billion in 2024, growing 14 percent year over year, and the firm expects most B2B organizations to complete their highest value deals through digital channels within the next few years, as summarized by Business Central consultancy TINX IT. Businesses still relying on manual data handoffs between ERP, PIM, and DAM will find that gap increasingly difficult to close as buyer expectations rise.

    Bringing It Together

    None of this requires replacing existing systems. Most B2B companies already have a capable ERP and, in many cases, source data scattered across DAM like folders and spreadsheets that could be consolidated. The real work is in architecture: deciding what data lives where, how it moves, and who owns each step of that journey.

    Getting ERP, PIM, and DAM to function as a single, reliable pipeline is what separates a storefront that customers trust from one that quietly loses orders to inconsistent product pages and outdated inventory counts. Companies that treat this as foundational infrastructure, rather than a one-time technical project, tend to scale their catalogs and channels with far less friction.

    For businesses evaluating where to start, Magneto IT Solutions works with manufacturers, distributors, and B2B sellers to map out ERP, PIM, and DAM architecture before writing a single line of integration code, which tends to save both time and budget down the line.

  • AVS Mismatch: What It Means, Why It Happens, and How to Fix It

    AVS Mismatch: What It Means, Why It Happens, and How to Fix It

    If your card just got declined and the error message mentioned “AVS,” you’re probably staring at your screen wondering what you did wrong. Short answer: probably nothing. An AVS mismatch happens when the billing address you entered doesn’t line up with the address your card issuer has on file. It doesn’t automatically mean fraud, and it doesn’t always mean your payment failed for good.

    This guide walks through what an AVS mismatch actually is, why it happens even when you’re sure you typed your address correctly, what happens to your money afterward, and what both shoppers and merchants can do about it.

    Quick answer: An AVS mismatch occurs when the billing address submitted during a card payment doesn’t match what the card issuer has on record. Depending on the merchant’s fraud settings, this can trigger a decline, a manual review, or in some cases get waved through anyway.

    What Is an AVS Mismatch?

    1. What does AVS stand for?

    Diagram illustrating how an online checkout address is verified through a payment gateway and secure datacenter to determine transaction status match.

    AVS stands for Address Verification Service (sometimes called Address Verification System). It’s a check that compares the numeric parts of the billing address you enter at checkout,  usually the street number and ZIP or postal code,  against the address the card issuer has on file for that account.

    2. How Address Verification Service works

    Here’s the path a payment actually takes, which most explanations skip over:

    Customer enters card details → Merchant’s checkout page → Payment gateway/processor → Card network (Visa, Mastercard, etc.) → Issuing bank → AVS response comes back → Gateway applies the merchant’s rules → Payment is approved, flagged for review, or declined.

    For a broader look at how payment processors work and what businesses should consider when choosing one, see our guide to payment processing options.

    The issuing bank is the one that actually runs the address check. It sends back a response code, and it’s the merchant’s payment gateway that decides what to do with that code. Two shoppers with the exact same “mismatch” can get completely different outcomes depending on which store they’re buying from, because each merchant sets its own risk tolerance.

    3. What information does AVS check?

    AVS typically only looks at:

    • The numeric portion of the street address (not the street name)
    • The ZIP or postal code

    It usually ignores things like apartment numbers, city, and state, which is part of why the system produces so many false mismatches. It’s a blunt tool, not a precise one.

    4. What does an AVS mismatch mean?

    An AVS mismatch means the numbers you entered didn’t match what the bank has on record. That’s it. It says nothing on its own about whether you’re the legitimate cardholder — it’s one data point that a merchant’s fraud system weighs alongside others.

    Does an AVS Mismatch Mean Your Card Was Declined?

    Not necessarily. This is where a lot of confusion comes from, because AVS results and payment declines aren’t the same thing.

    1. Why an AVS mismatch can cause a declined payment

    A conceptual diagram showing how different merchants handle AVS mismatch codes, leading to either an automatic decline or a manual review.

    Some merchants set their systems to auto-decline any transaction with even a partial address mismatch. Others only decline a full “no match,” and treat a partial match as something to flag for manual review instead. The AVS code itself doesn’t decide anything — the merchant’s rules do.

    2. Can a payment succeed despite an AVS mismatch?

    Yes, and this happens more often than people expect. WooCommerce’s own documentation on Stripe payments notes that a charge can go through successfully even when AVS or CVC checks come back as a mismatch, because the issuing bank’s authorization decision and the AVS result are handled as separate signals. A merchant can choose to accept the charge anyway if other risk indicators look fine.

    3. Who actually decides whether to approve or decline?

    Four parties are involved, and it’s worth keeping them straight:

    1. The issuing bank generates the AVS response.
    2. The card network passes that response along.
    3. The payment gateway applies the merchant’s configured rules to it.
    4. The merchant ultimately owns the final call on how strict those rules are.

    If you’re a customer, this explains why the same billing info can work fine on one site and fail on another.

    Why Does an AVS Mismatch Happen?

    Most of the time it’s nothing sinister. Here are the usual suspects.

    Incorrect billing address. A typo in the street number is the single most common cause. Easy to do on a phone keyboard.

    Wrong ZIP or postal code. Even one digit off will trigger a mismatch, since AVS checks numbers exactly.

    Recently changed address. If you moved and updated your address with the postal service or your landlord, that doesn’t automatically update your bank’s records. Card issuers usually need you to contact them directly.

    Bank records haven’t been updated. Sometimes you did notify your bank, but their system hasn’t synced the change yet. This can take a billing cycle or two depending on the issuer.

    Address formatting differences. “123 Main St Apt 4” versus “123 Main Street #4” can occasionally trip up stricter AVS implementations, though this affects the street-name portion less than you’d think since AVS mostly checks numbers.

    Apartment, suite, or unit numbers. Ironically, since most AVS checks ignore unit numbers entirely, entering or omitting them usually isn’t the actual problem — but people often assume it is and waste time troubleshooting the wrong field.

    Browser autofill entered an old address. This one catches a lot of people. Autofill can silently pull in a saved address from years ago.

    International address formats. AVS was built around the US and, to a lesser degree, Canadian and UK address structures. Many other countries don’t have equivalent postal-code granularity, so AVS often can’t return a meaningful result at all.

    Prepaid and gift cards. These frequently aren’t linked to a verified billing address in the issuer’s system, so AVS checks on them are unreliable by design.

    Corporate and business cards. Company cards are sometimes registered to a corporate office address rather than the employee’s own address, which trips up AVS if the employee enters their personal details.

    Recurring or card-on-file payments. If you update your address with the merchant but not with your bank (or vice versa), a subscription renewal can suddenly start failing AVS even though nothing about the card changed.

    How to Fix an AVS Mismatch as a Customer

    If your payment just got flagged, work through these in order.

    1. Check your billing address. Compare it character by character against your card statement, not against what you assume it should be.
    2. Verify your ZIP or postal code. This is the single field most likely to be wrong.
    3. Match your bank’s records exactly. If you moved recently, your bank’s file may still show the old address, use that one at checkout, not your new one, until you’ve formally updated it with them.
    4. Turn off outdated browser autofill. Clear the saved address and type it fresh.
    5. Retry the payment. A simple retry with corrected info resolves most cases.
    6. Contact your card issuer. If everything you’re entering is genuinely correct, call the number on the back of your card and ask them to confirm what address is on file.
    7. Try another payment method. PayPal, a different card, or bank transfer can get you unstuck while you sort out the address issue.

    When to contact the merchant: if the payment keeps failing after you’ve confirmed the address is correct, or if you were charged despite the decline message.

    When to contact your bank: if you suspect your address on file is outdated, or if you don’t recognize why AVS would be failing at all.

    What Happens to Your Money After an AVS Decline?

    This is usually the most urgent question, so let’s deal with it directly.

    1. Authorization hold vs. completed charge

    A card payment isn’t one single event,  it’s typically an authorization first, then a separate capture. An AVS-related decline usually happens at the authorization stage, before any money actually moves. What you often see is a temporary hold, not a completed charge.

    2. Why a declined payment may show as pending

    Banks place a hold to check whether funds are available, and that hold can appear on your account or app before the transaction is fully resolved. Even if the transaction is ultimately declined, the hold can take a little while to clear from your visible balance.

    3. How long can the hold take to disappear?

    There’s no single universal number here, and any article that gives you one is guessing. Support documentation from Authorize.net-based platforms, such as 4aGoodCause’s help center, mentions holds typically clearing within a few business days on their setup — but the actual timeframe depends on your specific bank and the merchant’s processor, so treat any figure you read as a rough guide, not a guarantee.

    4. What to do if the money hasn’t been released

    If a hold is still sitting on your account well past what your bank considers normal, call your bank directly. They can see the authorization on their end and tell you the expected release date, which the merchant usually can’t do for you.

    AVS Response Codes Explained

    Card issuers return a short response code alongside the AVS check. Here’s the catch worth flagging up front: these codes aren’t fully standardized. Meanings can shift slightly depending on the card network and processor, so treat the table below as a general guide rather than gospel.

    CodeMatch resultWhat it generally meansSuggested action
    YFull matchStreet number and ZIP both matchApprove
    XFull matchExact match including extended ZIPApprove
    APartial matchStreet number matches, ZIP doesn’tReview
    ZPartial matchZIP matches, street number doesn’tReview
    NNo matchNeither street number nor ZIP matchesDecline or review
    RRetrySystem couldn’t process the checkRetry the request
    UUnavailableIssuer doesn’t support AVSRely on other checks
    GInternational issuerNon-US card, AVS not supportedUse alternative verification

    If you’re a developer working with a specific processor, check that processor’s own documentation for the exact codes they return. Stripe, for example, publishes its own address-verification explanation with its specific code set — worth a direct read if you’re troubleshooting a Stripe integration.

    AVS Mismatch vs. Other Payment Verification Checks

    AVS is one piece of a bigger fraud-prevention puzzle, not the whole thing. Businesses should also consider broader Data Privacy and Compliance and data-protection practices when handling customer transactions.

    Security checkPrimarily verifies
    AVSBilling address (street number + ZIP)
    CVV/CVCThe 3-4 digit code proving you physically hold the card
    3D SecureCardholder identity, often via a bank app prompt or SMS code
    IP/geolocationWhether the transaction location looks consistent with the cardholder

    AVS and CVV get confused constantly because they often fail together, but they check completely different things. AVS looks at where you supposedly live. CVV checks whether you’re holding the physical card. A stolen card number without the physical card can pass AVS (if the thief has your address) but fail CVV.

    AVS Mismatch Doesn’t Always Mean Fraud

    Three diverse, legitimate credit card users—a traveler with luggage, a business professional, and an international traveler—looking at their smartphones with subtle red error icons floating nearby, representing false payment declines without using any text.

    This is worth stating plainly: a failed AVS check is not proof of fraud, and a passed AVS check is not proof of a legitimate transaction.

    1. Why legitimate customers fail AVS

    Someone who just moved, someone using a company card, someone paying from abroad, none of these people are doing anything wrong, yet all three are likely to trip AVS.

    2. Why fraudulent transactions can still pass AVS

    If a fraudster has stolen someone’s card details along with their billing address (which happens constantly in data breaches), AVS will return a full match. The check only confirms the address matches records,  it says nothing about who’s actually typing it in.

    3. Why AVS should be one part of a fraud-prevention strategy

    Relying on AVS alone means blocking real customers while letting through fraud committed by anyone with stolen address data. A stronger setup layers AVS with CVV checks, 3D Secure, device fingerprinting, and velocity checks (flagging unusual numbers of attempts in a short window).

    Payment security discussions on r/ecommerce and similar communities frequently make this same point from the merchant side, AVS alone is a weak filter, and treating it as a hard gate tends to cost more in lost sales than it saves in blocked fraud.

    How Merchants Should Handle AVS Mismatches

    If you’re running the checkout rather than clicking through it, here’s the practical framework. For a broader look at improving ecommerce websites, checkout experiences, and search visibility, see our Ecommerce SEO Checklist.

    Don’t automatically decline every mismatch. A blanket “decline on any AVS issue” rule is the single biggest cause of false declines, and false declines cost you real revenue from real customers.

    Build risk-based rules instead of all-or-nothing ones. Full matches auto-approve. Partial matches go to manual review or get combined with a CVV check before deciding. Full no-matches get declined or heavily scrutinized, especially on high-value orders.

    Write customer-friendly decline messages. “Your payment couldn’t be processed, please verify your billing address matches your card statement” is more useful, and generates fewer support tickets, than a generic “transaction declined.”

    Offer an alternative payment method at the point of failure. If AVS keeps blocking a genuine customer, letting them switch to PayPal or another method on the spot saves the sale.

    How to Reduce False AVS Declines

    A few concrete things merchants can do beyond adjusting the AVS threshold itself:

    • Validate addresses at the point of entry (before submitting for authorization), using an address-autocomplete service, so typos get caught before they ever reach the payment processor.
    • Keep billing and shipping address fields clearly separate in your checkout form, conflating them is a common source of mismatches.
    • Build a separate, more lenient rule set for international customers, since AVS coverage outside the US is inconsistent at best.
    • Treat prepaid and gift cards differently in your fraud rules, since AVS on these is inherently unreliable.
    • Use network tokenization for recurring billing so a customer’s expired or reissued card doesn’t silently break both the charge and the AVS check at once.
    • Combine AVS with CVV and 3D Secure rather than leaning on AVS by itself.
    • Track your approval rate against your false-decline rate over time,  if declines are climbing without a corresponding drop in chargebacks, your AVS rules are probably too strict.

    AVS Problems With International Payments

    AVS was designed around the US postal system, and it shows.

    Canada has a workable but different postal-code format, so match rates there are decent but not identical to the US. The UK’s alphanumeric postcodes work reasonably well with most implementations.

    Beyond those three countries, though, AVS support drops off fast, many national card networks and issuing banks simply don’t return a usable AVS response, which is where you’ll see code U (unavailable) or G (international issuer, unsupported) show up.

    For merchants selling internationally, this means leaning more heavily on CVV and 3D Secure for non-US, non-Canada, non-UK customers, since AVS isn’t giving you much signal to work with there anyway.

    AVS Mismatch by Payment Scenario

    The same underlying check plays out differently depending on what you’re buying.

    Ecommerce purchases are the classic case, AVS runs once, at checkout, against a billing address the shopper enters fresh.

    Subscriptions and recurring billing are trickier, since the address check that passed on day one can start failing months later if the cardholder moves or the card gets reissued, without the subscriber realizing why their renewal suddenly bounced.

    Travel and hospitality bookings often involve cards from a different country than where the purchase is being made, which is exactly the scenario where AVS is weakest.

    Restaurants and delivery apps sometimes see mismatches simply because the customer is ordering to a work address or a friend’s place rather than their own billing address,  a shipping-address mismatch, not a real problem.

    B2B and corporate cards frequently fail AVS because the card is registered to a company office rather than the individual making the purchase.

    Donations and nonprofit payments tend to be one-off, often from first-time donors on unfamiliar devices, which is part of why organizations like 4aGoodCause see enough AVS-related holds to publish dedicated help documentation on the topic.

    What Does “Gateway Rejected: AVS” Mean?

    If you’re a merchant and you see this specific message in your payment logs, it means the bank’s AVS response came back fine (or the issuer didn’t even flag it), but your own gateway’s configured filter rejected the transaction anyway based on rules you or your platform set.

    This is a configuration issue on your end, not a bank-level decline. Check your gateway’s AVS filter settings (most platforms, including Authorize.net and Stripe, let you adjust exactly which AVS codes trigger a rejection) and loosen them if you’re seeing this too often on transactions that otherwise look legitimate.

    Can You Disable or Bypass AVS?

    Can customers bypass AVS? No, this isn’t something a shopper controls. If your payment fails AVS, your only real options are the fixes covered earlier in this guide.

    Can merchants ignore an AVS mismatch? Yes, technically. Most gateways let merchants turn AVS checking off entirely or set it to advisory-only, where a mismatch is logged but never blocks the sale.

    Why disabling strict AVS rules can increase risk. Turning AVS off completely removes one layer of fraud screening, which can increase chargeback exposure, especially for merchants in card-not-present categories that carry higher fraud rates by default.

    Better alternatives to completely disabling AVS. Loosen the rules instead of removing them, auto-approve partial matches paired with a passing CVV check, for instance, rather than switching AVS off altogether.

    AVS Mismatch Troubleshooting Checklist

    Customer checklist

    • Billing address matches bank records exactly
    • ZIP or postal code is correct
    • No outdated autofill data
    • Recent address changes have been reported to the bank
    • Payment has been retried after corrections
    • Card issuer has been contacted if the address is confirmed correct
    • Alternative payment method tried if needed

    Merchant checklist

    • AVS response code reviewed for the failed transaction
    • Gateway-level AVS filter settings checked
    • Processor-level AVS configuration checked
    • Additional fraud signals (CVV, 3DS, velocity) reviewed alongside AVS
    • International customer status considered before declining
    • False-decline rate monitored over time
    • Rule changes tested before rolling out broadly
    • Approval rate tracked after any rule adjustment

    Frequently Asked Questions About AVS Mismatch

    What does AVS mismatch mean? 

    It means the billing address entered at checkout doesn’t match the address the card issuer has on file, based on the street number and ZIP/postal code.

    How do I fix an AVS mismatch? 

    Double-check your billing address and ZIP code against your card statement, clear outdated autofill data, and retry the payment. If it still fails, contact your card issuer to confirm what address they have on record.

    Why does AVS fail when my address is correct? 

    Usually because your bank’s records haven’t been updated yet, even if you’ve moved and updated your address elsewhere. Use the address your bank has on file, not your new one, until the bank confirms the update.

    Does an AVS mismatch mean fraud? 

    No. It’s one risk signal among several, and plenty of legitimate transactions fail AVS for mundane reasons like a recent move or an international card.

    Does an AVS mismatch mean my card was declined? 

    Not always. Some merchants decline on any mismatch, others only flag partial matches for review and still approve the charge.

    Will an AVS decline charge my card? 

    Usually not a completed charge,  more often a temporary authorization hold that clears on its own within a few business days, though the exact timing depends on your bank.

    Conclusion

    An AVS mismatch means the billing information you submitted doesn’t match the information your card issuer has on file, nothing more, nothing less. It doesn’t automatically mean fraud, and it doesn’t necessarily mean your payment can’t go through. 

    Sometimes the mismatch is caused by something as simple as an outdated address, a missing apartment number, or entering a ZIP code that differs from the one linked to your card.

    If you’re a customer, double-check your billing address and ZIP code against your bank or card statement before assuming something is seriously wrong.

    If the information is correct and the payment still fails, contacting your card issuer or trying another payment method may help.

    If you’re a merchant, treat an AVS mismatch as one risk signal among several rather than an automatic yes-or-no decision. A mismatch can be worth investigating, especially when combined with other warning signs, but blocking every transaction with an AVS mismatch can also reject legitimate customers. 

    The goal is to balance fraud prevention with a smooth checkout experience, so your AVS rules should fit your overall risk strategy rather than acting as the only line of defense.

  • Will AI Replace Accountants? What the Future of Accounting Actually Looks Like

    Will AI Replace Accountants? What the Future of Accounting Actually Looks Like

    AI is not going to eliminate accountants as a profession. But it is already automating a growing share of the routine work that used to fill an accountant’s day. That shift is the real story, and it’s more interesting than a simple yes-or-no answer.

    The short version: AI is much better at replacing accounting tasks than it is at replacing the accountant who reviews, interprets, and takes responsibility for the results. Data entry, reconciliation, and basic reporting are already being automated at scale. 

    Judgment, tax strategy, audit sign-off, and client advice are not,  at least not yet, and arguably not for a long time.

    If you’re asking whether AI will replace accountants, the honest answer has two parts: some accounting jobs will shrink, and the accountant’s role will change substantially. Neither of those things means the profession disappears.

    Will AI Replace Accountants? The Short Answer

    No, not the profession as a whole. AI is automating specific tasks inside accounting (data entry, categorization, reconciliation, first-draft reporting), but it can’t yet take on professional judgment, regulatory accountability, or client trust. Those are still human jobs, and they’re likely to stay that way for the foreseeable future.

    That said, this isn’t a comforting “nothing will change” answer either. Routine, entry-level accounting work is genuinely exposed to automation, and firms are already restructuring around that fact.

    AI is replacing tasks, not the whole job

    An accountant sitting at a desk in a modern, open-plan office, engaged in a face-to-face strategic conversation with two clients. On her desk are financial charts and paper documents, while dual computer monitors in the background display automated AI dashboards showing data analytics, transaction categorization, and progress graphs.

    Every accounting role is really a bundle of tasks. Some of those tasks, matching invoices, categorizing transactions, flagging duplicate payments, are repetitive and rule-based, which is exactly what AI is good at.

    Other tasks, deciding how to treat an ambiguous transaction, explaining a tax position to a client, signing off on an audit opinion, require context, accountability, and judgment that current AI systems don’t have.

    When people say “AI will replace accountants,” they’re usually picturing the first bucket of tasks disappearing. What actually happens is that those tasks get automated, and the accountant’s job shifts toward the second bucket.

    Why the answer isn’t a flat “no”

    It would be easy to write a reassuring article that just says accountants are safe. That wouldn’t be accurate. Bookkeeping-heavy and entry-level roles are already shrinking at some firms as AI tools take over reconciliation and data entry. The profession isn’t vanishing, but the shape of it is changing, and some jobs really are at risk.

    Why People Think AI Will Replace Accountants

    A few things make this question feel more urgent than it did five years ago.

    Accounting has always had a large share of repetitive, rules-based work,  the kind of work that’s easy to describe as “if X happens, do Y.” That makes it a natural target for automation, and software vendors have been chipping away at it for over a decade with optical character recognition, robotic process automation, and now generative AI.

    Generative AI adds a new layer on top of that. It can draft financial summaries, write memo-style explanations of variances, and answer plain-English questions about a dataset, things that used to require a person sitting down and writing. That’s a bigger leap than older automation tools, which could only follow fixed rules.

    Entry-level accounting work is particularly exposed because it’s disproportionately made up of the tasks AI handles well: data entry, basic reconciliation, and first-pass categorization. That’s the part of the job most likely to shrink first.

    What Accounting Tasks Can AI Automate?

    A split-concept workspace depicting the division between automated accounting and human advisory. On the left, robotic arms and glowing futuristic holographic interfaces process receipts, sort digital documents, and handle repetitive data entry. On the right, a female accountant sits at a conference desk, actively reviewing papers and consulting in-person with two male corporate clients in a modern high-rise office.

    Here’s a practical breakdown of where AI is strong, where it’s a useful assistant, and where it still needs heavy human oversight.

    Accounting taskAI automation potentialHuman involvement needed
    Data entryVery highLow — spot checks
    Invoice processingVery highException handling
    Transaction categorizationHighReview edge cases
    Bank reconciliationHighInvestigate mismatches
    Expense managementHighApprove exceptions
    Financial reporting (first draft)MediumHigh — interpretation
    Cash-flow forecastingMediumHigh — assumptions and judgment
    Tax researchMediumHigh — application to facts
    Tax strategyLow to mediumVery high
    Audit judgmentLow to mediumVery high
    Client advisoryLowVery high
    Strategic planningLowVery high

    A useful way to think about this: AI is strongest on tasks with clear rules and lots of historical data to learn from. AI-powered accounting software can automate areas such as invoice processing, expense categorization, forecasting, and reconciliation. It’s weakest on tasks that require weighing incomplete information, understanding a client’s specific situation, or taking legal responsibility for a conclusion.

    What AI Cannot Easily Replace in Accounting

    Several parts of the job don’t reduce to pattern matching, no matter how good the underlying model gets.

    Professional judgment. Deciding how to classify an unusual transaction, or whether a client’s revenue recognition approach is defensible, involves weighing facts against principles,  not just matching a pattern to prior examples.

    Regulatory and compliance decisions. Tax law and accounting standards change constantly and are applied to messy, specific situations. An accountant has to interpret intent, not just text.

    Audit accountability. An audit opinion carries legal and professional weight. Software can flag anomalies, but it can’t stand behind a sign-off the way a licensed auditor does.

    Client relationships. Clients bring accountants problems that don’t come pre-labeled,  a business decision, a family situation, an unexpected tax notice. That conversation is still a human one.

    Ambiguous or unusual transactions. AI models are trained on patterns in historical data. When something genuinely new comes up, a human has to figure out how to treat it.

    AI vs. Accountant: Who Does What?

    Business executives collaborating at a conference table alongside robotic arms processing paperwork in a modern high-rise office
    ResponsibilityAIAccountant
    Process routine transactionsDoes the workReviews exceptions
    Categorize expensesDoes the workReviews edge cases
    Detect anomaliesFlags themInvestigates and decides
    Draft reportsProduces first draftInterprets and finalizes
    Forecast scenariosAssists with modelingDecides which scenario to plan around
    Interpret regulationsAssists with researchMakes the call
    Handle complex tax issuesAssists with researchLeads
    Advise managementSupports with dataLeads the conversation
    Take professional responsibilityNoYes

    That last row is the one that matters most. Software doesn’t carry a license, sign an audit opinion, or represent a client in front of the IRS. A person does.

    Will AI Replace Accounting Jobs, or Reshape Them?

    This is where the employment data gets genuinely interesting, because two respected sources appear to disagree.

    1. What the U.S. employment data says

    The U.S. Bureau of Labor Statistics projects roughly 5% employment growth for accountants and auditors from 2025 to 2035, with about 115,300 average annual openings over that period, driven mostly by the need to replace workers who retire or change occupations 

    2. Why the World Economic Forum paints a different picture

    The World Economic Forum’s Future of Jobs Report 2025 lists accountants and auditors among the roles expected to decline globally through 2030, as part of a broader shift toward AI-augmented finance functions (WEF Future of Jobs Report 2025).

    3. Why both can be true at once

    These two projections aren’t actually measuring the same thing. The BLS figure is a U.S.-specific projection built largely around replacement demand, people retiring or leaving the field,  plus modest net growth.

    The WEF figure is a global survey of employer sentiment about which roles they expect to shrink as they adopt AI, which captures a different signal: employer intent to reduce headcount in routine roles, not total labor market openings.

    Put together, a reasonable read is this: routine accounting labor is likely to shrink as a share of total accounting work, while the overall number of accounting positions in the U.S. keeps growing slowly, largely through replacement hiring and demand for higher-value skills.

    Global employer sentiment and U.S. labor projections just aren’t the same measurement, and treating them as contradictory misses that distinction.

    4. Task automation vs. job elimination

    It helps to separate two different things: a task being automated, and a job disappearing. When AI automates a task, the person doing that job usually absorbs new responsibilities rather than losing the job outright, assuming they adapt.

    Where jobs genuinely disappear is when a role is made up almost entirely of automatable tasks, which describes some junior processing roles more than it describes accounting as a whole.

    Which Accounting Jobs Are Most Vulnerable to AI?

    Some roles carry more automation risk than others, mostly because of how task-heavy they are in the automatable column above.

    • Bookkeeping and data-entry-heavy positions
    • Accounts payable processing roles
    • Accounts receivable processing roles
    • Payroll processing
    • Junior reconciliation work
    • Routine, high-volume tax preparation
    • Basic, templated reporting roles

    These aren’t roles that vanish overnight. But the headcount needed to do them is likely to shrink as software takes on more of the volume.

    Which Accounting Roles Are More Resistant to AI?

    • CPAs and other licensed professionals
    • Tax advisors handling complex or ambiguous situations
    • Forensic accountants
    • Internal auditors
    • Management accountants
    • Financial analysts
    • Advisory-focused accountants
    • Controllers and finance leaders

    “Resistant” doesn’t mean untouched. Every one of these roles will use AI tools daily within a few years, if they don’t already. It means the core of the job, judgment, accountability, and relationships,  is harder to automate.

    Will AI Replace CPAs?

    CPA work is different from general accounting work in one important way: professional accountability. A CPA doesn’t just produce a number, they stand behind it, professionally and sometimes legally.

    Tax representation is a good example. The IRS specifically grants CPAs, attorneys, and enrolled agents unlimited representation rights before the agency, meaning they can represent a client on any tax matter, in front of any IRS office (IRS: Understanding tax return preparer credentials). That’s a legal status a piece of software cannot hold.

    AI can still do a lot for a CPA: research, first-draft analysis, document review, and tax preparation support. But the license, the sign-off, and the liability stay with the person. The realistic future is an AI-enabled CPA, not an AI replacement for one.

    Will AI Replace Entry-Level Accountants?

    This is arguably the most important question for anyone currently studying accounting or early in their career, and it deserves a straight answer: entry-level accounting work is genuinely exposed, more than any other tier of the profession.

    Junior accountants have traditionally learned the job by doing the “grunt work”,  data entry, basic reconciliations, and manual checking. That work is disappearing fastest, which creates a real problem: if AI does the repetitive tasks that used to teach new accountants how the numbers connect, how do future accountants build that judgment in the first place?

    There’s no clean answer yet. Firms that are ahead on this are restructuring junior roles around reviewing AI output, investigating exceptions, and working directly on client-facing analysis earlier than before,  essentially compressing the learning curve rather than removing it. 

    New accountants entering the field should expect fewer pure data-entry roles and more emphasis on being able to read, question, and correct AI output from day one.

    How AI Is Changing an Accountant’s Day-to-Day Work

    AI is changing accounting less by removing the accountant from the process and more by changing where the accountant spends their time.

    Work that once required hours of manual processing can increasingly be handled or accelerated by AI, allowing accountants to focus on reviewing information, solving problems, and helping clients or businesses make better decisions.

    Before AI: an accountant might spend much of the day entering transactions, reconciling accounts, preparing reports, checking figures manually, and communicating with clients once the numbers were finalized.

    With AI in the workflow: the process can look very different. AI can assist with data capture and transaction classification, identify unusual entries, match records, summarize financial information, and prepare initial reports.

    The accountant then reviews exceptions, checks the accuracy of the output, interprets what the numbers actually mean, explores different scenarios, and uses those insights in advisory conversations and business decisions.

    This means accountants can become involved earlier and more often in the decision-making process, rather than being brought in only after the financial work is complete.

    For example, instead of simply producing a monthly cash-flow report, an accountant may use AI-assisted analysis to identify a potential cash shortage, model different scenarios, and recommend actions before the problem becomes serious.

    As this shift continues, some skills become more valuable than others. Professional judgment, communication, business understanding, technology fluency, analytical thinking, and risk management become increasingly important because these are the areas where context and human oversight matter most.

    Meanwhile, tasks that are primarily about processing large amounts of repetitive information quickly and accurately become less differentiated. Data entry, basic reconciliation, routine categorization, and standardized reporting can increasingly be automated or accelerated.

    The result is not an accountant-free workflow. It is an AI-assisted accounting workflow in which the accountant moves from being primarily a processor of financial information to an interpreter, reviewer, advisor, and decision-support professional.

    How AI Can Make Accountants More Productive

    There’s decent evidence this isn’t just theory. Research highlighted by Stanford Graduate School of Business found that AI tools helped accountants close books faster and handle more clients, by taking over the “boring” repetitive parts of the job and freeing up time for review and analysis.

    In practice, that shows up as: faster bookkeeping cycles, quicker month-end close, more clients supported per accountant, better anomaly detection across large transaction volumes, and more time actually spent advising clients instead of processing their data.

    The right best accounting software for analytics can extend these benefits by helping accountants turn financial data into clearer trends, insights, and decisions.

    The Risks of Using AI in Accounting

    None of this works if firms treat AI output as automatically correct. Accounting is a high-stakes environment, and a few risks deserve honest treatment.

    AI models can produce confident-sounding but wrong answers, a known limitation often called hallucination.

    In accounting, that might mean misclassifying a transaction, misapplying a tax rule, or generating a plausible-sounding but incorrect explanation of a variance. Intuit’s own guidance on AI in accounting flags exactly this kind of limitation, along with the need for human oversight and awareness of potential bias in AI outputs.

    Other real risks include data privacy exposure when financial information is fed into third-party AI tools, regulatory and compliance gaps if AI-generated output isn’t properly reviewed, and simple overreliance,  a junior team member trusting AI output without knowing enough to spot when it’s wrong. Human-in-the-loop review isn’t optional here; it’s the whole safety mechanism.

    What Skills Will Accountants Need in the AI Era?

    • AI literacy, understanding what these tools are good and bad at
    • Data analysis and interpretation
    • Financial modeling
    • Tax and regulatory expertise
    • Professional judgment
    • Clear communication, especially explaining numbers to non-accountants
    • Strategic and business thinking
    • Advisory skills
    • Familiarity with accounting-specific AI tools and platforms

    Accounting knowledge is still the foundation. AI skills are the multiplier on top of it, not a replacement for it. Strong Business Data Analytics skills can further strengthen that combination by helping accountants interpret financial data, identify trends, and turn numbers into actionable business insights.

    How Accountants Can Prepare for AI

    1. Learn how the AI tools in your accounting software actually work, including their limitations.
    2. Get hands-on with AI-enabled platforms rather than avoiding them.
    3. Use automation for repetitive tasks so you have time for higher-value work.
    4. Build the habit of reviewing AI output critically instead of accepting it by default.
    5. Keep deepening your core accounting and tax expertise,  it’s still what makes the review meaningful.
    6. Develop advisory and client-communication skills.
    7. Build data literacy so you can question and interpret what AI produces.
    8. Stay current on regulatory and professional standards, since AI tools don’t take responsibility for compliance.

    There’s an active discussion of exactly these adjustments happening among practitioners on forums like r/Accounting on Reddit and in professional groups on LinkedIn, where working accountants are sharing what’s actually changing at their firms,  worth reading alongside any single article, including this one.

    What Will the Accountant of 2030 Look Like?

    Less data entry. More exception management. More analysis and interpretation. More direct client interaction. More strategic decision support. And a growing responsibility for overseeing AI output rather than producing every number by hand.

    A useful shorthand: the accountant becomes the trust layer between AI-generated financial data and the decisions people make based on it.

    AI vs. Automation: Why the Difference Matters

    These terms get used interchangeably, but they’re not the same thing, and the distinction matters for understanding where accounting is headed.

    Traditional accounting automation follows fixed rules,  if a transaction matches a pattern, apply a fixed treatment. Machine learning goes a step further, learning patterns from historical data rather than following hard-coded rules.

    Generative AI, the technology behind tools like ChatGPT and Claude, can produce novel text and analysis rather than just classifying data (Generative artificial intelligence).

    Agentic AI takes this further by chaining tasks together with less human input at each step, and “autonomous finance” describes the (still largely aspirational) end state where financial processes run with minimal human intervention.

    Accounting today sits somewhere between the first and third of these. Full autonomy in high-stakes financial work is not close.

    Is Accounting Still a Good Career in the Age of AI?

    Yes, but with an important caveat. Accounting expertise combined with AI fluency is becoming a much stronger career position than accounting expertise alone.

    AI is making many repetitive accounting tasks faster and easier to automate, so roles built primarily around data entry, basic reconciliation, transaction processing, or routine reporting may face more pressure than they did in the past.

    That does not make accounting a poor career choice. It means the skills that create value are changing. Accountants who understand financial principles, regulations, business operations, and professional judgment while also knowing how to use AI tools can work more efficiently and take on higher-value responsibilities.

    Instead of spending most of their time processing information, they can spend more time interpreting it, identifying risks, explaining financial results, and helping businesses make decisions.

    Some career paths are particularly well positioned for this shift. Advisory services, tax specialization, forensic accounting, audit leadership, financial analysis, and controller-track roles all rely heavily on judgment, context, communication, and accountability.

    AI can support professionals in these areas, but it does not remove the need for someone who can evaluate the output and understand the consequences of acting on it.

    There is also an important change happening at the entry level. New accountants may encounter fewer traditional “grunt work” tasks because AI can handle more routine processing.

    That could make the early career path look different from what previous generations experienced. At the same time, it creates an opportunity for new accountants to develop analytical, technological, and advisory skills earlier.

    So, anyone considering accounting should not be discouraged by AI headlines. Accounting is still a viable career, but the safest path is not to compete with AI at repetitive tasks.

    It is to become the person who knows how to use AI, verify its work, apply accounting judgment, and turn financial information into useful business decisions. AI fluency should increasingly be treated as a core accounting skill rather than an optional extra.

    Frequently Asked Questions About AI and Accounting

    Will AI completely replace accountants? 

    No. AI automates specific tasks within accounting, but professional judgment, regulatory accountability, and client relationships remain human responsibilities.

    Will AI replace CPAs? 

    Unlikely. CPAs hold legal representation rights and professional accountability that software cannot take on, though CPAs will increasingly use AI tools for research and drafting.

    Will AI replace bookkeepers? 

    Bookkeeping is one of the most exposed roles, since much of the work is repetitive data entry and categorization. Bookkeepers who move toward review, oversight, and client communication are better positioned.

    Will accounting jobs disappear? 

    Some routine, entry-level roles will shrink. Overall accounting employment in the U.S. is still projected to grow modestly, according to BLS data.

    What accounting tasks are most likely to be automated? 

    Data entry, invoice processing, transaction categorization, bank reconciliation, and first-draft reporting.

    Conclusion

    AI will replace some accounting tasks, reduce demand for certain routine roles, and change the accounting career path more than many people expect.

    Repetitive work such as data entry, transaction categorization, invoice processing, reconciliation, and basic reporting is increasingly suited to automation.

    That means accountants may spend less time processing numbers manually and more time reviewing results, investigating exceptions, interpreting financial information, managing risk, and advising clients or businesses.

    What the evidence does not support is the idea that accountants as a profession are simply disappearing. Accounting still depends on human judgment, regulatory knowledge, professional responsibility, communication, and the ability to understand the business context behind the numbers.

    AI can generate analysis and identify patterns, but someone still needs to verify the information, understand its implications, and take responsibility for important financial decisions.

    The bigger shift is therefore from doing every accounting task manually to managing and interpreting AI-assisted financial work.

    Accountants who learn how to use AI effectively can become more productive and focus on higher-value responsibilities, while those who rely only on traditional, repetitive workflows may face greater pressure.

    The biggest risk isn’t AI replacing accountants. It’s accountants who know how to use AI replacing accountants who don’t.

  • How to Scale a Marketplace Business: A Practical Growth Strategy

    How to Scale a Marketplace Business: A Practical Growth Strategy

    Scaling a marketplace business isn’t the same as scaling a normal online store or a SaaS product. When you grow an ecommerce brand, you’re mostly solving one problem: get more people to buy. A marketplace has two customers to satisfy at once, buyers and sellers,  and growth on one side without the other just breaks things.

    Add more buyers without enough sellers, and people show up to an empty shelf. Add more sellers without enough buyers, and your best sellers leave for somewhere they can actually make sales. This is why so many marketplace founders hit a wall: they treat “scale” as a traffic problem when it’s really a balance problem.

    The short answer: scale a marketplace by first proving liquidity and unit economics, then strengthening whichever side of the marketplace is holding you back, building acquisition channels you can repeat, and expanding into new locations, categories, or customer segments one at a time, not all at once.

    The rest of this guide walks through that process step by step, from figuring out if you’re actually ready to grow, to picking your next market, to the operational and trust systems that keep a bigger marketplace from falling apart.

    What Does It Mean to Scale a Marketplace Business?

    Scaling means growing transactions, revenue, and reach without losing the thing that made the marketplace work in the first place: a reliable match between buyers and sellers.

    1. Marketplace scaling vs. ordinary e commerce growth

    E-commerce store compared with a two-sided marketplace connecting buyers and sellers.

    An e commerce store scales by increasing traffic and conversion rate. A marketplace has to grow supply and demand together, in roughly the right proportion, or the whole thing gets worse instead of better. More listings with no buyers is just clutter. More buyers with no listings is a bounce rate problem.

    2. Why two-sided marketplaces are harder to scale

    Every growth decision touches two different groups with different motivations. A pricing change that pleases buyers might push sellers out.

    A push to add sellers fast might dilute quality and scare buyers away. You’re not managing one funnel,  you’re managing two, and they depend on each other.

    3. The marketplace flywheel

    Most healthy marketplaces run on a loop like this: more supply leads to better selection, better selection brings in more demand, more demand creates more transactions, more transactions attract more sellers, and the cycle repeats.

    Scaling well means putting your energy into whichever part of that loop is currently weakest, rather than pushing marketing spend into a system that isn’t ready to absorb it.

    When Is a Marketplace Ready to Scale?

    This is the question most articles skip, and it’s the one that matters most. Traffic growth doesn’t mean you’re ready to scale, it just means more people are looking.

    Readiness is about whether your marketplace can actually deliver on what those people are looking for.

    1. You have repeatable transactions

    If most of your transactions come from one-off pushes, a founder emailing their network, a discount code, a press mention, you don’t have a repeatable engine yet. You have a series of favors.

    2. Supply and demand are sufficiently liquid

    Liquidity means a reasonable share of buyer requests actually turn into completed transactions, and a reasonable share of listings actually get bought or booked. If most searches come up empty, or most listings never sell, scaling will only multiply the frustration.

    3. Sellers are staying active

    Sellers who list once and disappear are a warning sign, not a growth number. Active, returning sellers are what make a marketplace feel alive to buyers.

    4. Buyers are returning

    New buyer acquisition is expensive. If people transact once and never come back, you’re running a leaky bucket, and pouring more traffic in just means pouring more out.

    5. Unit economics are becoming predictable

    You should have a rough, working sense of what it costs to acquire a buyer or seller and what they’re worth over time. “We’ll figure out the economics once we’re bigger” is how marketplaces run out of money while growing.

    6. Operations can handle higher volume

    If your support inbox, dispute resolution, or seller onboarding is already stretched thin at your current volume, doubling that volume won’t just be uncomfortable, it can break the trust you’ve built.

    7. Trust and quality systems are working

    Reviews, verification, and dispute handling need to be functioning before you scale, not bolted on after problems show up at a larger scale.

    8. Marketplace scale-readiness checklist

    Before pushing hard on growth, check these:

    • Transactions happen weekly without manual intervention
    • A meaningful share of searches or requests result in a transaction
    • Sellers who join are still active after 60–90 days
    • A meaningful share of buyers make a second purchase
    • You know your rough CAC and LTV for both sides
    • Support and operations aren’t already at capacity
    • Reviews, verification, and dispute processes exist and work
    • You’ve identified which side (supply or demand) is currently the constraint

    If most of these are shaky, the priority is fixing the core marketplace, not adding fuel to it.

    Solve the Marketplace Chicken-and-Egg Problem First

    1. What is the chicken-and-egg problem?

    Buyers won’t come without good selection, and sellers won’t join without buyers. Every marketplace starts here, and it resurfaces every time you enter a new market or category,. it’s not a problem you solve once and forget.

    2. Should you grow supply or demand first?

    There’s no universal rule. It depends on your category. Research from Lenny Rachitsky’s interviews with marketplace operators found that many well-known marketplaces leaned heavily on building supply first, though a number of them were actually demand-constrained rather than supply-constrained (Lenny’s Newsletter).

    The point isn’t “supply always wins”,  it’s that you need to check which side is actually the bottleneck for your specific marketplace before deciding where to put your energy.

    3. How to identify your constrained side

    Use a simple diagnostic. If buyers search but don’t find enough relevant listings, you’re supply-constrained.

    If sellers have listings but aren’t getting transactions, you’re demand-constrained. Look at your own data,  search-to-result rates on one side, listing-to-sale rates on the other,  instead of guessing.

    4. When supply should come first

    Categories where selection and variety drive the decision,  rentals, freelance services, unique goods — usually need a critical mass of supply before demand will stick around.

    5. When demand should come first

    Categories with more standardized listings, or where sellers are professionals who’ll join as soon as there’s proven buyer interest, can sometimes justify demand-first growth.

    Sellers with existing sales channels are often willing to test a new platform if you can show them real buyer intent.

    6. How marketplaces approached the problem

    Airbnb famously grew supply by helping early hosts take better listing photos,  a manual, unscalable tactic that solved a very specific supply-quality problem before the company ever tried to scale demand. Uber launched city by city, deliberately seeding driver supply before marketing to riders in a new city.

    Etsy built its early growth around a community of independent sellers, which created selection before demand was pushed hard. These aren’t templates to copy directly,  they’re evidence that the right sequencing depends on the category, not a fixed playbook.

    Improve Marketplace Liquidity Before Expanding

    1. What is marketplace liquidity?

    Liquidity is how reliably a marketplace turns interest into a completed transaction. A search that returns good options and ends in a booking is liquid. A search that returns nothing relevant is not, no matter how much traffic you’re getting.

    2. Why liquidity matters more than raw traffic

    You can double your traffic and end up with the same number of transactions if liquidity doesn’t improve. Traffic without liquidity just means more disappointed visitors, which quietly raises your acquisition costs because fewer of them convert or come back.

    3. How to measure buyer liquidity

    Look at the share of buyer searches or requests that end in a completed transaction within a reasonable window. Business data analytics can help you identify these patterns and determine where buyers are dropping out of the marketplace.

    4. How to measure seller liquidity

    Look at the share of listings that get at least one transaction within a set period. A high number of dead listings,  things posted and never sold or booked, signals weak seller-side liquidity.

    5. How to reduce time-to-match

    Faster matching keeps both sides engaged. This might mean better search filters, automated matching, or simply having enough density of supply that buyers don’t have to wait.

    6. How to improve search-to-transaction conversion

    Look at where buyers drop off between searching and completing a transaction. Often it’s unclear pricing, too few relevant results, or friction in checkout, all fixable without adding a single new user.

    7. How to increase supply density

    Density matters more than total supply count. A marketplace with 10,000 sellers spread across 50 cities can feel emptier to a buyer than one with 500 sellers concentrated in a single city. Concentrate before you spread out.

    8. How to improve marketplace matching

    Better filters, smarter default sorting, and (where it makes sense) recommendation logic all help buyers find relevant listings faster, which directly improves conversion.

    Build a Strong Marketplace Foundation Before Scaling Acquisition

    Don’t scale acquisition faster than your marketplace can deliver value. If the core transaction experience is shaky, spending more on growth just means more people experiencing that shakiness,  and telling their friends about it.

    1. Improve search and discovery

    Buyers need to find relevant listings quickly. If your search results are noisy or your filters don’t match how people actually shop, fix that before buying more traffic.

    2. Optimize listing quality

    Clear photos, honest descriptions, and consistent pricing formats reduce buyer hesitation. This often matters more than adding more listings.

    3. Simplify transactions and checkout

    Every extra step in booking or purchasing is a place someone can abandon. Watch your funnel for drop-off points.

    4. Build seller onboarding

    A confusing onboarding process is often the real reason sellers “don’t stick around.” Make it fast to list something and start getting visibility.

    5. Create reliable payments and payouts

    Sellers need to trust that money will actually arrive, on time, without confusion. Marketplace-specific payment infrastructure,  split payments, escrow-style holds, scheduled payouts,  is core plumbing, not a nice-to-have.

    Sharetribe’s marketplace-building guide treats payments, seller verification, and payout systems as foundational rather than optional.

    6. Establish reviews and ratings

    Reviews reduce the trust gap for new buyers deciding whether to transact with an unfamiliar seller. Without them, every transaction feels riskier than it needs to.

    7. Build verification and moderation

    Basic identity or listing checks catch bad actors before they damage trust across the whole platform.

    8. Create dispute and refund processes

    Disputes will happen. What matters is whether there’s a clear, fair process, so one bad transaction doesn’t turn into a public trust problem.

    Prove Marketplace Unit Economics

    Metrics like GMV, CAC, and LTV get mentioned everywhere, but the number itself doesn’t matter as much as what decision it helps you make.

    1. GMV (Gross Merchandise Value)

    Total value of transactions flowing through the marketplace. It tells you about volume, not profitability — a marketplace can have huge GMV and still lose money on every transaction.

    2. Revenue

    What the marketplace actually keeps, usually a percentage of GMV (the take rate) or a flat fee.

    3. Take rate

    Revenue divided by GMV. This tells you how much of the transaction value you’re capturing, and whether that’s sustainable given your costs.

    4. Customer acquisition cost (CAC)

    What it costs, in marketing and sales spend, to acquire one paying buyer or one active seller. Customer acquisition cost (CAC) is especially important for marketplaces because buyer and seller acquisition can behave very differently.

    5. Customer lifetime value (LTV)

    The expected revenue from a customer over the time they stay active. This tells you how much CAC you can afford before growth becomes unprofitable.

    6. Contribution margin

    Revenue minus the variable costs of serving a transaction, payment processing, support, fraud losses. This tells you whether growth actually improves your financial position or just moves more money through a leaky system.

    7. Payback period

    How long it takes to recover the cost of acquiring a customer. Shorter payback periods mean you can reinvest in growth faster.

    8. Seller acquisition cost

    Often overlooked, but seller-side CAC can be just as important as buyer CAC, especially in categories where good sellers are scarce.

    9. Repeat purchase rate

    The share of buyers who transact more than once. This is often the clearest early signal of whether the marketplace is actually delivering value.

    10. How CAC, LTV, and take rate work together

    If your take rate is 15%, your LTV needs to reflect that,  a buyer who spends $1,000 over their lifetime is only worth $150 in revenue to you, not $1,000.

    Compare that $150 against your CAC. If CAC is $180, you’re losing money on every buyer you acquire, no matter how good your GMV numbers look on a dashboard.

    11. Example marketplace unit economics calculation

    A home services marketplace has a 12% take rate, average buyer LTV of $2,000 in GMV over two years, and buyer CAC of $60.

    Revenue per buyer works out to $240 (12% of $2,000), against a $60 acquisition cost, a healthy 4x return before accounting for support and processing costs. That’s the kind of math worth doing before scaling acquisition spend, not after.

    Choose How You Want to Scale

    Sharetribe’s marketplace scaling framework identifies location, category, and customer segment as the main vectors marketplaces use to grow. Each comes with different trade-offs.

    1. Scale by geography

    Take your proven model into a new city, region, or country. This works well when your existing market has strong liquidity and the model doesn’t depend heavily on local relationships that don’t transfer.

    .2. Scale by category

    Add adjacent product or service categories that your existing buyers are already asking for. This can work well if your existing supply base can stretch into the new category without diluting quality.

    3. Scale by customer segment

    Serve a new type of buyer or seller with your existing infrastructure,  for example, moving from individual consumers to small businesses.

    This can unlock a much larger addressable market, but the new segment often has different needs than the one you built for.

    4. Scale through adjacent products or services

    Similar to category expansion, but usually smaller in scope,  adding a complementary offering rather than a whole new vertical.

    5. Scale internationally

    The highest-risk, highest-reward option. It usually means dealing with new regulations, payment systems, and buyer behavior all at once.

    6. How to choose the right scaling vector

    Expansion routeBest whenMain advantageMain risk
    New locationLocal liquidity is strong and repeatableReplicates a proven modelLaunch cost in each new market
    New categoryExisting users are already asking for itCross-sell into an existing baseSupply gets fragmented
    New segmentExisting infrastructure fits new usersBigger addressable marketDifferent needs, different expectations
    InternationalModel is highly repeatableLarge growth ceilingRegulation and localization work

    Pick the one that plays to your current strength, not the one that sounds most exciting in a pitch deck.

    How to Choose Your Next Market

    If you’re expanding geographically, score potential markets rather than picking based on gut feel or which city a team member happens to live in.

    Consider market size, existing demand signals, whether supply is available locally, how much competition already exists, local customer behavior, cultural differences that might affect adoption, how comfortable the local population is with the underlying technology, relevant regulation, available payment infrastructure, and your realistic cost of launching there.

    New-market scoring framework

    Market scoring framework comparing potential markets using ratings, charts, growth data, and evaluation factors.

    Score each factor from 1 to 5 for every candidate market, then compare totals. A market that scores well on size but poorly on regulation and payment infrastructure might actually be a worse bet than a smaller market where launch friction is low.

    The scoring exercise is less about the exact number and more about forcing an honest comparison instead of picking the market that feels most familiar.

    Build a Repeatable Marketplace Expansion Playbook

    The goal after your first successful expansion is to turn it into a repeatable process, not a one-off project.

    Document what actually worked in your first successful market and be honest about which parts can be standardized versus which parts had to be handled locally, things like partnerships, regulation, or customer expectations rarely transfer as-is. Launch new markets small, as real tests rather than full rollouts.

    Focus early effort on establishing supply, then demand, and measure liquidity before spending more on that market. Improve the local experience based on what you learn, and set a clear point at which you decide to keep investing or pull back.

    Example 90-day marketplace expansion plan

    Days 1–30: recruit an initial base of sellers manually, focusing on quality over quantity. Days 31–60: introduce demand carefully, ideally through channels that convert well without much spend — referrals, existing-market cross-promotion, local partnerships.

    Days 61–90: measure liquidity and transaction repeat rate, then decide whether to keep investing in that market or shift resources elsewhere.

    Use SEO to Scale Marketplace Demand

    For a lot of marketplaces, SEO for business is one of the most durable demand channels available because organic search can scale without a matching increase in paid spend.

    Category landing pages and location landing pages give search engines (and buyers) a clear entry point for specific intent,”cleaning services in Austin” needs its own page, not just a filter buried in a search bar. Combining category and location (“plumbers in Denver”) often captures long-tail searches that are highly specific and easier to rank for.

    Individual seller or listing pages, when well-optimized, can also capture search traffic on their own. Programmatic SEO,  generating pages at scale from structured data, can work well for marketplaces with many locations or categories, but it needs careful handling of thin or duplicate content, or it does more harm than good.

    Comparison content, genuine user-generated reviews, strong internal linking between related category and location pages, and clean indexation control all support this.

    A marketplace-growth analysis from Journey Horizon specifically points to category, subcategory, and location page combinations as a meaningful SEO opportunity for marketplaces that haven’t built them out yet.

    Build Growth Loops Instead of Relying Only on Paid Acquisition

    Paid acquisition gets expensive fast, especially on both sides of a marketplace at once. Growth loops — where usage itself generates new usage, are more sustainable over time.

    Sellers who succeed on your platform often refer to other sellers. Buyers who have a good experience refer to other buyers. Organic search compounds over time instead of resetting with every ad budget cycle.

    Content built around real buyer or seller questions keeps working long after it’s published. Network effects mean each new user makes the marketplace slightly more valuable to everyone already on it.

    Partnerships with complementary businesses can bring in users who already trust the referring brand. Retention work, keeping existing users active, reduces how much new acquisition you need in the first place. And cross-selling into adjacent categories lets you grow revenue from users you already have.

    Increase Seller Supply Without Sacrificing Quality

    Marketplace seller supply strategy showing verified sellers, outreach, partnerships, onboarding, and growth tracking.

    Growing supply too fast, without a quality bar, is one of the fastest ways to damage buyer trust.

    Direct outreach, personally recruiting the right sellers rather than waiting for them to find you, still works well in the early stages of any new category or market. Referral programs and targeted incentives can accelerate this once you have a base of happy sellers to draw from.

    Partnerships with associations, agencies, or other platforms can bring in vetted supply faster than cold outreach.

    Automating onboarding reduces friction for legitimate sellers, and tracking activation (are new sellers actually getting their first sale quickly?) and retention (are they still active after a few months?) tells you whether your supply growth is healthy or just noisy.

    Increase Buyer Demand and Repeat Transactions

    Acquiring a new buyer is usually far more expensive than keeping an existing one active, which is why repeat transaction rate deserves as much attention as new buyer growth.

    Improving discovery and search relevance helps buyers find what they want faster. Reducing friction at checkout improves conversion without adding a single new visitor.

    Personalized recommendations, where you have enough data to support them, can lift repeat engagement.

    Referral programs turn happy buyers into an acquisition channel. And simply reducing friction throughout the experience, fewer required fields, clearer pricing, faster load times, often moves the needle more than any single growth tactic.

    Scale Marketplace Technology and Operations

    Growth creates operational load that doesn’t show up on a growth chart until it becomes a problem. Search and matching systems need to keep performing as listing volume grows.

    Payments and payouts need to stay reliable as transaction volume increases. Seller management, customer support, fraud prevention, and moderation all need systems, not just more people doing the same manual work.

    AppDirect’s guidance on marketplace ecosystems highlights integrations, automated vendor onboarding, compliance handling, and self-service tools as what let marketplaces support more sellers and partners without support headcount growing at the same rate.

    Analytics dashboards and automated alerts help you catch liquidity or quality problems in a specific market or category before they show up as churn.

    Where it fits your category, AI-assisted matching or recommendations can improve relevance as your catalog grows too large for simple filters to handle well.

    Protect Trust and Quality While Scaling

    Trust is the hardest thing to rebuild once it’s damaged, and scaling puts more stress on trust systems than anything else.

    Seller and buyer verification reduce fraud and give both sides confidence. Reviews and ratings help buyers make decisions without needing to know a seller personally. Fraud detection and content moderation catch problems before they spread.

    Clear dispute resolution and refund policies mean one bad transaction doesn’t turn into a trust crisis across the platform.

    Service-level standards give sellers something concrete to meet, and basic marketplace governance, rules about what’s allowed and how they’re enforced,  keeps the whole system fair as it grows past the point where you can personally know every seller.

    The Most Important Marketplace Metrics to Track

    KPIHow it’s measuredWhat it tells you
    GMVTotal transaction valueOverall marketplace volume
    Take rateRevenue ÷ GMVHow much value you’re capturing
    CACAcquisition spend ÷ new customersGrowth efficiency
    LTVExpected customer value over timeLong-term economics
    LiquiditySuccessful matches ÷ relevant opportunitiesMarketplace health
    Conversion rateTransactions ÷ relevant visitsDemand-side efficiency
    Repeat purchase rateRepeat buyers ÷ total buyersRetention strength
    Seller activationActive sellers ÷ onboarded sellersSupply quality
    Seller retentionRetained sellers ÷ total sellersSupply-side health
    Time-to-matchTime from request to completed transactionMatching efficiency
    Contribution marginRevenue minus variable costsWhether growth is actually profitable

    How to Know When Not to Scale Yet

    Sometimes the right move is to slow down and fix what you have, not push harder on growth.

    Signs it’s not time yet: liquidity is still weak in your core market, one side of the marketplace (usually supply) is largely inactive, CAC is climbing faster than LTV, sellers are churning faster than you’re replacing them, buyers aren’t coming back after their first transaction, quality complaints are trending up, your operations are still mostly manual and already stretched, or your existing market hasn’t reached enough density to feel reliable to either side.

    This is the section founders tend to skip, but it might be the most useful one. The question worth asking isn’t “how do I grow faster”,  it’s “what’s currently stopping me, and is it actually fixed yet.”

    Common Marketplace Scaling Mistakes

    Expanding into too many markets at once, before any single one has proven itself. Adding new categories before the core marketplace has real liquidity. Buying traffic before fixing a broken conversion funnel. 

    Growing supply aggressively without matching demand, or the reverse. Ignoring seller-side economics while focusing only on buyer growth. Letting buyer retention slide while chasing new buyer acquisition. 

    Optimizing for GMV while quietly losing money on every transaction. Automating a process that was already broken, which just breaks it faster and at higher volume. And sacrificing quality standards for growth speed, a mistake that’s cheap to make and expensive to undo.

    Marketplace Scaling Examples

    Airbnb grew by building density in specific cities and neighborhoods first, rather than spreading thin across many markets at once. Their early focus on host photo quality solved a specific supply problem before broader growth.

    Uber launched market by market, seeding driver supply in each new city before marketing hard to riders, a repeatable playbook built city by city rather than all at once.

    Etsy grew around an ecosystem of independent sellers and craft categories, letting the seller community itself become part of the demand story.

    Thumbtack took a broader, less category-specific approach, covering a wide range of local services rather than specializing narrowly.

    DoorDash focused heavily on expanding restaurant supply and delivery reliability, treating selection and fulfillment speed as the core growth lever rather than just marketing spend.

    What founders should actually learn from these examples

    These aren’t blueprints to copy directly. The categories, timing, and competitive landscape were all different from whatever you’re building now. 

    What’s actually useful here is the pattern: each of these companies identified their real constraint and focused resources there before pushing broader growth.

    A discussion thread on r/startups makes a similar point, founders repeatedly note that copying a well-known company’s specific tactics without their underlying market conditions tends to backfire (startups, Reddit).

    A Practical Marketplace Scaling Framework

    Putting it all together, here’s a repeatable sequence:

    1. Validate: confirm buyers and sellers actually want what you’re offering, beyond a small initial group.
    2. Measure: get real numbers on liquidity, CAC, LTV, and retention.
    3. Diagnose: figure out honestly whether supply or demand is your constraint.
    4. Fix liquidity: improve matching and conversion before adding more volume.
    5. Prove economics: confirm the unit economics work at your current scale.
    6. Build growth loops: reduce dependence on paid acquisition.
    7. Choose one expansion vector: location, category, or segment, not all three at once.
    8. Launch a controlled expansion: treat it as a test, not a full commitment.
    9. Automate operations: build systems before volume forces you to.
    10. Repeat what works: turn your first successful expansion into a playbook for the next one.

    Frequently Asked Questions

    How do you scale a marketplace business? 

    Prove liquidity and unit economics in your core market first, fix whichever side (supply or demand) is holding you back, build acquisition channels you can repeat without constantly increasing spend, then expand into one new location, category, or segment at a time.

    How do you increase liquidity in a marketplace? 

    Improve search and matching so buyers find relevant listings faster, increase supply density in your existing market before spreading geographically, and fix friction points in the transaction flow itself.

    Should a marketplace focus on supply or demand? 

    It depends on the category. Check your own data, if searches return too few relevant results, you’re supply-constrained; if listings aren’t converting into transactions, you’re demand-constrained.

    When should a marketplace expand to a new city? 

    Once your current market has strong liquidity, repeatable transactions, and a playbook you can document and hand to a team launching the next market.

    Is it better to expand by geography or category? 

    Neither is universally better. Geography works well when your model is highly repeatable; category works well when existing buyers are already asking for it and your supply base can stretch to meet it.

    What metrics should a marketplace track? 

    GMV, take rate, CAC, LTV, liquidity, conversion rate, repeat purchase rate, seller activation and retention, time-to-match, and contribution margin.

    Conclusion

    A marketplace shouldn’t be judged on how many users, sellers, categories, or markets it has. The real goal is more successful transactions, delivered efficiently, without losing liquidity, trust, retention, or healthy economics along the way.

    There’s no single scaling playbook that fits every marketplace,  a local services platform, a B2B software marketplace, and a rental marketplace all have different liquidity dynamics and different constraints. 

    What holds across all of them is the discipline to check readiness before pushing growth, diagnose the real constraint instead of guessing, and expand in controlled steps you can actually learn from. 

    That discipline, more than any single tactic, is what separates marketplaces that scale well from ones that just get bigger and messier.

    For further reading on marketplace mechanics and network effects, Wikipedia’s overview of two-sided markets is a useful primer, and marketplace-focused discussions on LinkedIn often surface real operator experience worth following.

  • Taxation Without Representation: What It Means and Why It Still Matters for Businesses Today

    Taxation Without Representation: What It Means and Why It Still Matters for Businesses Today

    At its simplest taxation without representation means being forced to pay taxes to a government without having a say in the politics that create those taxes. 

    The phrase became one of the famous complaints of American colonists in the 1760s and 1770s. Their problem was not just that taxes were there. 

    Their problem was being taxed by the British Parliament while not having any elected people from their area in Parliament. (PBS). That difference is important.

    Taxes are a part of running a modern economy. Businesses might have income taxes, employment taxes, excise taxes, sales or use taxes, property taxes and other state or local requirements based on how they’re set up and where they are located. 

    The IRS says that the type of business a company has determined which taxes it might need to pay and how those taxes are managed. (IRS)

    So why link a slogan from the 1700s with businesses today?

    Because taxes are not about money. They are also about having a say in being held responsible, being open and being able to take part in decisions that influence the economy.

    For business owners, knowing about the idea behind taxation without representation can help them understand why tax policy gets much attention, how governments get the power to tax and why businesses often support or oppose changes to taxes.

    What Does Taxation Without Representation Mean?

    Colonial-era illustration showing British authorities collecting taxes from American colonists protesting a lack of political representation.

    Taxation without representation is when the government takes your money without you having a say in how it’s spent. You do not get to choose the people who make the decisions about taxes.

    The American colonies did not like it when the British government taxed them without giving them a voice.

    The main point was simple: if you have to pay taxes you should have a say in how the government spends your money. The problem was not about how much money people had to pay in taxes.

    Taxation without representation is really about having a say in the government and being able to agree or disagree with the decisions they make. It is about being heard and having control over the money you earn.

    The issue of taxation without representation is more about being treated and having representation in the government.

    During the colonial period, Parliament passed measures that affected the American colonies. Colonists objected because they did not elect representatives to Parliament.

    The dispute became particularly intense following measures such as the Stamp Act and Townshend Acts, contributing to protests, boycotts, and eventually the revolutionary movement.

    The principle eventually became closely associated with the broader American argument for representative government.

    Taxation vs. Taxation Without Representation

    Taxation comparison showing representative government on one side and taxation without political representation on the other.

    It is important not to confuse these two concepts.

    Taxation simply means a government requires individuals or businesses to make payments to fund public purposes.

    Taxation without representation refers specifically to the relationship between taxation and political representation.

    A person or business can disagree with a tax rate without necessarily experiencing taxation without representation.

    For example, a business owner might believe that a 30% tax rate is too high. That is a disagreement about tax policy.

    By contrast, taxation without representation raises a different question:

    Does the taxpayer have a meaningful political mechanism to participate in the government that imposes the tax?

    That distinction is essential when discussing the historical meaning of the phrase.

    The History of Taxation Without Representation

    1. Why Did the Colonists Object to British Taxes?

    After the French and Indian War finished in 1763 Britain had a lot of debts and costs to deal with. The British government tried to get money from the American colonies by using different taxes and charges.

    The colonists already paid taxes at the colonial level. Their main issue was not the idea of being taxed.

    The real issue was that Parliament made rules for the colonies even though the colonies did not choose members of Parliament.

    Because of this the colonists said that taxing them without letting them vote was breaking their rights.

    This disagreement turned the topic of taxes into a conversation, about who had power and what it meant to govern yourself.

    2. The Stamp Act

    The Stamp Act of 1765 was a law that made printed things in the colonies have a special stamp. The stamp was linked to a tax that people had to pay. This law affected papers like papers, newspapers, licenses and other printed things. 

    Soon after the law was passed people in the colonies started to object. People who did not like the law said that Parliament did not have the right to make them pay taxes. They said this because they did not have any representatives in Parliament. 

    The argument over the Stamp Act helped make the idea of “no taxation, without representation” well known. 

    3. The Boston Tea Party

    The argument finally got worse.

    The Tea Act from 1773 played a role in the events that led to the Boston Tea Party, when people in the colonies showed their anger about taxes and the special treatment given to the East India Company.

    The Boston Tea Party turned into a sign of resistance from the colonies. It also showed that arguments about taxes could grow into bigger issues than just money. 

    Discussions about taxes started to mix with questions about power in politics, control over the economy, having a voice in government and whether the government was fair.

    4. The Declaration of Independence

    The Declaration of Independence had a list of complaints against the British Crown and the government of Britain.Taxation was one of the issues that the American colonies had with  Britain.

    However the American Revolution was about more than high taxes. The American Revolution was really about who had the power to make decisions, how the colonies were represented in the government of Britain, what laws were passed and whether the colonies could govern themselves.

    The American colonies and Britain did not see eye to eye on these issues. Historians today say that the American Revolution was mainly about the colonies wanting to have a say in how they were governed and who had the power to make decisions, not just about the amount of taxes they had to pay according to PBS.

    Why Representation Matters When Governments Tax

    The principle behind taxation without representation is based on a simple democratic idea:

    People affected by government decisions should have a voice in choosing the people who make those decisions.

    Taxes influence almost every part of an economy.

    They can affect:

    • Business profits
    • Consumer prices
    • Employee compensation
    • Investment decisions
    • Hiring
    • Business formation
    • Property ownership
    • Imports and exports
    • Corporate expansion
    • Entrepreneurial risk
    • Government spending

    Because taxation can have such broad consequences, taxpayers have an interest in how tax laws are created.

    In a representative system, citizens elect lawmakers who create legislation, including tax legislation.

    The U.S. Constitution gives Congress the authority to impose federal taxes. Article I, Section 8 gives Congress power to lay and collect taxes, duties, imposts, and excises for purposes including paying debts, providing for the common defense, and promoting the general welfare.

    This creates an important difference between the colonial situation and the modern federal system.

    The modern U.S. system is built around representative institutions rather than taxation imposed by an unelected Parliament over a population lacking elected representation in that body.

    Does Taxation Without Representation Still Exist Today?

    The phrase Taxation Without Representation is still important today even though it needs to be explained in a way that makes sense for times. In the United States a good example of this is what happens in Washington, D.C.

    The people who live in Washington, D.C. Pay taxes to the government but they do not get to vote for people to represent them in the Senate and they do not have a voting member in the House like people who live in the other states do.

    The city of Washington, D.C. It itself has used the phrase Taxation Without Representation to talk about this situation for a time. You can find information about this on the website ocp.dc.gov.

    Just because a business does not like a tax that does not mean it is an example of Taxation Without Representation.

    Most people and businesses today. Work in a system where they have representatives who make laws about taxes. This is very different from what happened a time ago when the colonies disagreed with the government about taxes and representation.

    Taxation Without Representation is not about paying taxes that you do not like, it is about not having any say in how you are governed and that is what makes the situation in Washington, D.C. A good example of Taxation Without Representation.

    What Does Taxation Without Representation Mean for Businesses?

    For businesses, the concept becomes especially interesting because companies are affected by tax policy even though businesses themselves are not individual voters.

    A business may be affected by decisions involving:

    • Corporate income taxes
    • Pass-through taxation
    • Payroll taxes
    • Sales taxes
    • Excise taxes
    • Property taxes
    • Business licensing fees
    • Import duties
    • Local taxes
    • Tax credits
    • Industry-specific taxes

    The IRS identifies several major categories of federal business taxes, including income tax, estimated tax, self-employment tax, employment taxes, and excise tax. (IRS)

    The tax consequences also depend heavily on the structure of the business.

    A sole proprietorship, partnership, corporation, S corporation, and LLC can have different federal tax treatment and filing requirements.

    This is why business owners should not think of “business tax” as a single tax.

    How Businesses Have Representation in the Tax System

    Businesses have several ways to participate in the political and policy process.

    1. Voting

    Business owners and employees can vote for candidates whose tax and economic policies align with their interests.

    Voting is one of the most direct forms of political representation.

    2. Contacting Legislators

    Business owners can communicate with elected representatives about proposed legislation.

    For example, a small-business owner could explain how a proposed tax increase might affect:

    • Hiring
    • Expansion
    • Cash flow
    • Prices
    • Capital investment

    This allows lawmakers to hear from people directly affected by tax policy.

    3. Industry Associations

    Businesses often participate in industry associations that advocate for particular policy positions.

    These organizations may conduct research, communicate with legislators, submit comments, and educate members about proposed legislation.

    4. Public Policy Advocacy

    Companies can participate in lawful advocacy and public policy discussions.

    Large corporations may have dedicated government-relations teams, while small businesses may rely on chambers of commerce or industry groups.

    5. Public Comment and Regulatory Participation

    Not every business-related rule comes directly from Congress.

    Government agencies also create regulations under authority granted by law.

    Businesses may have opportunities to participate in regulatory processes through comments, hearings, industry consultations, and other lawful channels.

    This means representation is broader than simply voting every few years.

    Why Tax Representation Matters to Small Businesses

    Small business owner reviewing tax documents and calculating expenses at a desk with a laptop, calculator, paperwork, and tax-related business icons.

    Large corporations often have dedicated accounting, legal, tax, and government-relations departments.

    Small businesses usually do not.

    A small business owner may personally handle:

    • Bookkeeping
    • Payroll
    • Taxes
    • Hiring
    • Sales
    • Customer service
    • Compliance
    • Operations

    That makes changes in tax policy particularly important.

    For example, a change in payroll taxation could affect employment costs.

    A change in business deductions could alter taxable income.

    A change in sales-tax requirements could affect pricing and compliance.

    A change in local property taxes could increase the cost of operating a physical location.

    TThe IRS emphasizes that businesses can have federal, state, and local tax responsibilities, particularly when they have employees or operate across jurisdictions.

    For small businesses, therefore, understanding tax policy is not merely a political exercise. It can become a practical business management issue, which is where understanding what a business controller does can be useful.

    Taxation Without Representation vs. High Taxes

    These concepts are often confused.

    A high tax is not automatically taxation without representation.

    Consider two hypothetical businesses.

    Business A

    Business A operates in a state where lawmakers are elected by residents. The state legislature increases the corporate tax rate.

    The owner disagrees with the increase and believes it will hurt the company.

    That is a tax-policy disagreement, not necessarily taxation without representation.

    Business B

    Business B operates under a governing authority where taxpayers have no meaningful elected representation in the legislative body imposing the tax.

    That situation is much closer to the historical concept of taxation without representation.

    The distinction matters because the phrase describes a political relationship, not simply the size of the tax bill.

    How Tax Policy Can Affect Business Decisions

    Taxes influence business decisions in ways that go beyond the amount paid to the government.

    1. Hiring Decisions

    Businesses consider total employment costs when deciding whether to hire.

    Employment taxes can form part of that cost.

    The IRS notes that employers may have responsibilities involving federal income-tax withholding, Social Security and Medicare taxes, and federal unemployment taxes.

    2. Investment Decisions

    Tax rules can influence whether a company purchases equipment, expands facilities, or invests in new technology.

    Tax deductions and credits may change the financial calculation, while sales tax compliance can also affect the overall cost of business purchases and investments.

    3. Pricing

    Businesses may incorporate certain taxes into their pricing decisions.

    For consumer-facing companies, changes in sales or excise taxes can affect final prices and demand.

    4. Business Location

    State and local tax differences can influence where businesses establish operations.

    However, taxes are only one factor. Businesses may also consider labor availability, infrastructure, customers, regulations, transportation, and real estate costs.

    5. Cash Flow

    Tax obligations can affect when money leaves a business.

    Federal income tax is generally structured as a pay-as-you-go system, meaning businesses may need to make payments during the year rather than waiting until the annual return is filed. (IRS)

    Representation, Accountability, and Business Confidence

    A healthy tax system requires more than simply collecting revenue.

    Businesses also need predictability.

    Imagine a company planning a five-year expansion.

    It may invest millions of dollars in:

    • Equipment
    • Buildings
    • Employees
    • Technology
    • Inventory
    • Training

    If tax laws change unpredictably, the company’s financial projections can become less reliable.

    This is one reason businesses pay attention not only to tax rates but also to:

    • Legislative proposals
    • Tax incentives
    • Deduction rules
    • Compliance requirements
    • Filing deadlines
    • Regulatory changes
    • State and local policies

    Representation provides a mechanism for taxpayers to communicate concerns about these policies.

    Taxation and the U.S. Constitution

    The modern U.S. tax system is built on constitutional authority.

    Article I, Section 8, Clause 1 gives Congress the power to lay and collect federal taxes. The Constitution also places limits and conditions on that power. (Constitution.gov)

    The Constitution’s Origination Clause is another important part of the system.

    Revenue bills must originate in the House of Representatives, although the Senate can propose or agree to amendments. (Congress.gov)

    This structure reflects the broader constitutional principle that taxation should occur through established representative institutions.

    In other words, modern U.S. taxation is not based on the British colonial model that inspired the original protest.

    Taxation Without Representation and Washington, D.C.

    Washington, D.C. Offers one of the modern examples of why the phrase keeps coming up.

    People who live in the District pay taxes but do not have voting representation in Congress like people who live in a state.

    The government of the District has actually used the phrase “Taxation Without Representation” in its efforts. (Ocp.dc.gov) For companies that are based in Washington, D.C. this issue can therefore be seen as part of the political environment where local businesses work.

    It is important to make a difference between the political representation of residents and the separate legal and tax responsibilities that are placed on businesses.

    A business does not stop paying a tax just because its owners do not agree with the system.

    Tax responsibilities still apply unless a real law or an exemption says something.

    Can a Business Refuse to Pay Taxes Because It Claims There Is No Representation?

    No.

    Disagreeing with taxation policy does not automatically provide a legal basis for refusing to pay taxes.

    Businesses are generally required to comply with applicable federal, state, and local tax laws.

    The IRS provides businesses with systems for filing and paying taxes, including electronic filing and payment options. (IRS)

    A business that believes a tax is incorrect should use appropriate legal and administrative processes rather than simply stop paying.

    Depending on the situation, legitimate options may include:

    • Filing an amended return
    • Requesting an administrative review
    • Challenging an assessment
    • Appealing through the appropriate process
    • Seeking professional tax advice
    • Pursuing litigation when legally appropriate

    The historical slogan should therefore be understood as a principle concerning political representation, not as a general excuse for tax noncompliance.

    Why Tax Transparency Matters to Businesses

    Representation works best when taxpayers can understand what governments are doing.

    Businesses benefit when tax systems are:

    1. Transparent

    Companies should be able to determine what they owe and why.

    2. Predictable

    Businesses need reasonable stability when making long-term investments.

    3. Administratively manageable

    Complex tax requirements can create significant compliance costs, especially for small businesses.

    4. Accountable

    Taxpayers should have avenues to challenge incorrect assessments and participate in policy debates.

    5. Consistent

    Similar businesses should generally be able to understand how rules apply to them.

    These principles are closely connected to the broader idea behind taxation without representation: taxpayers should not be treated as passive sources of revenue without meaningful avenues for accountability.

    How Business Owners Can Stay Informed About Tax Policy

    You do not need to become a constitutional scholar to understand how tax policy affects your company.

    A practical approach can include the following.

    1. Monitor Legislative Changes

    Keep track of federal and state proposals that could affect your industry.

    2. Follow Official Tax Authorities

    The IRS provides business tax information covering filing, payment, employment taxes, estimated taxes, and other obligations. (IRS)

    State and local tax authorities are also important sources of information.

    3. Work With Tax Professionals

    An accountant, CPA, enrolled agent, or tax attorney can help interpret complicated tax rules.

    4. Understand Your Business Structure

    Your business structure can influence how taxes are calculated and reported. The IRS specifically notes that business structure affects the taxes a business must pay and how those taxes are handled. (IRS)

    5. Participate in Business Organizations

    Industry groups and local business organizations can help business owners understand policy developments and participate in public discussions.

    6. Keep Accurate Records

    Good records make it easier to calculate tax liabilities, claim legitimate deductions, respond to tax authorities, and make informed financial decisions.

    Accounting software can also help businesses organize financial data, track expenses, manage taxes, and maintain accurate records

    Taxation Without Representation in the Digital Economy

    The idea becomes even more interesting as businesses increasingly operate across borders.

    A digital company might have:

    • Customers in multiple states
    • Employees working remotely
    • Contractors in different jurisdictions
    • International customers
    • Digital products
    • Online advertising revenue
    • Cloud infrastructure spread across regions

    This creates complicated questions about which governments have authority to tax particular activities.

    The business may feel economically connected to multiple jurisdictions at once.

    As commerce becomes more digital, businesses increasingly need to understand not only how much tax they owe, but also which government has the authority to impose it and under what legal framework.

    That does not mean every cross-border tax is taxation without representation.

    Rather, it highlights why jurisdiction, legal authority, transparency, and political accountability remain important concepts in modern taxation.

    Common Misconceptions About Taxation Without Representation

    Myth 1: It Means Any Tax Is Unfair

    False.

    The phrase specifically concerns taxation imposed without meaningful political representation.

    Myth 2: The American Revolution Happened Only Because Taxes Were Too High

    Oversimplified.

    Taxation was part of the conflict, but representation, constitutional authority, political rights, trade restrictions, and self-government were also central issues.

    Myth 3: Businesses Can Stop Paying Taxes If They Disagree With Government

    False.

    Businesses generally remain legally responsible for applicable taxes.

    Myth 4: Representation Only Means Voting

    Not necessarily.

    Representation can involve elections, legislative advocacy, public participation, industry organizations, regulatory processes, and other lawful mechanisms.

    Myth 5: The Concept Is Only Historical

    Not entirely.

    The phrase remains part of modern political debate, including discussions surrounding Washington, D.C. and federal representation. (ocp.dc.gov)

    Why Taxation Without Representation Still Matters in 2026

    The phrase remains relevant because the underlying question has not disappeared:

    Who gets to make decisions that require people and businesses to contribute money to the government?

    Modern economies are much more complicated than the colonial economy, but the fundamental relationship between taxation and political authority remains important.

    Businesses today operate within tax systems created through federal, state, and local governments.

    They must understand:

    • Who imposes the tax
    • What authority supports the tax
    • Who makes the rules
    • How tax changes are proposed
    • How taxpayers can participate
    • What compliance obligations apply
    • What legal remedies are available

    The IRS’s current business guidance illustrates just how extensive these obligations can be. Depending on the business and circumstances, federal responsibilities can include income taxes, employment taxes, estimated taxes, self-employment taxes, excise taxes, and information reporting. (IRS)

    This makes tax literacy an important business skill.

    Taxation Without Representation: Key Takeaways for Businesses

    For business owners, the most important lessons are straightforward:

    1. Taxation without representation is primarily a political concept, not simply a complaint about high taxes.
    2. The phrase originated in the colonial conflict with Britain, when colonists objected to taxation by a Parliament in which they lacked elected representation. (PBS)
    3. Modern U.S. taxation operates through constitutional and representative institutions. Congress has constitutional authority to impose federal taxes, subject to constitutional limitations. (Constitution.gov)
    4. Businesses have numerous tax obligations, and those obligations vary according to business structure and circumstances. (IRS)
    5. Political participation matters to businesses because tax policies can affect hiring, investment, pricing, expansion, and cash flow.
    6. Disagreement with a tax does not eliminate a legal obligation to pay it.
    7. Tax representation is ultimately about accountability and political voice, not about eliminating taxes altogether.

    Frequently Asked Questions

    What is taxation without representation in simple terms?

    Taxation without representation means being required to pay taxes to a government without having meaningful elected representation in the body that imposes those taxes.

    Why did the colonists say “no taxation without representation”?

    American colonists objected to British taxes because they believed Parliament was imposing taxes on them even though the colonies did not elect representatives to Parliament. The dispute therefore concerned political representation and authority, not simply the amount of tax. (PBS)

    What is an example of taxation without representation today?

    Washington, D.C. is a commonly cited modern example because District residents pay federal taxes but lack voting representation in Congress equivalent to residents of the states. (ocp.dc.gov)

    Does taxation without representation apply to businesses?

    The historical principle primarily concerns political representation of taxpayers. Businesses are affected by tax laws and can participate in the political and policy process through owners, employees, associations, advocacy, and other lawful channels.

    Can businesses refuse to pay taxes because they disagree with tax policy?

    No. A disagreement with tax policy does not normally eliminate a business’s legal tax obligations. Businesses should use appropriate administrative or legal procedures to challenge taxes they believe are incorrect.

    What taxes do businesses typically pay?

    Depending on their structure and activities, businesses may have federal income tax, estimated tax, employment tax, self-employment tax, excise tax, and other state or local tax obligations. (IRS)

    Why is taxation important to businesses?

    Taxes can affect profitability, cash flow, hiring, investment, pricing, expansion, and business location. Understanding tax policy can therefore help businesses make better financial and strategic decisions.

    Conclusion

    Taxation without representation is more than a phrase from an American history textbook. It captures a fundamental question about the relationship between taxpayers and government: if people and businesses are required to contribute money to the government, what mechanisms give them a voice in the decisions that create those obligations?

    For American colonists, the question became a major source of conflict with Britain and helped fuel the movement toward independence.

    For businesses today, the issue looks different. Modern companies operate within a constitutional system where elected lawmakers establish tax laws and government agencies administer them. 

    Businesses can vote through their owners and employees, communicate with representatives, participate in industry organizations, engage in public policy discussions, and use established legal processes to challenge government decisions.

    At the same time, the underlying principle remains valuable.

    Tax systems work best when taxpayers understand what they are paying, why they are paying it, who created the rules, and how they can participate in the political process.

    For business owners, that makes taxation without representation more than a historical slogan. It is a useful starting point for thinking about tax policy, accountability, transparency, representation, and the economic decisions that shape the business environment.