

If you’ve ever looked at a balance sheet and wondered, “Is accumulated depreciation an asset?” you’re not alone. This is one of the most common accounting questions among students, small business owners, and even new accountants.
The short answer is: No, accumulated depreciation is not an asset. It’s known as a contra asset account, which means it reduces the value of a fixed asset on the balance sheet.
That answer sounds simple, but understanding why accumulated depreciation exists and how it works is what really matters.
What Is Accumulated Depreciation?
Accumulated depreciation is the total depreciation recorded for an asset since the day it was purchased and used by a business.
Businesses buy long-term assets such as:
- Machinery
- Vehicles
- Buildings
- Computers
- Office furniture
- Equipment
These assets lose value over time because of:
- Wear and tear
- Aging
- Obsolescence
- Daily use
Instead of recording the entire cost as an expense immediately, businesses spread the cost over the asset’s useful life. This process is called depreciation.
Accumulated depreciation simply keeps track of the total amount depreciated so far.
For example:
- A company buys a machine for $50,000
- The machine depreciates by $5,000 every year
- After 3 years, accumulated depreciation becomes $15,000
This means the machine’s book value is now:
$50,000 − $15,000 = $35,000
So while the machine still appears on the balance sheet at its original cost, accumulated depreciation reduces its carrying value.
Is Accumulated Depreciation an Asset?
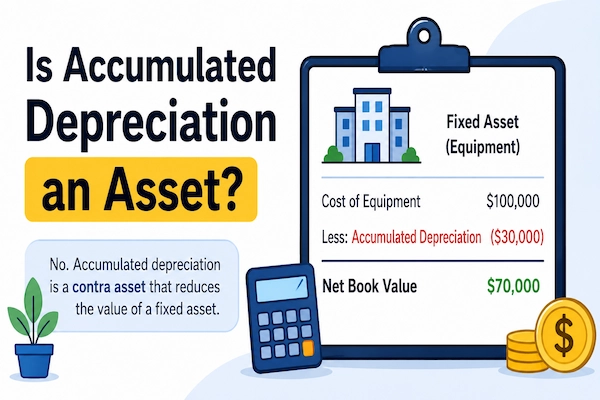
No, accumulated depreciation is not an asset.
It is classified as a:
Contra Asset Account
A contra asset account is an account that offsets or reduces the balance of another asset account.
In accounting:
- Regular asset accounts usually have a debit balance
- Contra asset accounts carry a credit balance
Accumulated depreciation reduces the recorded value of fixed assets to show a more realistic current value.
For example:
| Asset | Amount |
| Equipment | $100,000 |
| Less: Accumulated Depreciation | ($30,000) |
| Net Book Value | $70,000 |
In this case:
- Equipment is the actual asset
- Accumulated depreciation is reducing that asset’s value
- Net book value is the remaining carrying amount
That’s why accumulated depreciation is not considered an independent asset.
Why Businesses Use Accumulated Depreciation
Accumulated depreciation exists to help businesses follow the matching principle in accounting.
The matching principle says expenses should be recorded in the same period as the revenue they help generate.
Imagine buying machinery for $120,000 that lasts 10 years.
If the company recorded the entire $120,000 as an expense in Year 1:
- Year 1 profits would look unusually low
- Future years would show inflated profits
That wouldn’t accurately represent business performance.
Instead, the company spreads the cost over the asset’s useful life.
So if annual depreciation is $12,000:
- Every year records $12,000 depreciation expense
- Accumulated depreciation grows each year
- Financial statements stay more accurate
This creates a fairer picture of profitability and asset value.
Where Does Accumulated Depreciation Appear on the Balance Sheet?
Accumulated depreciation appears under the assets section of the balance sheet.
However, it’s shown as a negative figure directly below the related fixed asset.
Example:
| Fixed Assets | Amount |
| Building | $500,000 |
| Less: Accumulated Depreciation | ($80,000) |
| Net Building Value | $420,000 |
This format helps investors, lenders, and business owners understand:
- Original asset cost
- Total depreciation taken
- Remaining book value
The net value gives a clearer picture of what the asset is worth from an accounting perspective.
Is Accumulated Depreciation a Liability?
No, accumulated depreciation is not a liability either.
Liabilities represent obligations or debts a business owes, such as:
- Loans
- Accounts payable
- Taxes payable
- Wages payable
Accumulated depreciation does not represent money owed to anyone.
Instead, it simply tracks how much of an asset’s value has been used over time.
That’s why accountants classify it as a contra asset account rather than a liability.
Is Accumulated Depreciation an Expense?
This is another area where people get confused.
Depreciation Expense vs Accumulated Depreciation
These two terms are related but not identical.
| Depreciation Expense | Accumulated Depreciation |
| Recorded for one accounting period | Total depreciation since purchase |
| Appears on income statement | Appears on balance sheet |
| Temporary account | Permanent balance sheet account |
| Reduces annual profit | Reduces asset carrying value |
Think of it this way:
- Depreciation expense is the yearly charge
- Accumulated depreciation is the running total
For example:
Year 1
- Depreciation expense = $5,000
- Accumulated depreciation = $5,000
Year 2
- Depreciation expense = $5,000
- Accumulated depreciation = $10,000
Year 3
- Depreciation expense = $5,000
- Accumulated depreciation = $15,000
The expense resets every year, but accumulated depreciation keeps growing.
How to Calculate Accumulated Depreciation
The most common method is the straight-line depreciation method.
Straight-Line Depreciation Formula
Annual Depreciation Expense =
(Asset Cost − Salvage Value) ÷ Useful Life
Where:
- Asset Cost = purchase price
- Salvage Value = estimated value at end of useful life
- Useful Life = estimated years of use
Example Calculation
A company purchases office equipment for:
- Cost = $20,000
- Salvage Value = $2,000
- Useful Life = 6 years
Step 1: Calculate Annual Depreciation
($20,000 − $2,000) ÷ 6 = $3,000 per year
Step 2: Calculate Accumulated Depreciation
| Year | Annual Depreciation | Accumulated Depreciation |
| 1 | $3,000 | $3,000 |
| 2 | $3,000 | $6,000 |
| 3 | $3,000 | $9,000 |
| 4 | $3,000 | $12,000 |
After 4 years, accumulated depreciation equals $12,000.
Journal Entry for Accumulated Depreciation
Every time depreciation is recorded, businesses make this journal entry:
| Account | Debit | Credit |
| Depreciation Expense | XXX | |
| Accumulated Depreciation | XXX |
Example:
If annual depreciation is $4,000:
| Account | Debit | Credit |
| Depreciation Expense | $4,000 | |
| Accumulated Depreciation | $4,000 |
This entry:
- Increases expenses on the income statement
- Increases accumulated depreciation on the balance sheet
- Reduces net income
- Reduces asset carrying value
Types of Assets That Use Accumulated Depreciation
Accumulated depreciation is mainly used for tangible fixed assets.
Examples include:
1. Buildings
Commercial properties lose value over time because of aging and usage.
2. Machinery
Manufacturing equipment becomes less efficient over time.
3. Office Equipment
Computers, printers, and office furniture lose value as technology changes.
4. Factory Equipment
Industrial assets wear down from continuous production.
Assets That Do Not Use Depreciation
Not every asset is depreciated.
1. Land
Land generally does not lose value through normal use, so businesses do not depreciate it.
2. Intangible Assets
Items like:
- Trademarks
- Patents
- Copyrights
- Software licenses
usually use amortization instead of depreciation.
Different Methods of Depreciation
Although straight-line depreciation is most common, businesses can use other methods too.
1. Straight-Line Method
Equal depreciation expense every year.
Best for:
- Office furniture
- Buildings
- General equipment
2. Declining Balance Method
Higher depreciation in earlier years.
Best for:
- Technology assets
- Vehicles
- Equipment that loses value quickly
3. Double Declining Balance Method
An accelerated depreciation method that records even higher early-year depreciation.
4. Units of Production Method
Depreciation depends on actual usage.
Best for:
- Manufacturing machines
- Production equipment
No matter which method is used, accumulated depreciation keeps increasing throughout the asset’s life.
Why Accumulated Depreciation Matters
Accumulated depreciation is important for several reasons.
a. Accurate Financial Reporting
It prevents assets from appearing overvalued on the balance sheet.
b. Better Profit Measurement
Businesses spread asset costs across multiple years rather than recording one huge expense.
c. Tax Benefits
Depreciation expenses can reduce taxable income.
d. Asset Management
Companies can track aging equipment and plan replacements.
e. Investor Transparency
Investors get a clearer understanding of how efficiently assets are being used.
Real-Life Example of Accumulated Depreciation
Imagine a logistics company buys delivery trucks for $300,000.
The trucks:
- Have a useful life of 10 years
- Have a salvage value of $50,000
Annual Depreciation
($300,000 − $50,000) ÷ 10 = $25,000
After 4 Years
Accumulated depreciation becomes:
4 × $25,000 = $100,000
Balance Sheet Presentation
| Trucks | $300,000 |
| Less: Accumulated Depreciation | ($100,000) |
| Net Book Value | $200,000 |
This tells readers that the trucks have already consumed part of their useful value.
Common Mistakes People Make About Accumulated Depreciation
Understanding accumulated depreciation becomes easier once you know the common misconceptions.
Mistake 1: Thinking It’s a Liability
It’s not money owed to anyone.
Mistake 2: Thinking It’s an Expense
Depreciation expense is the yearly charge. Accumulated depreciation is the running total.
Mistake 3: Assuming It Reflects Market Value
Accumulated depreciation affects book value, not actual resale value.
An asset may:
- Be worth more than book value
- Be worth less than book value
- Still function perfectly after full depreciation
Mistake 4: Forgetting Contra Asset Rules
Contra asset accounts increase with credits, unlike normal assets.
Accumulated Depreciation vs Amortization
People often confuse depreciation and amortization.
Here’s the difference:
| Depreciation | Amortization |
| Used for tangible assets | Used for intangible assets |
| Applies to machinery, vehicles, buildings | Applies to patents, trademarks, software |
| Creates accumulated depreciation | Creates accumulated amortization |
Both concepts reduce the carrying value of long-term assets over time.
What Happens When an Asset Is Sold?
When a business sells an asset:
- The asset account is removed
- Accumulated depreciation is removed
- Any gain or loss is recorded
Example
A machine originally cost $40,000.
Accumulated depreciation = $25,000.
Book value = $15,000.
If the machine sells for $18,000:
- The company records a $3,000 gain
If it sells for $10,000:
- The company records a $5,000 loss
This process helps businesses maintain accurate accounting records.
How Accumulated Depreciation Impacts Financial Statements
Accumulated depreciation affects multiple financial statements.
Balance Sheet
Reduces fixed asset value.
Income Statement
Depreciation expense lowers net income.
Cash Flow Statement
Depreciation is added back because it’s a non-cash expense.
This is why depreciation matters heavily in business valuation and financial analysis.
Can Accumulated Depreciation Exceed Asset Cost?
No, accumulated depreciation cannot exceed the depreciable value of an asset.
Once the asset reaches its salvage value:
- Depreciation stops
- Accumulated depreciation stops increasing
For example:
- Asset cost = $50,000
- Salvage value = $5,000
- Maximum accumulated depreciation = $45,000
Why Investors and Accountants Pay Attention to Accumulated Depreciation
Accumulated depreciation can reveal important business insights.
Aging Assets
High accumulated depreciation may suggest equipment is old and may soon need replacement.
Capital Expenditure Trends
Investors can see whether a company regularly invests in new assets.
Profitability Analysis
Depreciation affects net income and earnings.
Tax Planning
Businesses use depreciation strategies to manage taxable income.
Frequently Asked Questions
1. Is accumulated depreciation a current asset?
No. It is a contra asset account connected to long-term fixed assets.
2. Is accumulated depreciation debit or credit?
Accumulated depreciation normally carries a credit balance.
3. Why is accumulated depreciation negative on the balance sheet?
Because it reduces the value of fixed assets.
4. Is depreciation an expense?
Yes. Depreciation expense appears on the income statement.
5. Is accumulated depreciation a permanent account?
Yes. It remains on the balance sheet until the asset is sold or removed.
6. Does accumulated depreciation affect cash?
No directly. Depreciation is considered a non-cash expense.
7. Can land have accumulated depreciation?
No. Land is generally not depreciated.
Final Thoughts
So, is accumulated depreciation an asset? The answer is clearly no.
Accumulated depreciation is a contra asset account used to reduce the carrying value of fixed assets over time.
It helps businesses:
- Follow accounting principles
- Present more accurate financial statements
- Match expenses with revenue
- Track asset usage and aging
- Calculate realistic book values